


Wall Street index futures are gaining between 0.2% and 0.3%, while investors’ attention today will focus primarily on the September US labor market report: NFP, the unemployment rate and wage growth, which could have the strongest impact on expectations for the Fed. In Europe, attention will turn to the preliminary euro area CPI reading, particularly core inflation, as a stronger print could limit the ECB’s room to ease monetary policy.
- Despite the cautious rise in US equities, demand for safe-haven assets continues to dominate global bond markets. Yields are falling in the US, Japan, Australia and New Zealand, while US Treasuries are holding most of Thursday’s price gains. The defensive tone reflects a combination of risks, including tensions in credit markets, elevated commodity prices, persistent inflationary pressure, and political and fiscal uncertainty.
- Yesterday’s rebound in bonds pushed the 10-year Treasury yield back from its highest levels since 2002. Even so, the S&P 500 recovered its initial losses after US manufacturing data showed a sharp increase in raw material costs, keeping inflation concerns alive.
- Europe remains the weaker link. Concerns over France’s fiscal and political outlook continue to support a higher risk premium on French debt, while German bonds remain relatively stable. Asian indices are also down around 0.6%, with China’s Hang Seng standing out negatively after falling nearly 3%.
- Sentiment across equity markets is clearly weaker. Asian indices are heading for their worst week since July, while European equities are on track for their weakest week since April. Pressure is also visible in the UK, where long-dated gilt yields briefly climbed above 6%, highlighting the scale of stress in the bond market.
- The US Dollar Index remains strong and is heading for a third consecutive weekly gain, supported by the relative resilience of the US economy. Brent crude has paused its advance and is trading near $102 after two consecutive positive sessions, while copper is heading for its biggest weekly decline since May.
- For today’s US NFP report at 12:30 PM GMT, consensus expects nonfarm payrolls to rise by around 90,000, while the unemployment rate is seen holding at 4.1%. Geopolitics also remains an important risk factor, particularly amid tensions between Washington and Tehran, which continue to sustain uncertainty around inflation and energy prices.
- Fed Vice Chair Philip Jefferson suggested that policymakers may need more time to assess whether further rate increases are necessary. New York Fed President John Williams made similar remarks earlier, saying there was no urgency to consider another hike following September’s rate increase.
- Donald Trump said that, based on the information he had heard so far, Iran may have been behind the foiled terrorist attack in Israel. The Pentagon is reportedly considering deploying another aircraft carrier and an additional 10,000 troops to the Middle East, while the US is deploying additional Patriot air-defense systems to Saudi Arabia and near Qatari energy facilities, according to Axios.
- Iranian sources cited by Mehr News reported that a supertanker with a capacity of around 2.5 million barrels, which was allegedly transiting the Strait of Hormuz “illegally,” was struck about 8 km off the coast of Oman. The vessel is reportedly on fire, although the reports still require independent confirmation.
- Vladimir Putin said yesterday that Russia is ready for peace talks and wants to conclude them as quickly as possible, but only on terms Moscow considers acceptable to the Russian public. He also said Russia needs security guarantees regarding Ukraine, while referring to Russian territorial gains in September. Ukraine said Russian forces struck one of the bridges today and shelled Kyiv.
- Nike shares (NKE.US) are falling 8% to their lowest level since 2013. The company reported first-quarter EPS of $0.48 versus $0.44 expected, down from $0.49 a year earlier, while revenue came in at $11.21 billion versus the $11.33 billion consensus. Nike brand revenue reached $10.95 billion versus $11.09 billion expected. Gross margin improved to 42.8% from 42.2% a year earlier, but EBIT in China came in at $248 million, well below the $312.2 million estimate, while inventories totaled $7.80 billion versus $7.96 billion expected. The company also expects fiscal 2027 revenue to decline by a high-teens percentage and adjusted EPS to come in at $1.15-$1.35, underlining ongoing pressure on demand and profitability despite the improvement in gross margin.
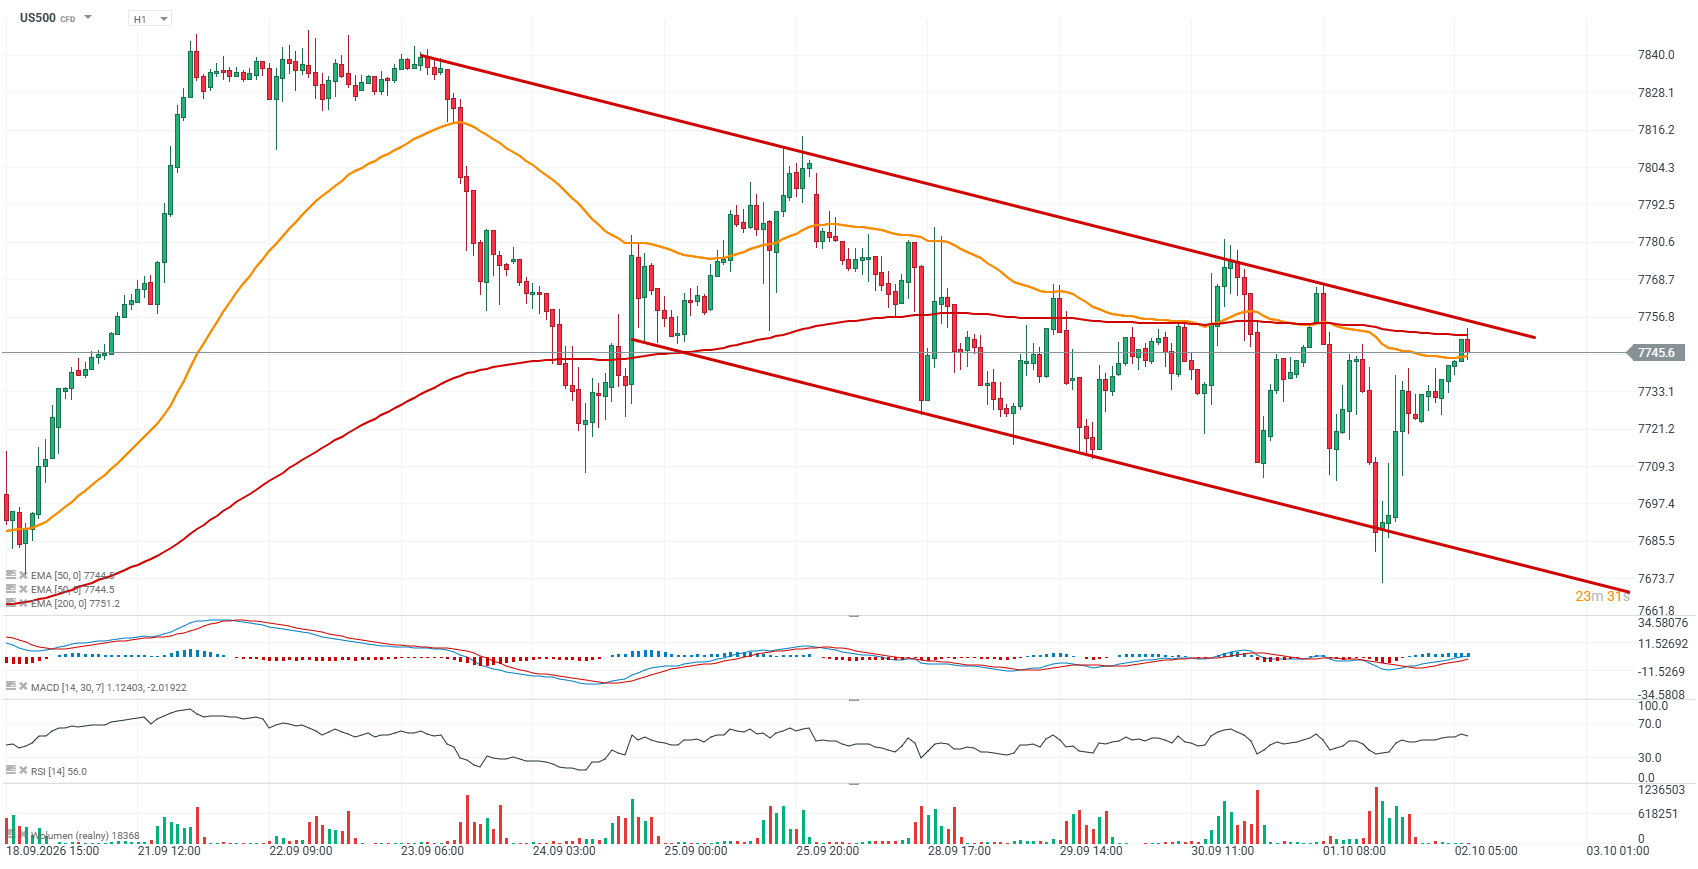
US500 chart (H1 interval)
Since September 23, the S&P 500 futures contract has pulled back and is currently trading near the upper boundary of a descending price channel, where 7,750 points appears to be a key resistance level, while the lower boundary is around 7,670 points. The benchmark is also testing its 200-day exponential moving average (EMA200) on the daily chart, and a breakout above this level would be a key short-term challenge.
 Source: XTB


Market Wrap: Tech stocks stabilize sentiment in Europe 📈 Adidas and Puma resilient despite Nike’s sell-off?

Chart of the Day: Sharp sell-off in China 📉 HK.cash posts its biggest decline since March (02.10.2026)



Daily Summary: Wall Street Recovers as Micron Shines and Oil Prices Rise Again

Stock of the Week: Micron. The Memory Cycle in the Age of Artificial Intelligence
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.