


One of the session’s top performers in the technology sector on Monday is ARM Holdings, up about 14%.
Admittedly, this move was part of a broader rebound among semiconductor makers, supported among other things by falling bond yields and oil prices. In Arm’s case, however, an additional reference point is last week’s comments by CEO Rene Haas, which significantly raised expectations for the commercial success of the company’s own processors.
In an interview with CNBC on September 16, Haas said his confidence in the company’s ability to meet demand for an “AGI CPU,” a proprietary chip specialized for agentic AI, with a value of USD 2 billion has increased since the July earnings presentation. Earlier, Arm had indicated customer interest exceeding the sales level for which it had secured supply. The CEO’s statement therefore strengthens expectations that potential orders will translate into recognized revenue.
The timing of these declarations remains important. In the July update, demand exceeding USD 2 billion related to fiscal years 2027 and 2028 combined, and secured capacity corresponded to the previously stated ability to sell USD 1 billion. Growing management confidence provides a basis for optimism, but the statement alone does not determine a formal guidance increase.
AGI CPU Changes Arm’s Economics
Arm is in a situation similar to most makers of the most advanced chips and AI development and operations hardware. The problem is no longer demand; the challenge is manufacturing capacity, which can clearly pressure the investment timeline through the pace at which revenue converts into profit and cash flows.
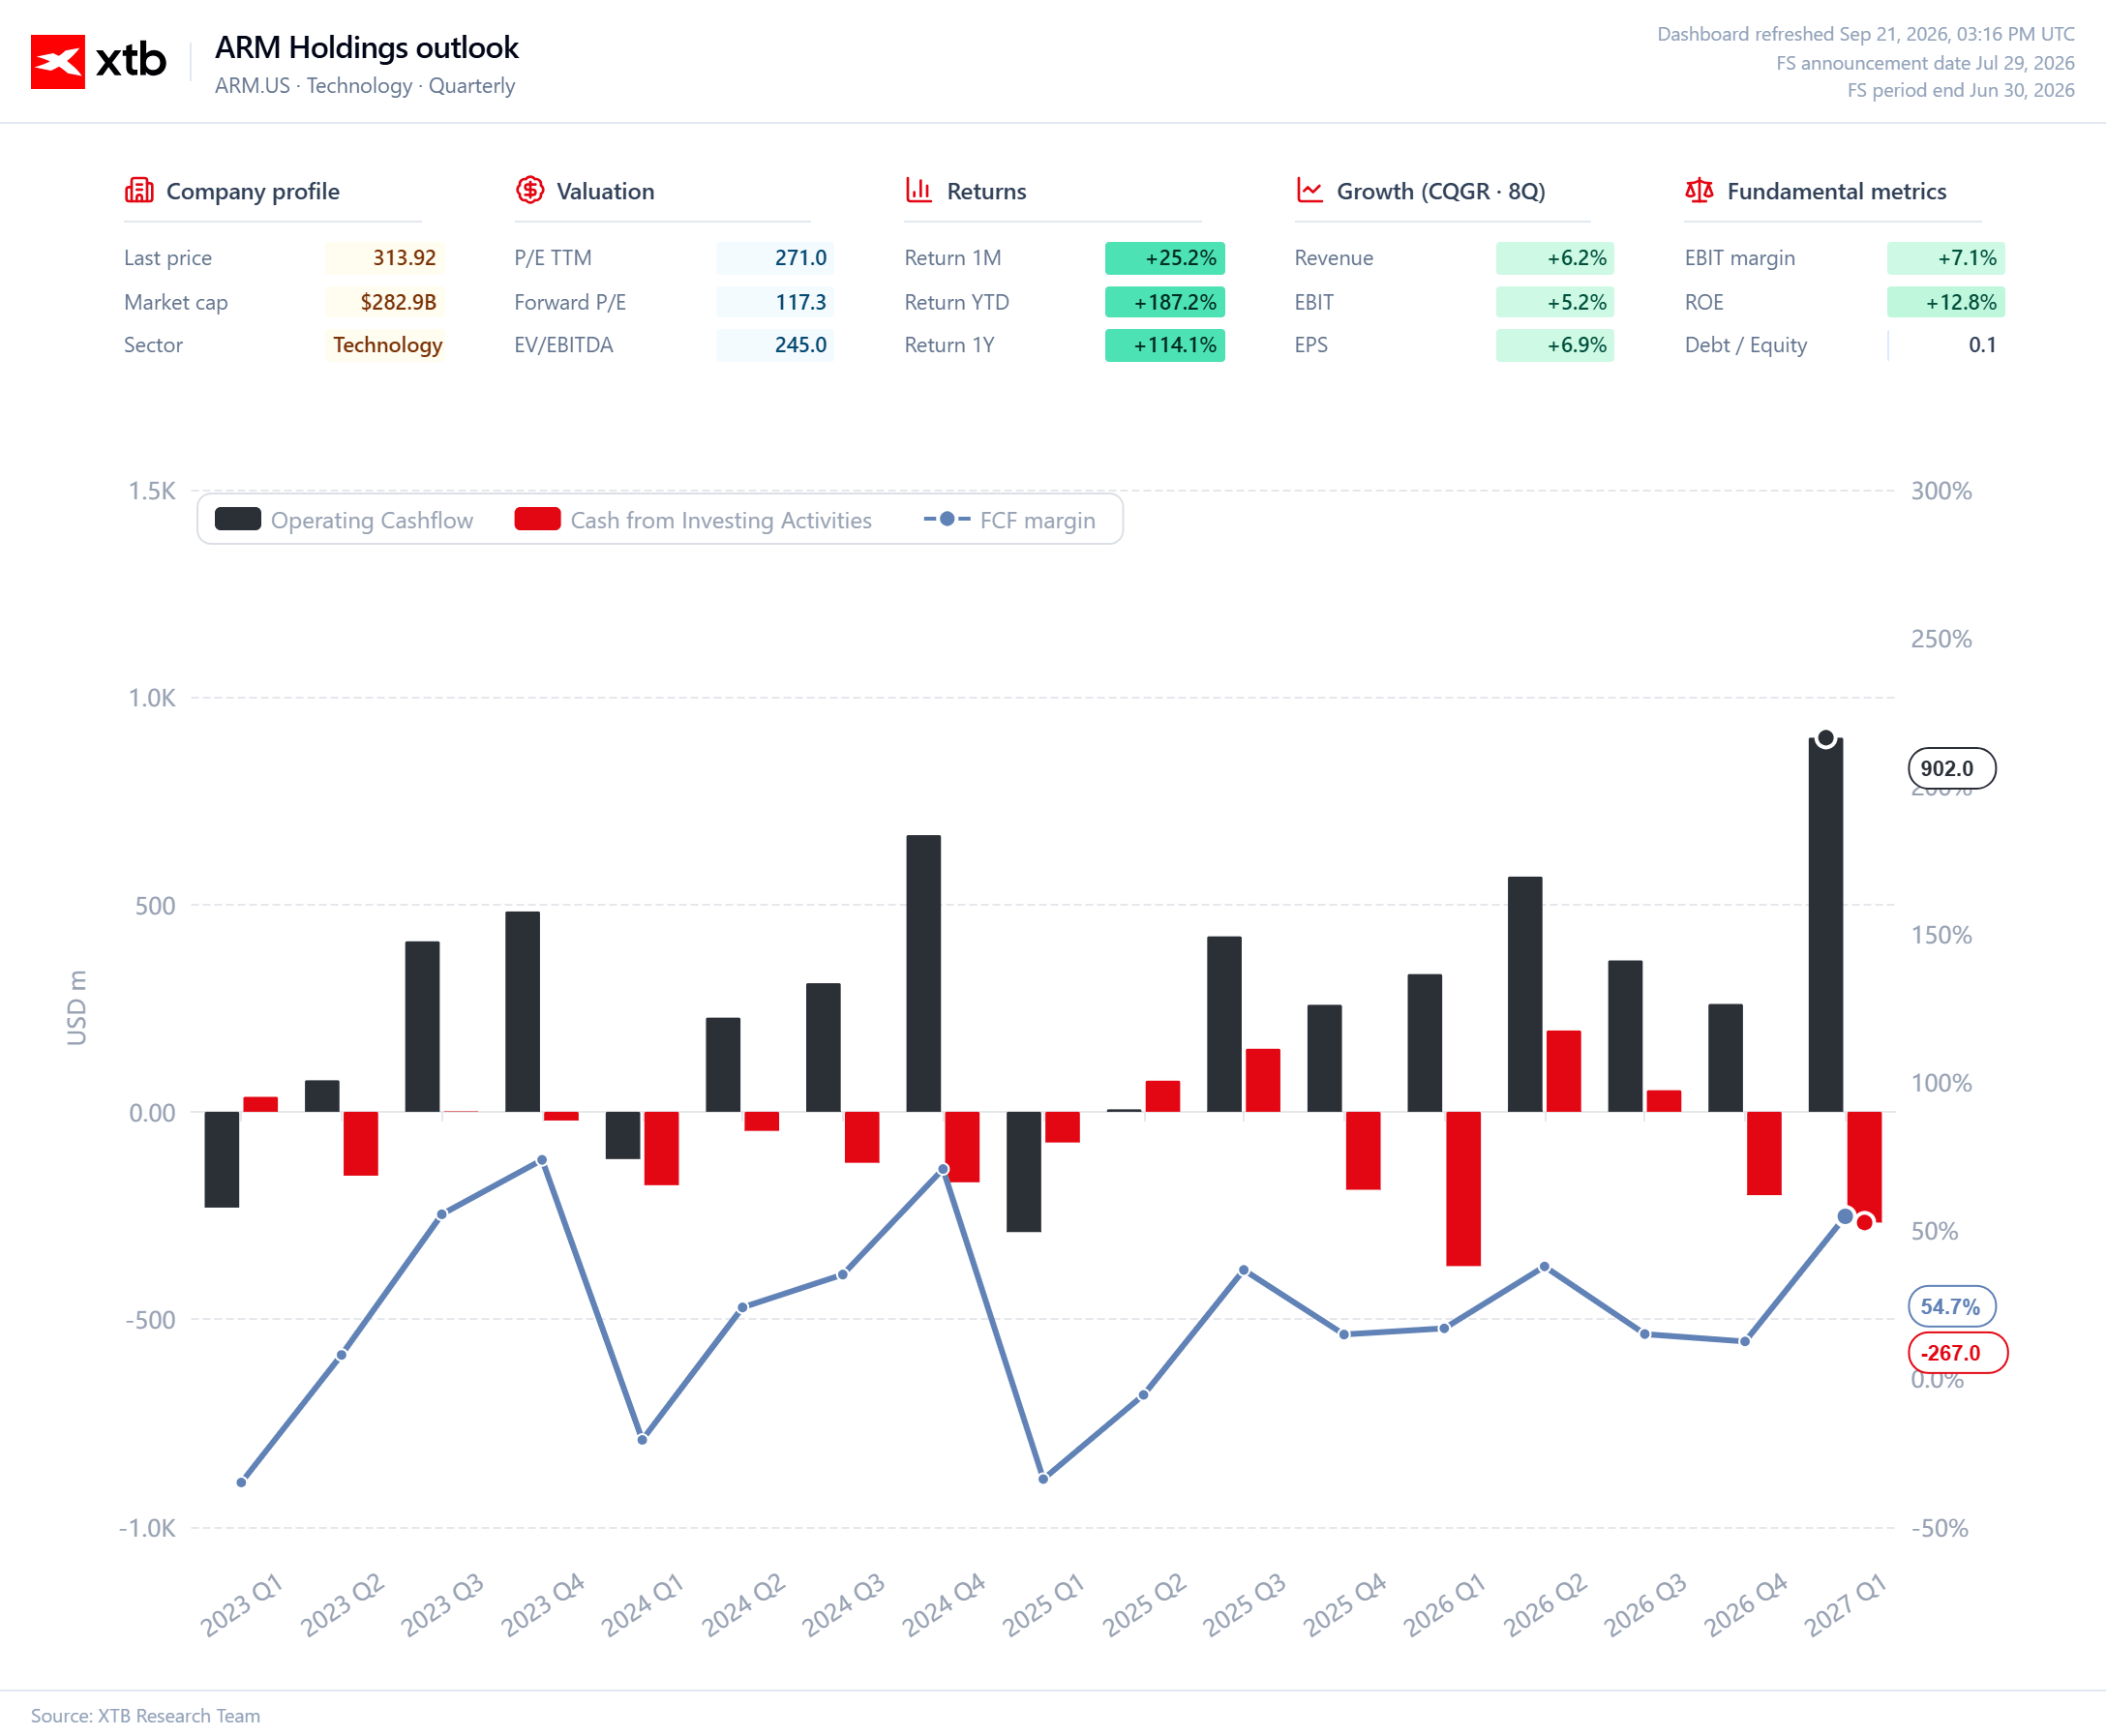
For the past decades, Arm operated on a licensing model. A structural change in demand has partly enabled and partly forced a shift of production capabilities in house. This is a major strength and asset, but beyond the costs, a key challenge is bringing additional capacity partitions online.
This shift means the ability to capture a larger share of spending on computing infrastructure. Selling finished processors increases potential revenue per deployment while also increasing the importance of manufacturing costs, supply management, and working capital.
The new processor expands Arm’s business into selling its own chips for data centers. According to Haas’s description, the product is intended to support cloud computing, work with GPU accelerators, and support applications using AI agents. Its value proposition for customers is based mainly on performance and energy efficiency, while reducing the cost and complexity of designing their own hardware.
SoftBank Increases Financing and Its Dependence on Arm’s Valuation
At the same time, SoftBank increased financing secured by Arm shares by USD 5 billion to USD 25 billion, according to Reuters. The stake in the processor designer therefore plays an important role in financing the Japanese group’s broader investment strategy.
SoftBank has also launched a bond offering totaling USD 10 billion and EUR 1 billion. The funds are intended to support the next tranche of investment in OpenAI and replace bridge financing planned for that purpose. The transaction shows the scale of capital mobilization around AI, although its announcement comes before the issuance is completed.
For Arm and SoftBank, these investments are both an opportunity and an additional risk channel. A rising share price improves the value of SoftBank’s collateral, while a deep selloff could increase pressure to post additional collateral or reduce leverage, depending on contract terms.
These obligations burden the shareholder’s financing, and their impact on Arm is primarily through the ownership structure and potential share supply.
ARM Price Chart (D1)
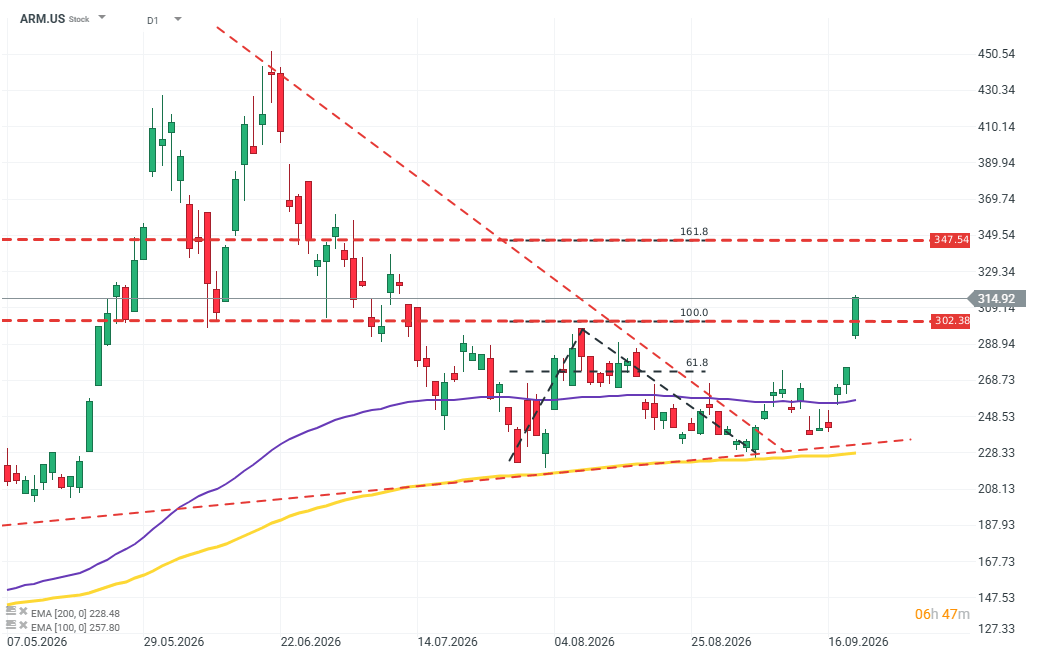
On the chart, one can observe a breakout from a descending triangle formation after holding the EMA200. Fibonacci expansion levels indicate around USD 350 as the next significant resistance level. Source: xStation5


SEC eases regulations: Does Bitcoin and Strategy benefit the most?


Daily Summary: Hawkish Fed fails to scare the markets (17.09.2026)

Nasdaq 100 Up 1.7%

US Open: Nasdaq, gold and silver surge following... an interest rate hike (17.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.