


The Bank of Japan followed in the footsteps of the Federal Reserve today, raising interest rates by 25 bps to the highest level in 31 years (the benchmark rate at 1.25%).
Figure 1: BoJ Interest Rate and Core CPI Inflation in Japan (1995 - 2026)
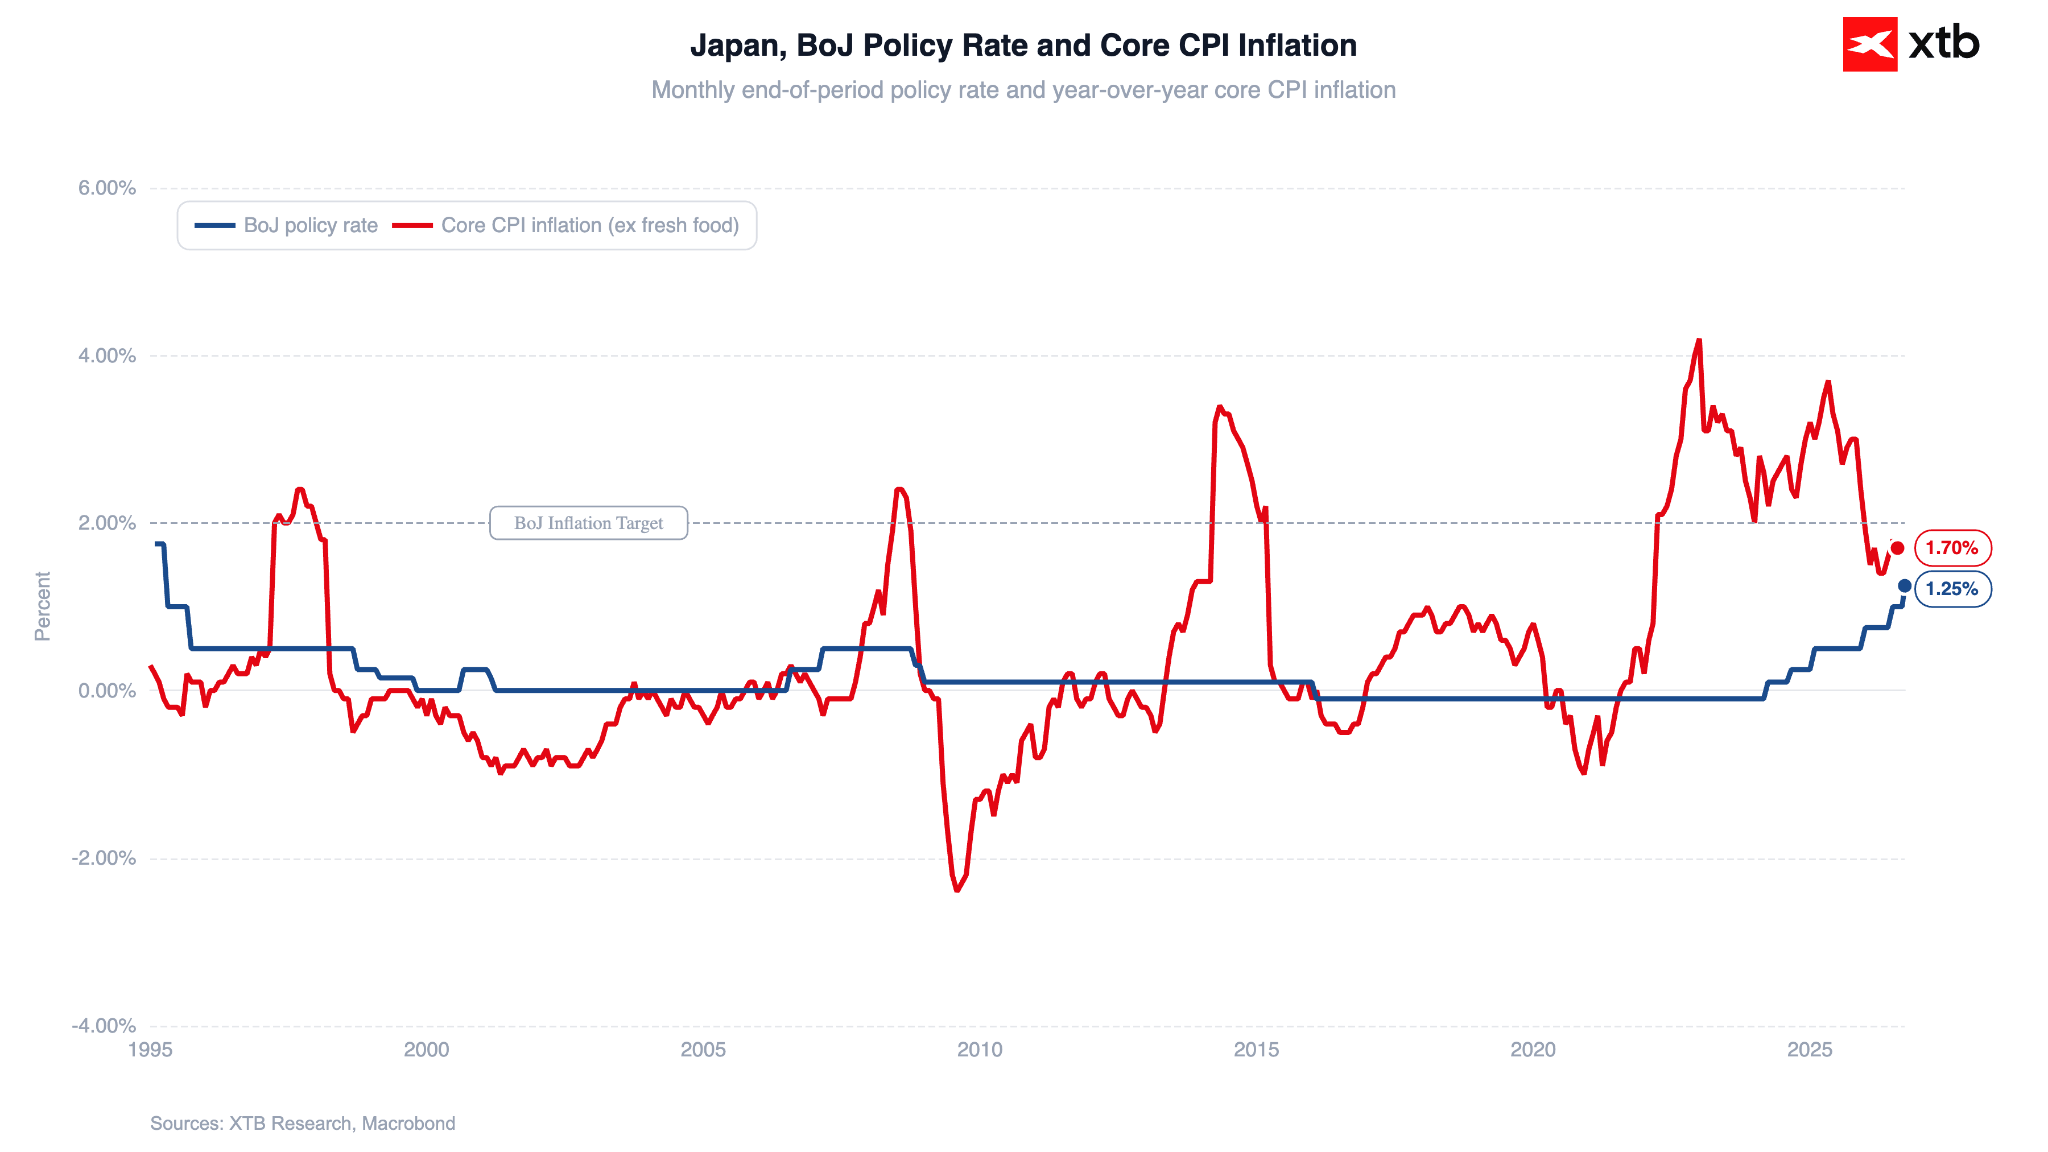 Source: XTB Research, 18.09.2026
In contrast to the dollar, which gained ground after the FOMC meeting, the yen is today surrendering some of the gains it accumulated over recent weeks.
Figure 2: Major Currencies vs. USD (14.09.2026 - 19.09.2026)
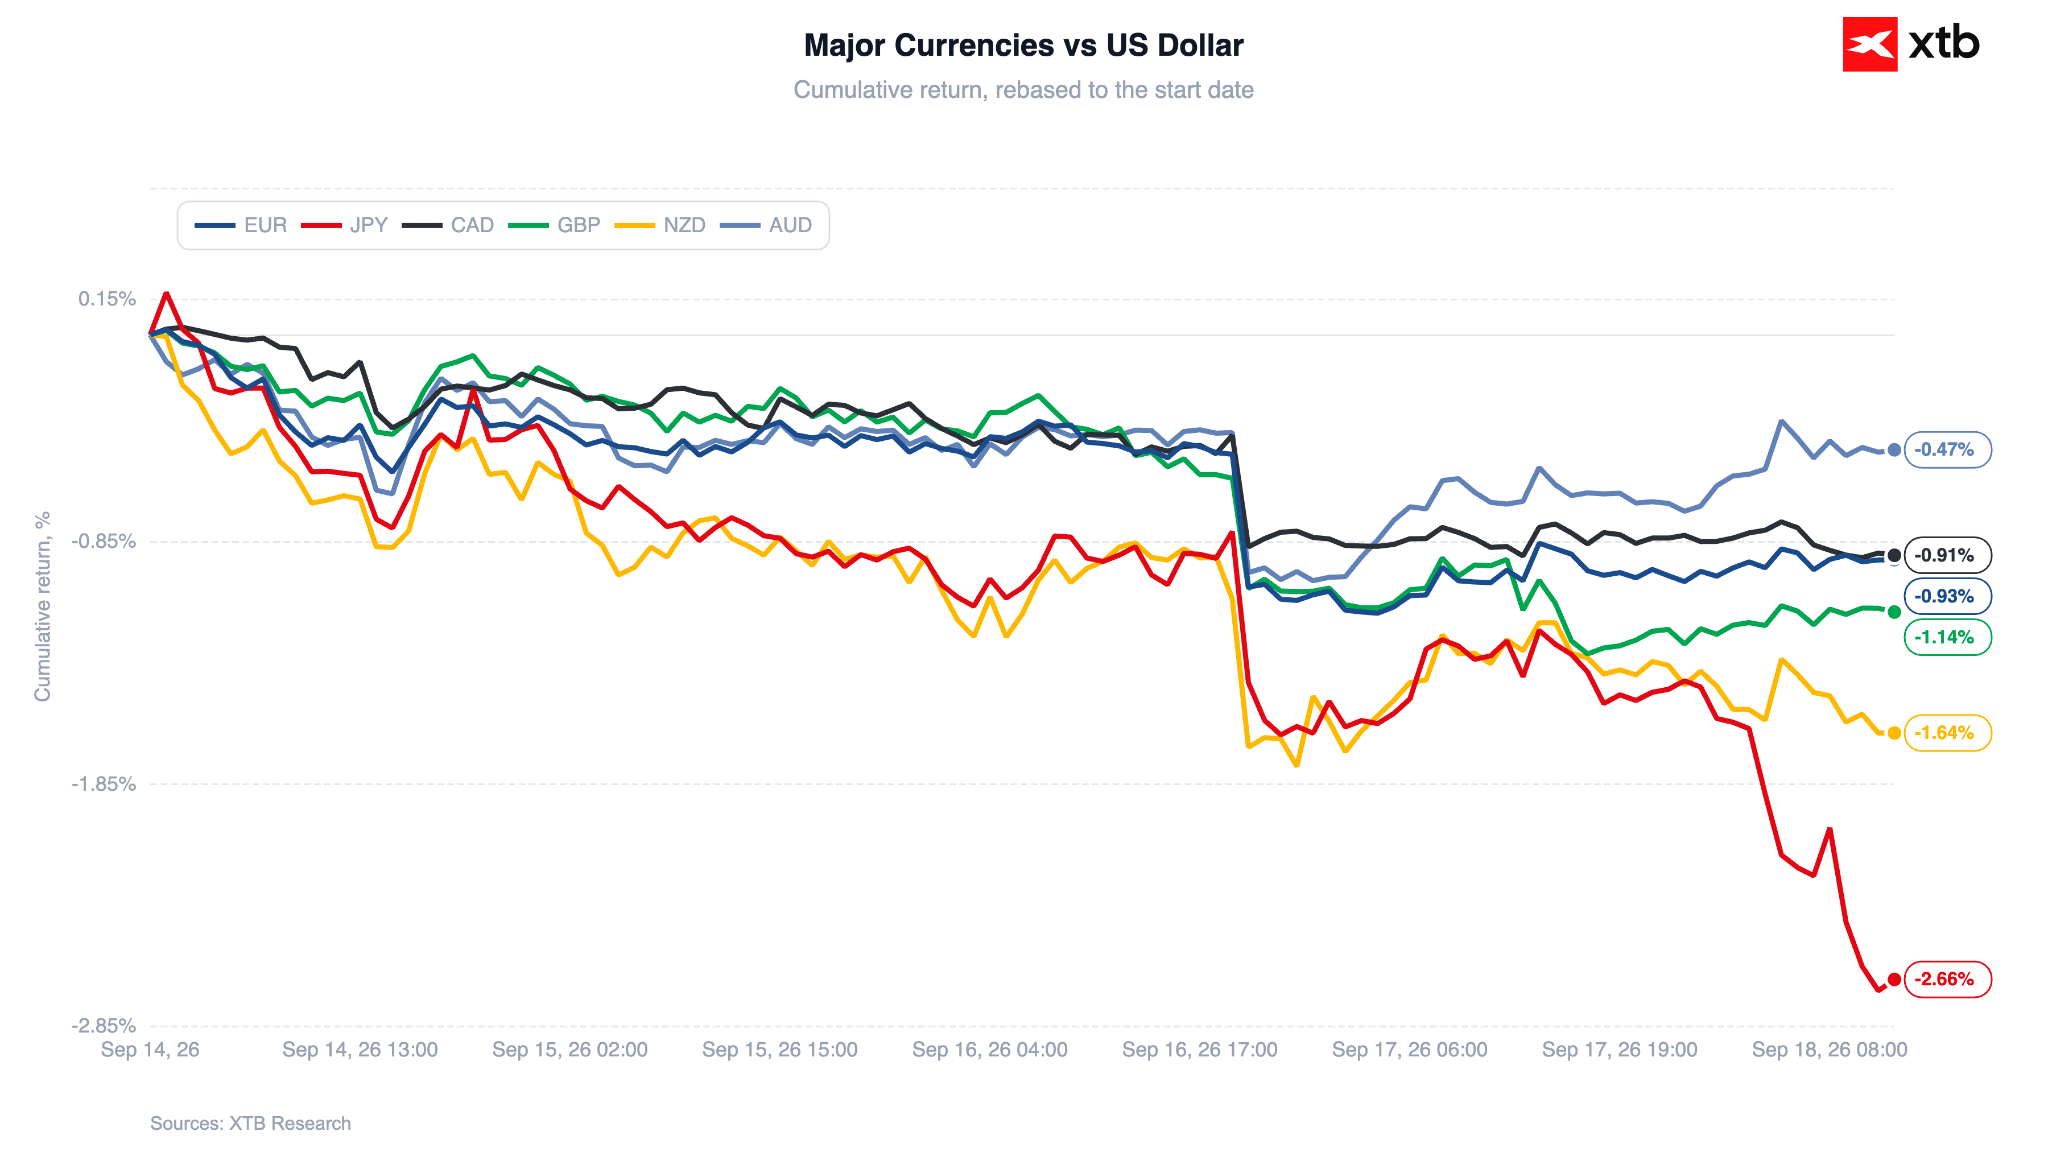 Source: XTB Research, 18.09.2026
There are at least several reasons behind this move; however, they all anchor around one key issue: the BoJ fell short of market expectations regarding its forward guidance.
Figure 3: Market-Implied BoJ Interest Rate Path (2026 - 2027)
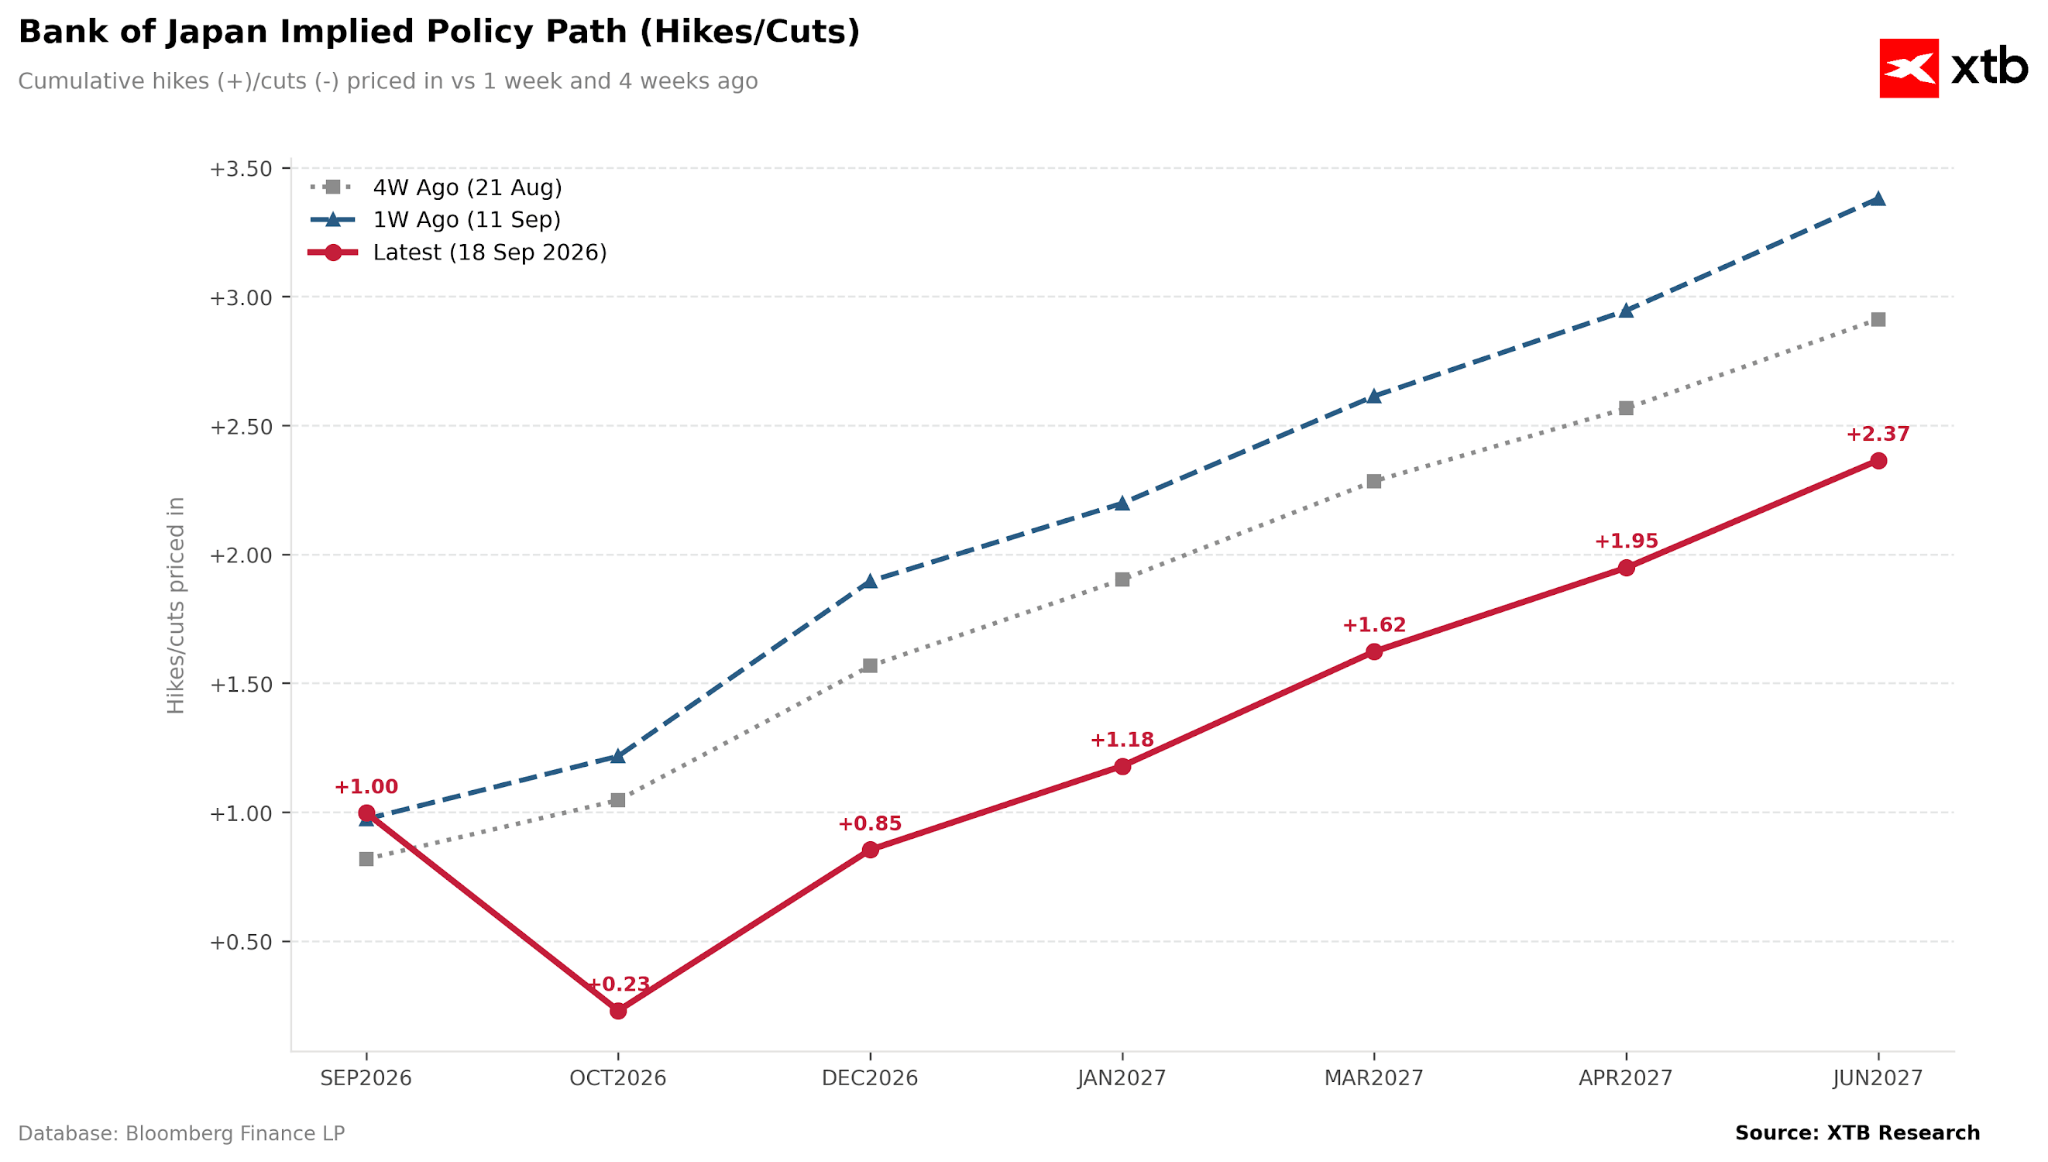 Source: XTB Research, 18.09.2026
Note: Current valuations refer to a higher base (i.e. the interest rate level following today's hike).
A Lack of Unanimity
Most importantly, the decision was not unanimous (7-2). The rate hike was opposed by Board members appointed in March by Sanae Takaichi's government: Toichiro Asada and Ayano Sato.
This is particularly significant given that Naoki Takamura and Hajime Takata, the most hawkish among the Board members, will end their terms as early as July next year. The government will once again nominate the candidates, which means the internal centre of gravity within the Board could shift towards a much more dovish stance.
Unlike ordinary bills, where a constitutional majority (two-thirds of the seats) in the House of Representatives allows the veto of the House of Councillors to be bypassed, selecting Board members requires the consent of both Houses. This restricts the government's freedom of action and may prevent the approval of ultra-dovish nominations.
Takaichi herself is perceived as a reflationist, meaning an advocate for economic policies aimed at deliberately inducing moderate inflation to stimulate demand. Her policy aligns to some extent with Abenomics, the economic vision of former Prime Minister Shinzo Abe, which assumes a loose fiscal policy, a weak yen to support exports, and active economic stimulation through state expenditure.
Ueda Not Hawkish Enough
Governor Ueda's press conference initially brought about a certain downward correction on the USDJPY pair; however, it ultimately failed to help the yen regain its footing. The Governor noted that "up until now, our short-term policy objective has been to push core inflation out of levels below 2 per cent; currently, core inflation is approaching 2 per cent, which [...] means that the policy [ed. note: monetary policy] phase has changed".
He mentioned, however, that the bank does not have a predetermined plan or a preset pace for hikes (e.g., once a quarter). Every subsequent move will be dependent on current macroeconomic data, particularly on prevailing inflation conditions.
He also sought to reassure investors, emphasising that although monetary policy is no longer ultra-loose, financial conditions in the country remain accommodative. In assessing the current economic situation, he used the phrase "mild recovery".
He confirmed that the bank must closely monitor exchange rate fluctuations. A weak yen fuels so-called imported inflation, especially in the face of high energy commodity prices; Japan covers approximately 90% of its energy demand through imports.
—
Michał Jóźwiak, Financial Markets Analyst at XTB


Hawkish remarks by BOJ Governor strengthen the yen – key takeaways
🏯Chart of the Day: Yen in a Trap. BoJ Hike That Weakened the Currency (18.09.2026)


Macro Calendar – Dovish BoJ Pivot and Key Data from Europe and the US



📊Morning Briefing: BoJ raises rates, but the yen paradoxically weakens (18.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.