


European indices are losing ground as a wave of sell-offs in companies linked to artificial intelligence has spread from the US and Asia to the Old Continent. On Monday, US indices fell sharply (S&P 500 by approx. 1.9%, Nasdaq by approx. 2.5%). Today, South Korea's KOSPI index is at its lowest since February, while in Taiwan, trading is deepening Monday's sell-off of around 6%. The catalyst is new US restrictions on China's access to advanced AI chips, and investors are additionally awaiting Nvidia's earnings after the US market close. The Stoxx Europe 600 is down approx. 0.7%, with about 80% of its companies in the red, led by technology and the consumer sector.
Against this backdrop, a transaction in the European space sector stands out. Finland's Iceye, a radar satellite operator, announced via an Italian subsidiary a takeover offer for rocket manufacturer Avio (AVIO.IT). It is offering EUR 41 per share in cash, representing a premium of approx. 21% to Monday's close and a valuation of around EUR 2.05 billion. The acquisition is to be financed with own cash and debt, and following the transaction, Iceye intends to delist Avio from the Milan stock exchange. The rationale is clear: satellites, their manufacturing, and data analytics combined with launch vehicles and propulsion would create an integrated European space and defense company. Iceye announces that within five years it will invest another billion euros in Italy (up to 400 jobs) and retain Avio's brand and workforce. However, the road to completion is long. The offer requires regulatory approvals, as well as acceptance by at least two-thirds of shareholders. Avio shares gained up to approx. 17% at the start of the session.
The second topic of the day is Deutsche Bank, which lost even over 6% in morning trading. The reason is a leak of approx. 15 million bank documents analyzed by an international team of journalists, including the "Financial Times". According to the newspaper, the bank reported suspicious transactions in the US worth approx. USD 582 million linked to Jeffrey Epstein. The documents also show that in 2017, the bank accidentally disclosed data from Donald Trump's tax filings, which current CEO Christian Sewing reportedly called a "terrible mistake". The bank emphasizes that the matters are historical in nature and points to approx. EUR 7 billion invested in control systems between 2019 and 2025. For investors, the greatest risks here are regulatory and reputational costs, rather than the direct impact on earnings.
Currency Market
- EURUSD: The euro is weakening (approx. 0.2%), with the rate falling to around 1.0970. A stronger dollar and weakness in European equities limit room for a euro rebound.
- GBPUSD: The pound is edging down slightly (by less than 0.1%), trading in the 1.3180 region.
- USDJPY: The dollar is virtually unchanged against the yen (up by less than 0.1%), with the rate remaining near 159.5. Cautious sentiment in equity markets is not translating into a notable strengthening of the yen today.
- USDPLN: The zloty is weakening (approx. 0.3%), with the rate rising to around 4.01.
Commodity Market
- Oil: Brent is gaining approx. 1.8% to around USD 93.5, and WTI approx. 2.1% to approx. USD 86.8. This is a rebound following Monday's sell-off and an approx. 22% drop in November, caused among other things by the IEA forecast projecting a supply surplus in Q4. The market is balanced by reports of attacks on tankers in the Strait of Hormuz area.
- Gold: Edging down slightly (approx. 0.2%) to approx. USD 3850 per ounce. The metal is consolidating after falling near annual lows, when some investors sold it to cover losses in tech stocks.
- Silver is rising by approx. 0.8% (to approx. USD 47.4)
- Gas: NATGAS.EU is gaining approx. 1.8%, while US Henry Hub is losing approx. 0.6%.
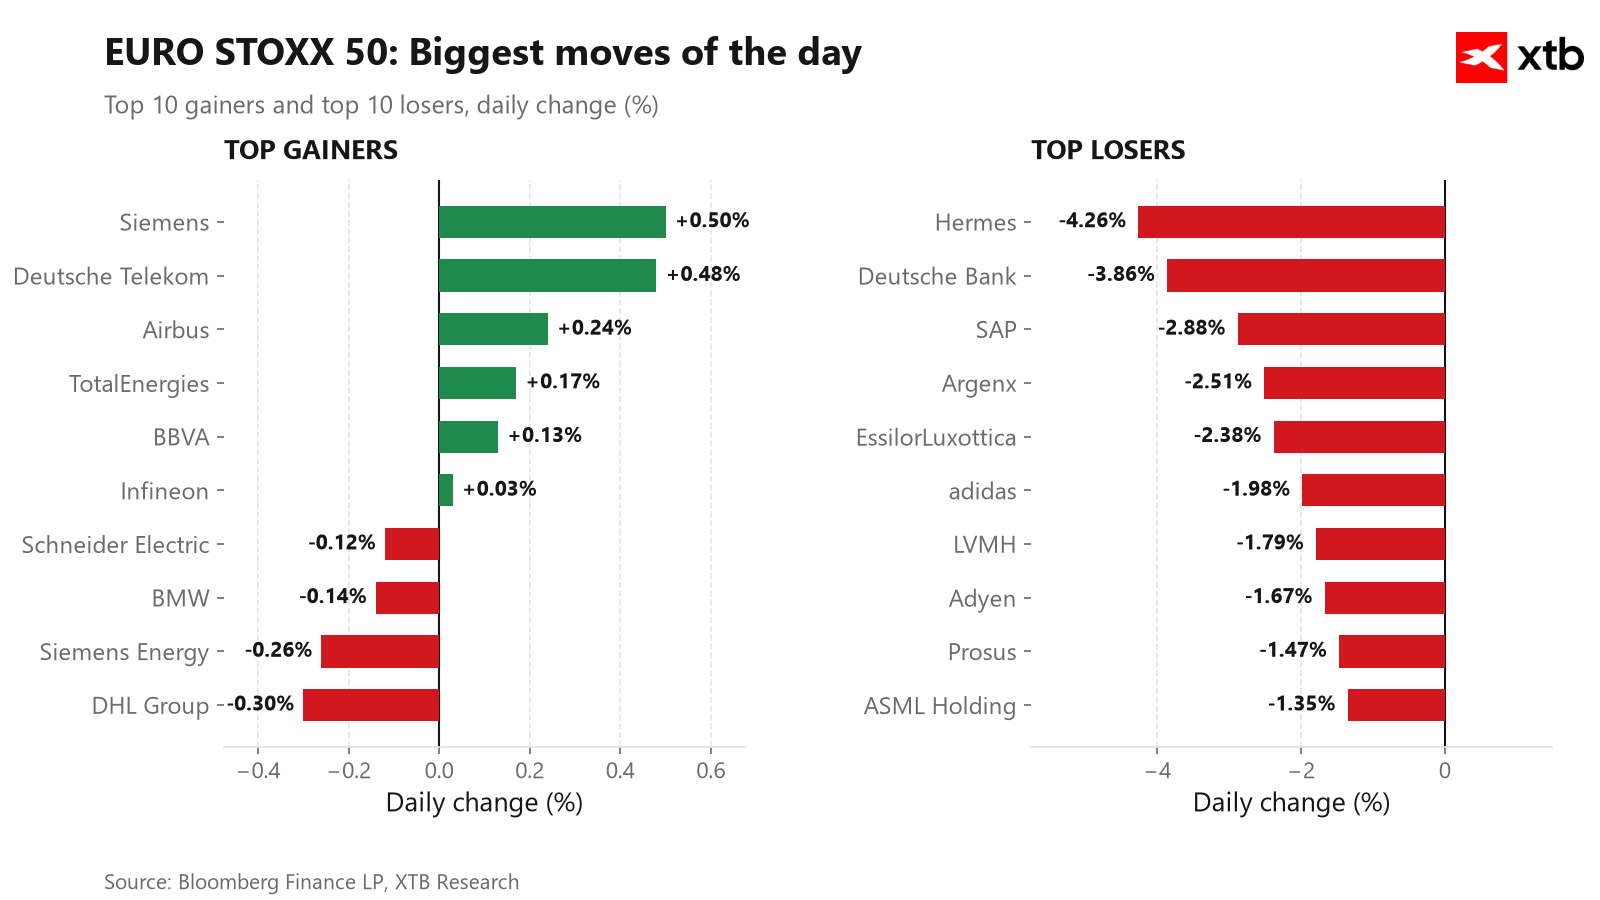
Chart 1 presents the largest price changes of companies from the Euro Stoxx 50 index
Company News
- Deutsche Bank (DBK.DE): Sell-off following reports of Epstein-linked transactions and document leak. The market is pricing in regulatory risk, while the bank assures that the matters are historical in nature. (down approx. 4.3%, after an earlier drop reaching over 6%)
- LVMH (MC.FR), Hermès (RMS.FR), EssilorLuxottica (EL.FR): The entire luxury goods sector is under pressure. The market is returning to concerns over demand in China (according to local data, jewelry sales fell by nearly 29% y/y in October) as well as Morgan Stanley's rating downgrades from last week. Hermès, considered the most resilient brand, is losing the most in the index. (LVMH: down approx. 2.2%; Hermès: nearly 4.8%; EssilorLuxottica: approx. 2.3%)
- SAP (SAP.DE) and Prosus (PRX.NL): Both companies remain under pressure from sentiment toward AI and software. We found no reports today that would explain the move, so the market attributes it to the sector. (SAP: down approx. 3%)


DAX Pulls Back for a Second Day from All-Time Highs



Daily Summary: Tech Stock Selloff Weighs on Markets, Fed Outlines AI Scenarios


US OPEN: Tech selloff continues ahead of Nvidia earnings and Anthropic’s debut

Morning Wrap: Weak Chinese data and sell-off in Asian chips hit sentiment ahead of Warsh's speech
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.