


European cocoa futures fell to their lowest level since the August 12 rollover, as the market increasingly focuses on improving near-term availability of the commodity. Higher production in Côte d’Ivoire and elevated cocoa inventories in ICE warehouses are adding pressure to prices. At the same time, the medium-term outlook remains more balanced, as forecasts for the 2026/27 season point to the risk of weaker crops in West Africa.
- Côte d’Ivoire harvested 2.06 million tonnes of cocoa between June 2025 and June 2026, up 30% from a year earlier.
- ICE cocoa inventories remain close to two-year highs at around 3.43 million bags.
- Supply risks for the 2026/27 season include weaker crop prospects in Ghana and Côte d’Ivoire, as well as the potential impact of a strong El Niño.
Higher supply from Côte d’Ivoire weighs on prices
The main source of pressure on cocoa prices remains data from Côte d’Ivoire, the world’s largest cocoa producer. Regulator Le Conseil du Café Cacao reported that the country harvested 2.06 million tonnes of cocoa between June 2025 and June 2026, compared with 1.58 million tonnes a year earlier, representing an increase of around 30%.
Data cited by Bloomberg also show that, under the international cocoa marketing year starting in October 2025, deliveries to ports reached 2.14 million tonnes by September 13, up 18% from a year earlier. Comparisons are complicated, however, by Côte d’Ivoire’s decision to move the start of its local marketing year to September 1.
According to Reuters data based on the new calendar, deliveries between September 1 and 13 reached just 26,000 tonnes, down 45.8% from the comparable period of the previous season.
High inventories confirm improving cocoa availability
Another negative factor for prices is the high level of ICE cocoa inventories. They reached a two-year high of 3.437 million bags on September 4 and remained close to that level on Thursday at around 3.429 million bags.
Barry Callebaut, the world’s largest cocoa processor, said in early September that the global cocoa market is currently well supplied. According to the company, conditions are significantly better than during the 2023/24 supply crisis, when El Niño contributed to a sharp rise in cocoa prices.
The 2026/27 season could bring renewed supply problems
Near-term supply looks comfortable, but the outlook for the next season is less favorable. Early crop assessments in Côte d’Ivoire point to weaker cherelle formation and a potential decline in production to around 1.8 million tonnes, down about 18% from 2.2 million tonnes in the 2025/26 season.
Ghana, the world’s second-largest cocoa producer, is also facing potential problems. The Ghana Cocoa Board estimated in August that production in the 2026/27 season could reach around 650,000 tonnes, compared with 750,000 tonnes a year earlier, although earlier COCOBOD projections pointed to an even lower range of 450,000–550,000 tonnes.
Disease, aging cocoa farms and unfavorable weather are adding pressure to plantations. Cloudy conditions and limited sunshine in Ghana and Côte d’Ivoire are supporting the spread of black pod disease, which is reducing the quality of part of the crop.
El Niño remains an important supply risk
In the medium term, the market continues to price in weather-related risks. The U.S. Climate Prediction Center indicated that the current El Niño could become one of the strongest in more than 75 years.
Such a weather pattern typically increases the risk of hotter and drier conditions in West Africa. This could reduce soil moisture, weaken cocoa trees and lower future yields.
These risks have already been partly reflected in global balance forecasts. StoneX cut its estimate for the global cocoa surplus in the 2026/27 season to 25,000 tonnes from 149,000 tonnes previously, while Transgraph Consulting expects the surplus to fall to 80,000 tonnes from 415,000 tonnes in 2025/26.
Cocoa demand remains mixed
Processing data show clear differences between regions. In Europe, cocoa grindings fell 4.6% y/y in Q2 to 316,400 tonnes, the lowest level for this period in six years.
At the same time, demand in North America was significantly stronger than expected. Grindings rose 7.7% y/y to 109,700 tonnes, compared with expectations for a 1% decline.
An even stronger improvement was recorded in Asia, where cocoa grindings increased 25% y/y in Q2 to 224,600 tonnes. This suggests that despite weakness in Europe, global demand is not currently providing a clear signal of further deterioration.
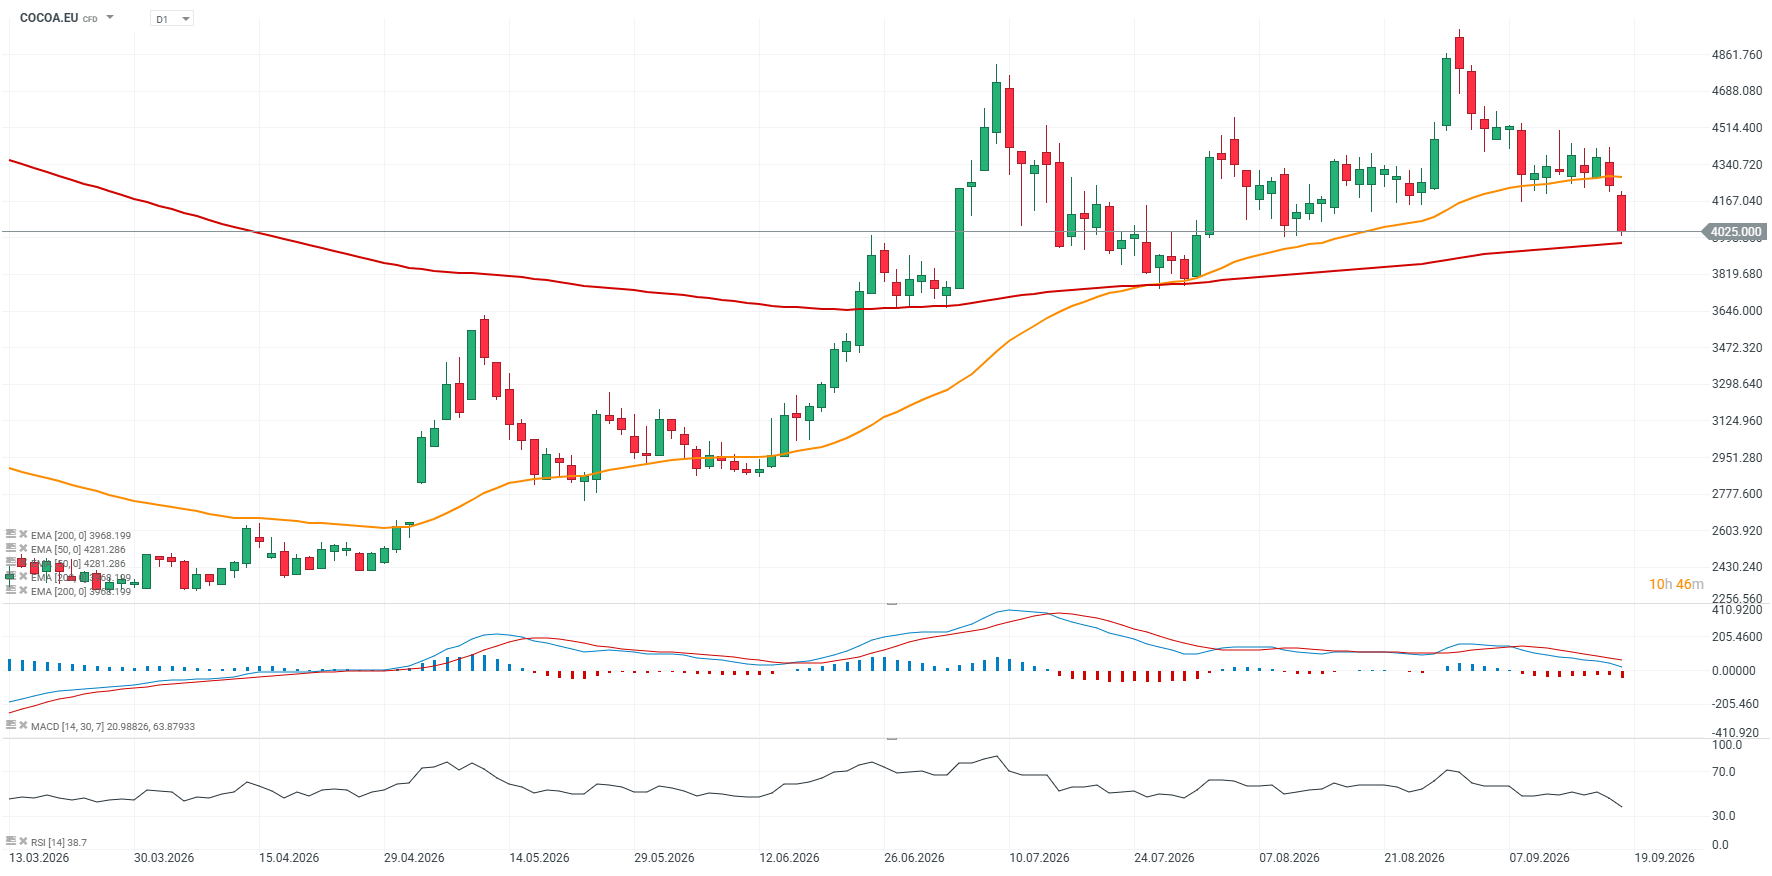
Source: xStation5


Market warp: Rate Forecasts and Semiconductors in the Spotlight


📈 Gold gains 1% and erases post-Fed losses. Are metals returning to growth



📊Morning Briefing: BoJ raises rates, but the yen paradoxically weakens (18.09.2026)


US Open: Nasdaq, gold and silver surge following... an interest rate hike (17.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.