


The latest preliminary PMI estimates for September brought a clear positive surprise on the demand side in the euro area. Economic activity in Europe is visibly accelerating, with key economies in the region, led by France and Germany, recording a strong rebound in the services sector. Despite challenges related to cost pressures and previous monetary policy tightening, the European private sector is returning to an expansion path at the fastest pace in months. The question remains, however, whether recent interest rate hikes in the euro area and rising energy commodities, such as oil and gas, will not slow down this growth.
Key PMI Data for September
Eurozone (S&P Global):
- Services PMI (Flash): 53.0 pts vs 51.5 pts expected (previous: 51.6 pts)
- Manufacturing PMI (Flash): 52.7 pts vs 52.6 pts expected (previous: 52.7 pts)
- Composite PMI (Flash): 53.1 pts vs 51.7 pts expected (previous: 52.0 pts)
Niemcy (HCOB):
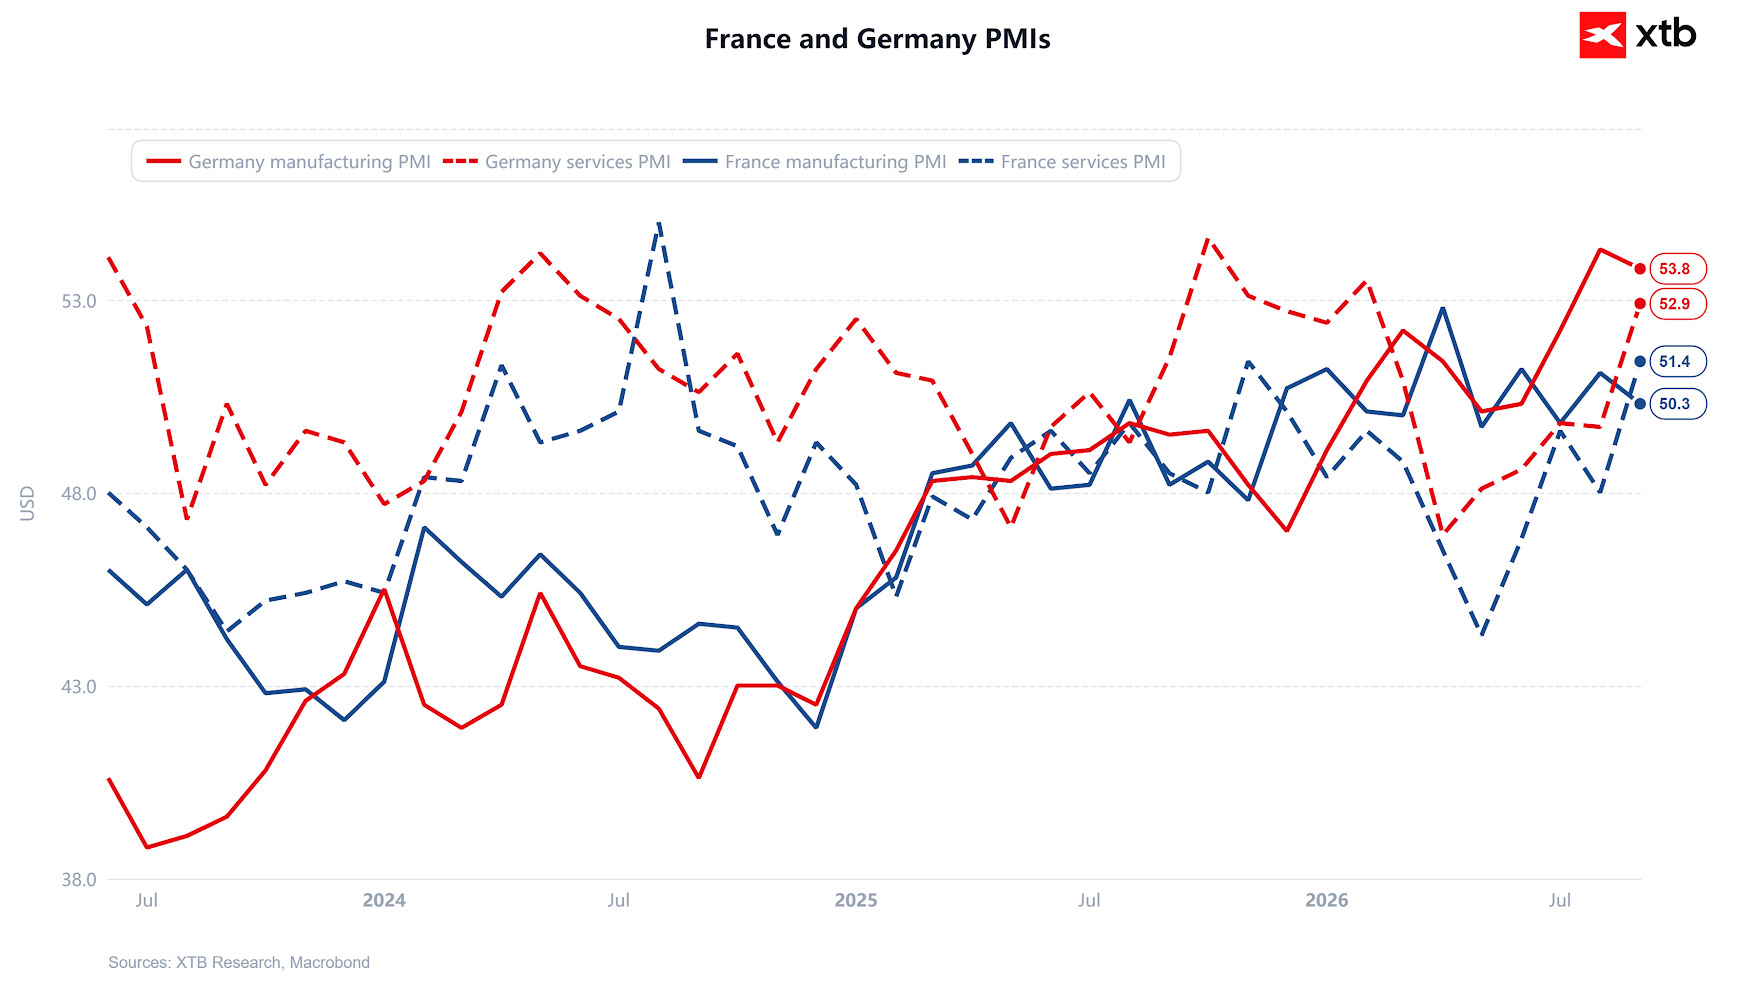
- Services PMI (Flash): 52.9 pts vs 49.9 pts expected (previous: 49.7 pts)
- Manufacturing PMI (Flash): 53.8 pts vs 54.0 pts expected (previous: 54.3 pts)
- Composite PMI (Flash): 53.8 pts vs 51.8 pts expected (previous: 51.8 pts)
Francja (S&P Global):
- Services PMI (Flash): 51.4 pts vs 48.3 pts expected (previous: 48.0 pts)
- Manufacturing PMI (Flash): 50.3 pts vs 51.0 pts expected (previous: 51.1 pts)
- Composite PMI (Flash): 51.2 pts vs 48.7 pts expected (previous: 48.5 pts)
Commentary on Data and a Dilemma for the ECB
The published data indicate clear resilience in the European economy. A particularly positive signal is the decisive return of the services sector to the expansion zone—above the 50-point threshold—in both France and Germany. In France, the aggregated Composite index reached its fastest growth rate in over two years, while for the entire euro area, it was the most dynamic rise in economic activity in nearly three and a half years.
However, the main challenge for the European Central Bank remains resurging inflationary pressure. Reports point to a renewed acceleration in input cost growth and finished goods prices, driven in part by higher fuel, energy, and raw material prices. For the ECB, improved economic activity alongside returning price pressures means that the bank cannot yet declare victory over inflation.
Although recent days brought a decline in global oil prices in response to hopes of de-escalating Middle East tensions, markets are pricing in roughly a 47% probability of another 25 bps rate hike by the ECB at its October meeting and see a strong chance of a full rate increase before the end of this year.
EURUSD Technical Analysis
Despite significantly better-than-expected readings from the European economy and recently falling oil prices, the EURUSD exchange rate reaction remained opposite to theoretical expectations. The US dollar maintains the advantage gained following the recent Federal Reserve meeting, pushing the currency pair toward a key support zone.
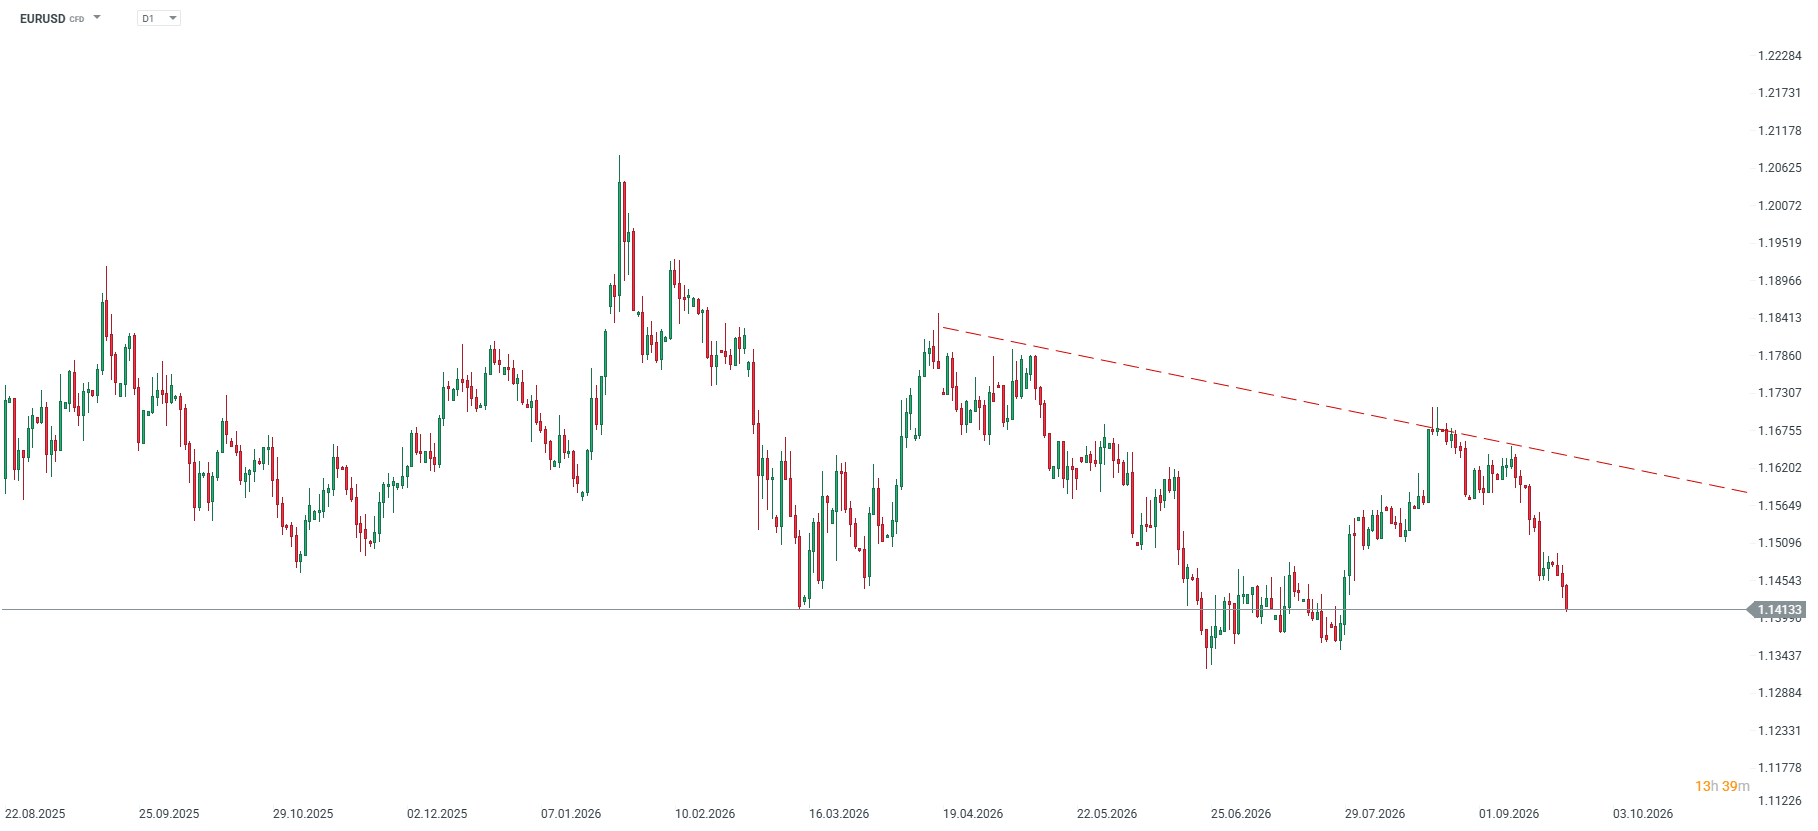
- Key support (1.1400): EURUSD quotes are approaching a broad and important support level around 1.1400. A sustained downside breakout past this barrier would open the door to a deeper sell-off toward the 1.1350 level.
- Trendline and resistance: The main structure on the daily (D1) and 4H timeframes is defined by a downtrend line. The first significant resistance in any attempt to recover losses is the local peak at 1.1495, followed by the trendline and resistance near 1.1560.
- Market scenarios: Buyers need a decisive breakout above the downtrend line to negate supply pressure and trigger a move toward 1.1560. As long as the rate stays below this line, the risk of testing and breaking the 1.1400 support remains elevated.



🛢️WTI crude tests $90. Brent below $100


Economic Calendar - Another day of central bankers' speeches. Is AUDUSD responding to inflation risks?


Morning Briefing: Global Markets Riding AI Wave, Rising Geopolitical Tensions, and Hawkish Central Banks (22.09.2026)

Chart of the Day: European Gas (NATGAS.EU) below 80 EUR, but Goldman Sachs warns of 105 EUR/MWh.
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.