

- France's composite PMI fell to 48.4 pts in October as political and fiscal crises contracted the private sector.
- Germany's composite PMI dropped to 52.8 pts while manufacturing grew and services stagnated under high inflation.
- EURUSD dropped below 1.12 following the weak French data ahead of the upcoming ECB meeting.
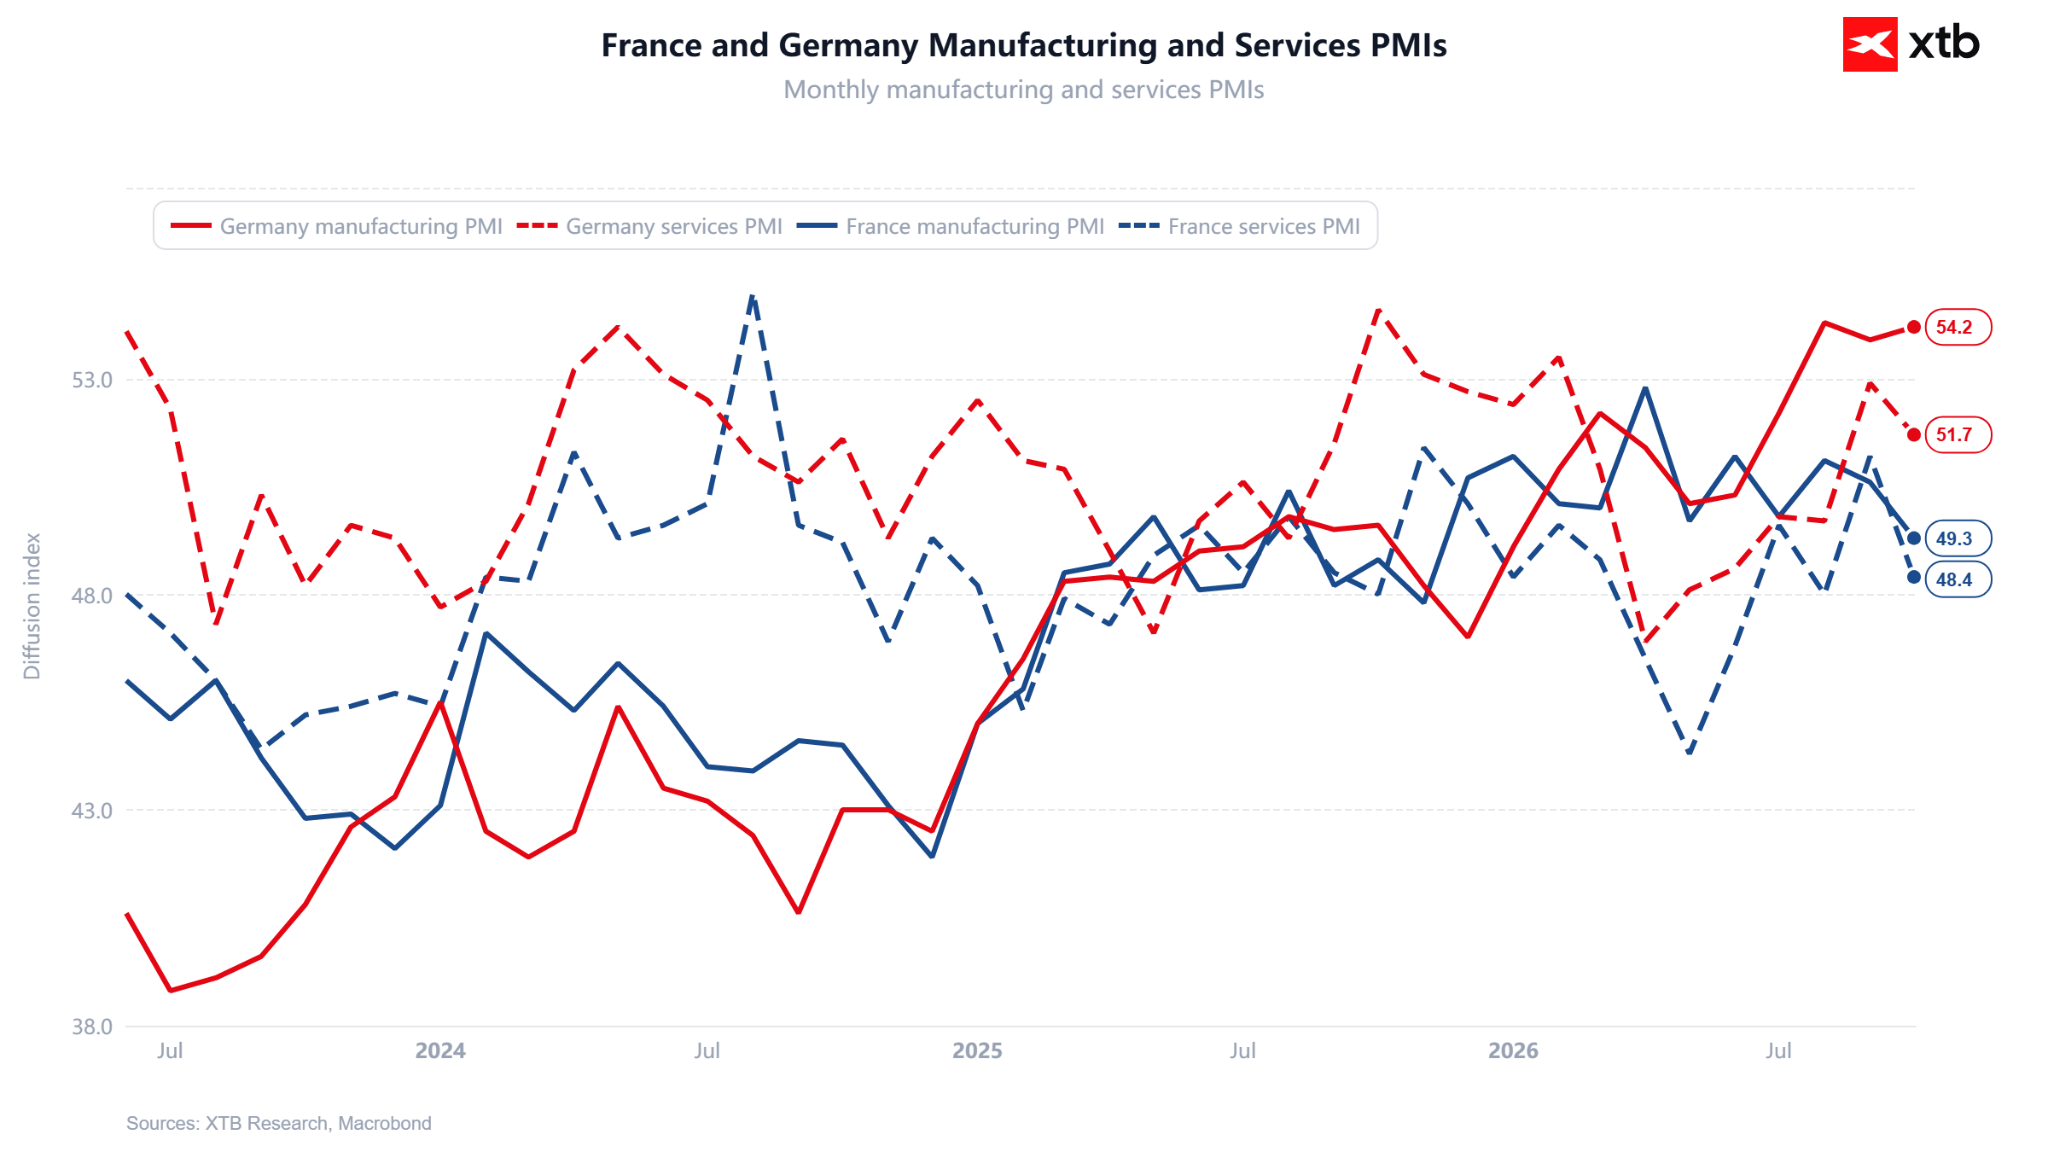
October's preliminary PMI indices showed how much the two largest economies in the eurozone are diverging. The French private sector fell into contraction territory, although in this case, taking into account recent protests and budget concerns, it should come as no surprise. The composite PMI fell to 48.4 points against expectations of 50.3 points. Both manufacturing and services found themselves below the 50-point mark simultaneously.
Germany is still growing, although slower than expected. Manufacturing positively surprised, but services are visibly weakening under the weight of high inflation. The market interpreted the data unequivocally: EURUSD dropped below 1.12, and in the background we are slowly counting down the time to the ECB meeting next Thursday.
France: clear disappointment
- Composite PMI: 48.4 pts (forecast 50.3 pts, previously 51.1 pts). This is a reading below the lowest forecast in the 50.0–51.1 range.
- Manufacturing: 49.3 pts (forecast 50.5 pts, previously 50.6 pts). This is the lowest level since November 2025.
- Services: 48.4 pts (forecast 50.7 pts, previously 51.2 pts).
- New orders: in manufacturing: 44.9 pts, lowest since July 2025; in services: 45.9 pts; composite: 45.7 pts, falling for the 11th consecutive month.
- 12-month expectations index: lowest in 6.5 years.
Germany: growth continues, but slows down
- Composite PMI: 52.8 pts (forecast 53.4 pts, previously 53.8 pts). This is the fourth consecutive month of expansion.
- Manufacturing: 54.2 pts (forecast 53.5 pts, previously 53.9 pts). This is the upper limit of forecasts and the ninth consecutive month of growth. A year ago, the index stood at 49.6 pts.
- Services: 51.7 pts (forecast 52.5 pts, previously 52.9 pts).
- New orders: in manufacturing: 53.6 pts (previously 54.4 pts); in services: 50.0 pts (previously 52.3 pts), meaning complete stagnation; composite: 51.1 pts (previously 53.0 pts).
Commentary on the data
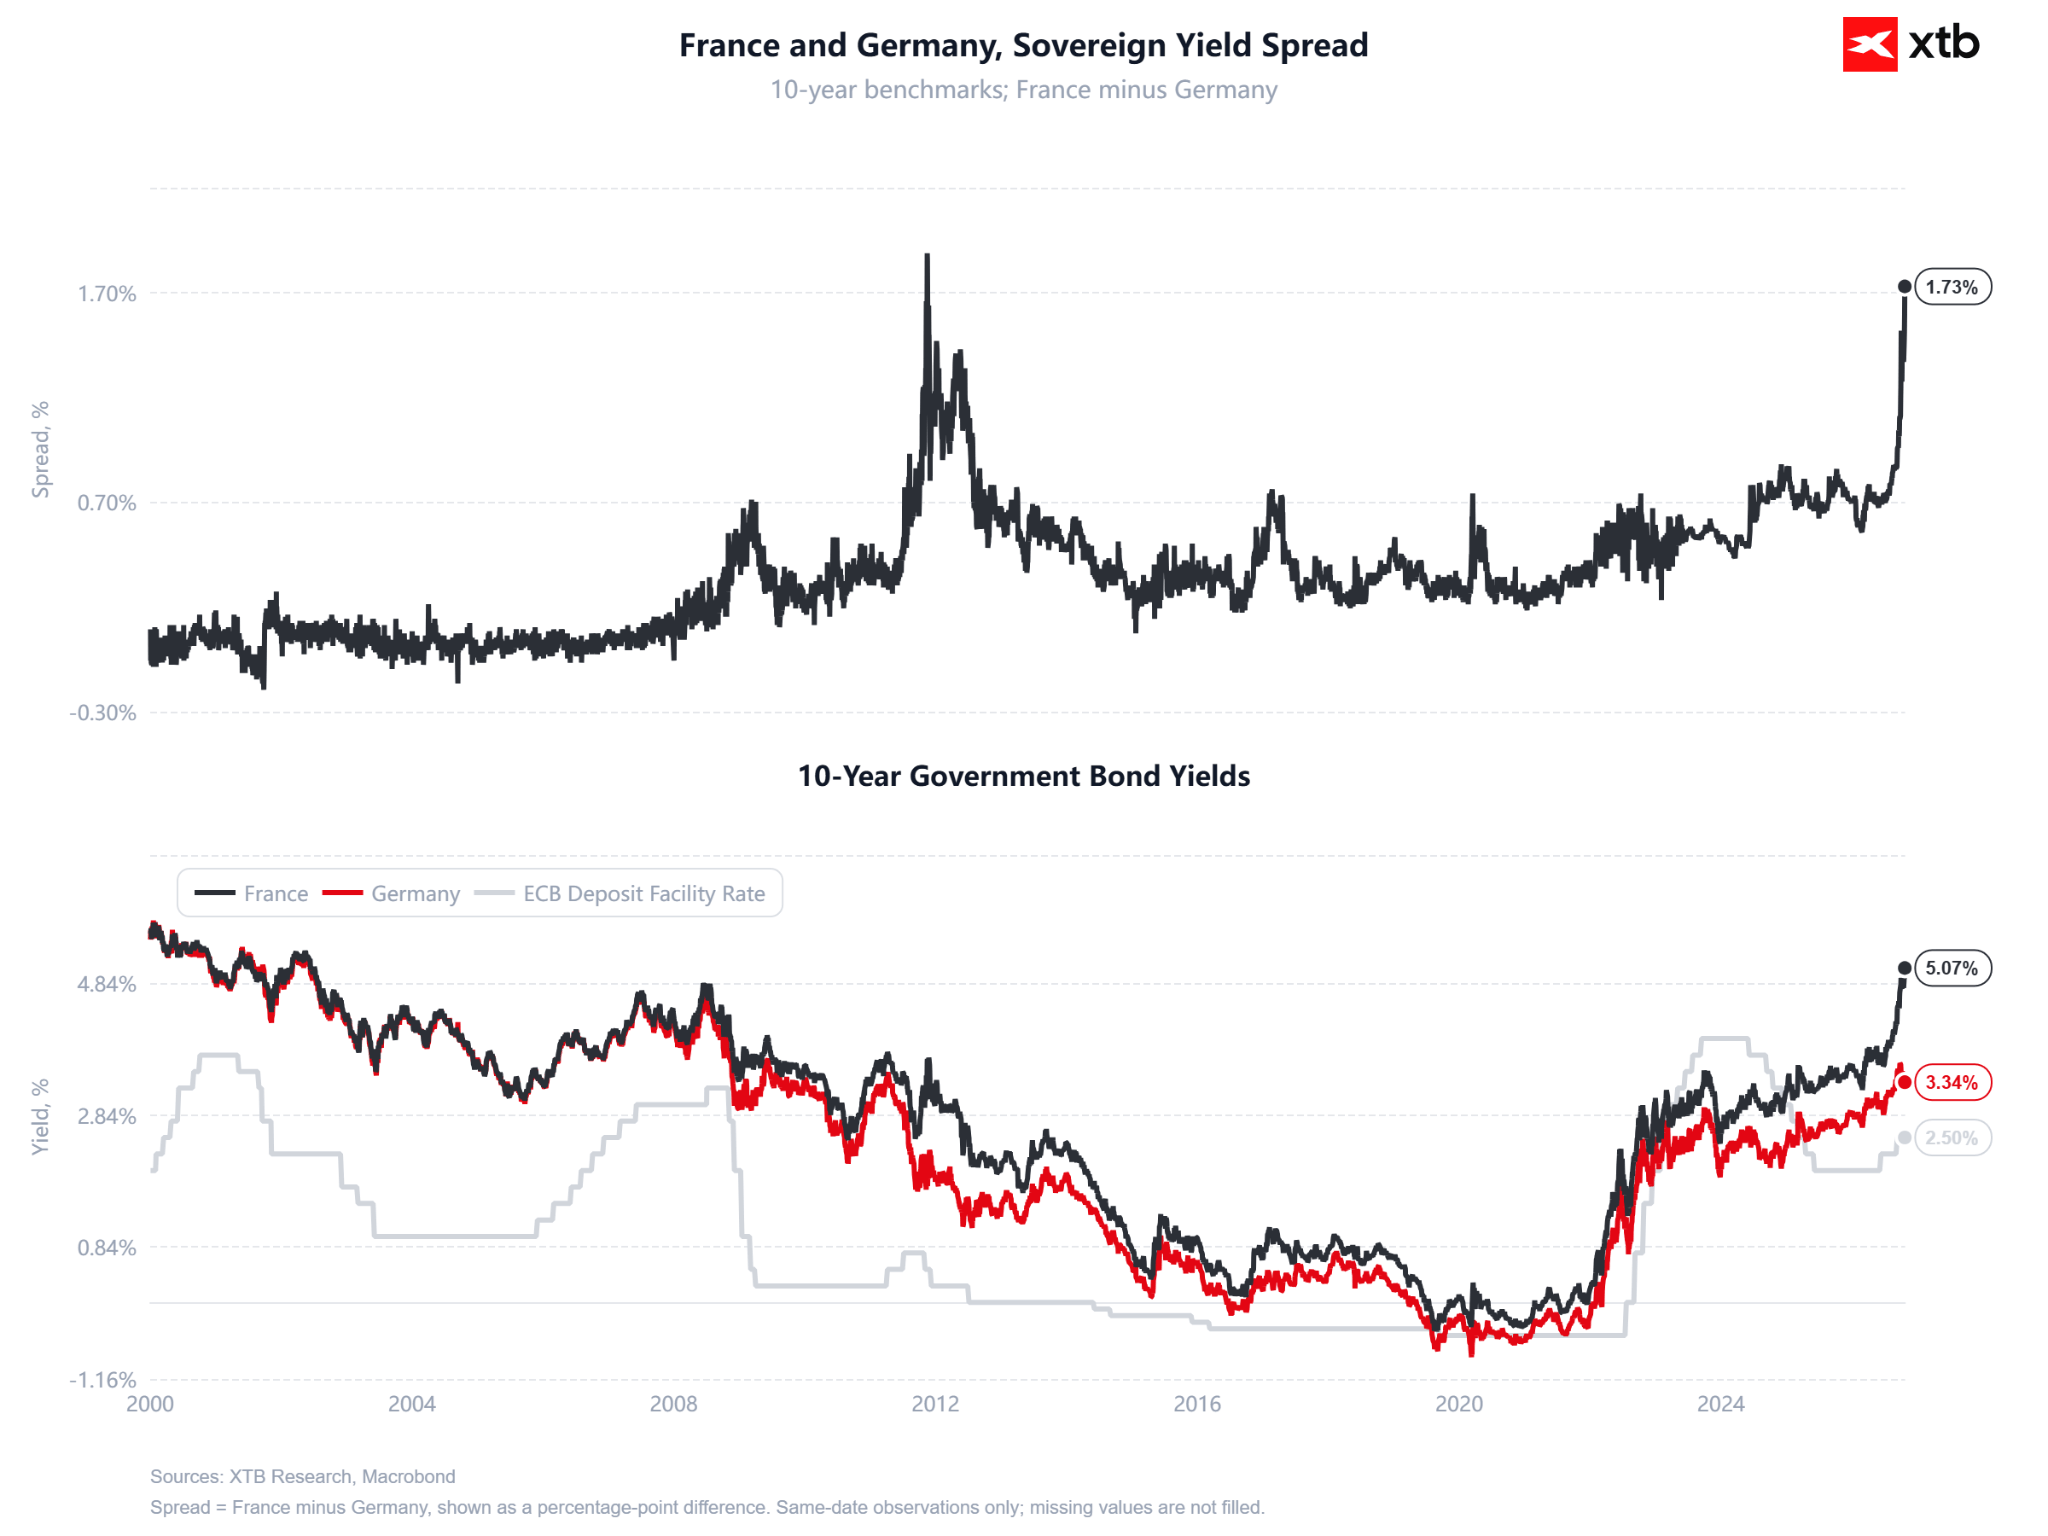
France is paying for the combination of a fiscal and political crisis. The yield on 10-year bonds reached 5% this week, the highest since 2002. The spread to Bunds rose to nearly 175 bps, the highest since 2011. As S&P Global notes, the sharp tightening of financial conditions immediately translated into reduced purchases and corporate investment. Added to this are protests and unrest, the cost of which is estimated at around EUR 1 billion. Most concerning, however, is the drop in business expectations, driven by fears ahead of the 2027 presidential election, where Marine Le Pen is the favorite in the first round. The slump in new orders suggests that October may only be a preview of weaker months ahead. Tonight, Moody's will review France's rating, and under current conditions, a positive surprise is unlikely.
The German economy continues to benefit from public spending on infrastructure and defense, as well as investments in AI. This is visible in manufacturing, which is growing thanks to exports and defense orders. However, services show the other side of the coin: inflation is eroding consumer purchasing power, and new orders in this sector have stalled. According to S&P Global, renewed cost pressure linked to expensive energy following the escalation of the conflict with Iran is dampening sentiment in manufacturing as well. Germany thus remains the anchor of the eurozone, but its recovery is fragile.
For the eurozone as a whole, the picture increasingly resembles stagflation: activity is weakening, while inflation (3.8% in September) and energy prices remain high.
EURUSD: French data tipped the scales
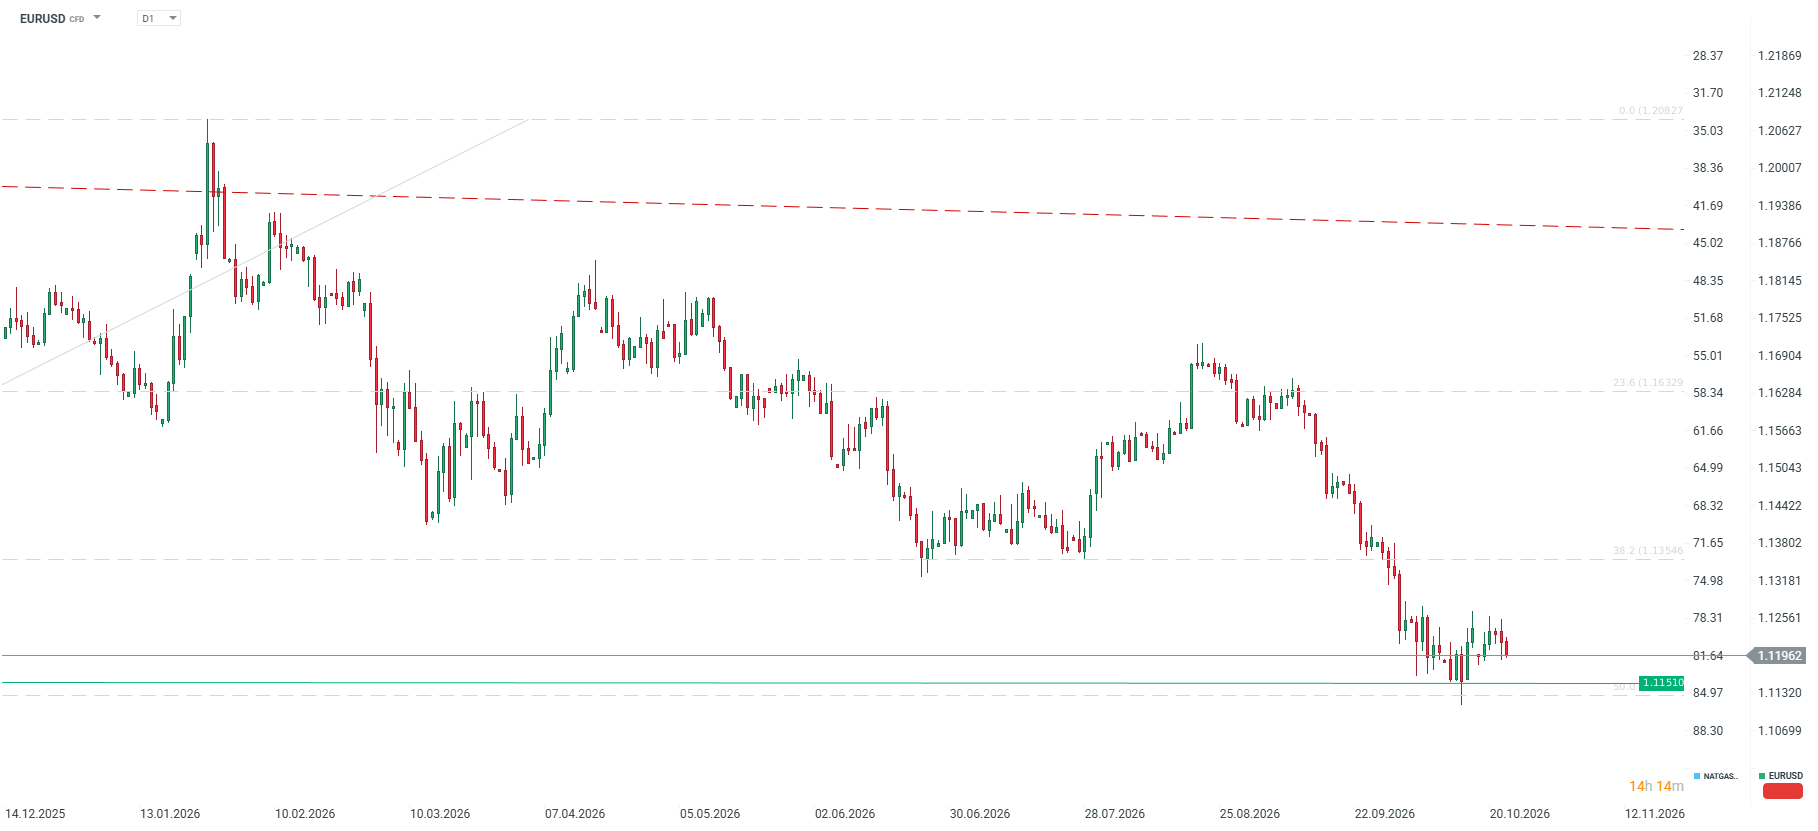
The single currency dropped below 1.12 against the dollar right after the release of French data. As recently as Thursday, EURUSD was around 1.1245, so Thursday's rebound proved to be merely a correction in a downward trend. Several factors are weighing on the euro simultaneously:
- weakening economic momentum,
- record risk premium for France,
- expensive oil, which favors the dollar,
- demand for safe-haven assets following the sell-off in tech stocks.
The nearest support is 1.1151 (low from October 15) near the 50.0 retracement of the long-term upward wave, followed by the 1.1109–1.1111 zone. Resistance now stands at 1.1250. An additional short-term risk is tonight's Moody's decision: a downgrade of France's rating could deepen the euro's decline at the start of the new week.
ECB meeting next week
The ECB meeting is scheduled for October 28–29. The market and economists almost unanimously expect a pause following two rate hikes since the outbreak of the Middle East conflict. Bloomberg Economics expects a final hike in December, to 2.75%. Today's data, however, complicates the picture. Inflation and energy prices argue for further tightening, but contracting activity in France and bond market tensions increase the cost of every subsequent rate hike. Christine Lagarde's messaging will be key. If a clear hint at a December hike is given, the euro could recover some losses. A stronger focus on risks to growth and debt market stability would give EURUSD another argument for further declines.



Daily Summary: Valuations Under Pressure, Capital Moves Away From Technology

Market Wrap: "Decent" results are not enough – tech stocks fall further; oil highest since May (22.10.2026)



Daily Summary: SpaceX and the tech sector drive Wall Street, oil retreats sharply below $97

Russia is selling off gold reserves. Why, to whom, and does it matter for the market?
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.