


The primary catalyst driving the current surge was yesterday's release of US PMI indicators for September. The data significantly exceeded expectations, reaching five-year highs. The composite index reached 58.4, which is consistent with GDP growth dynamics of around 5%. However, the report also highlighted intensifying cost pressures and an increasing tendency among companies to pass higher costs on to customers.
Figure 1: US PMI Indicators (2023 - 2026)
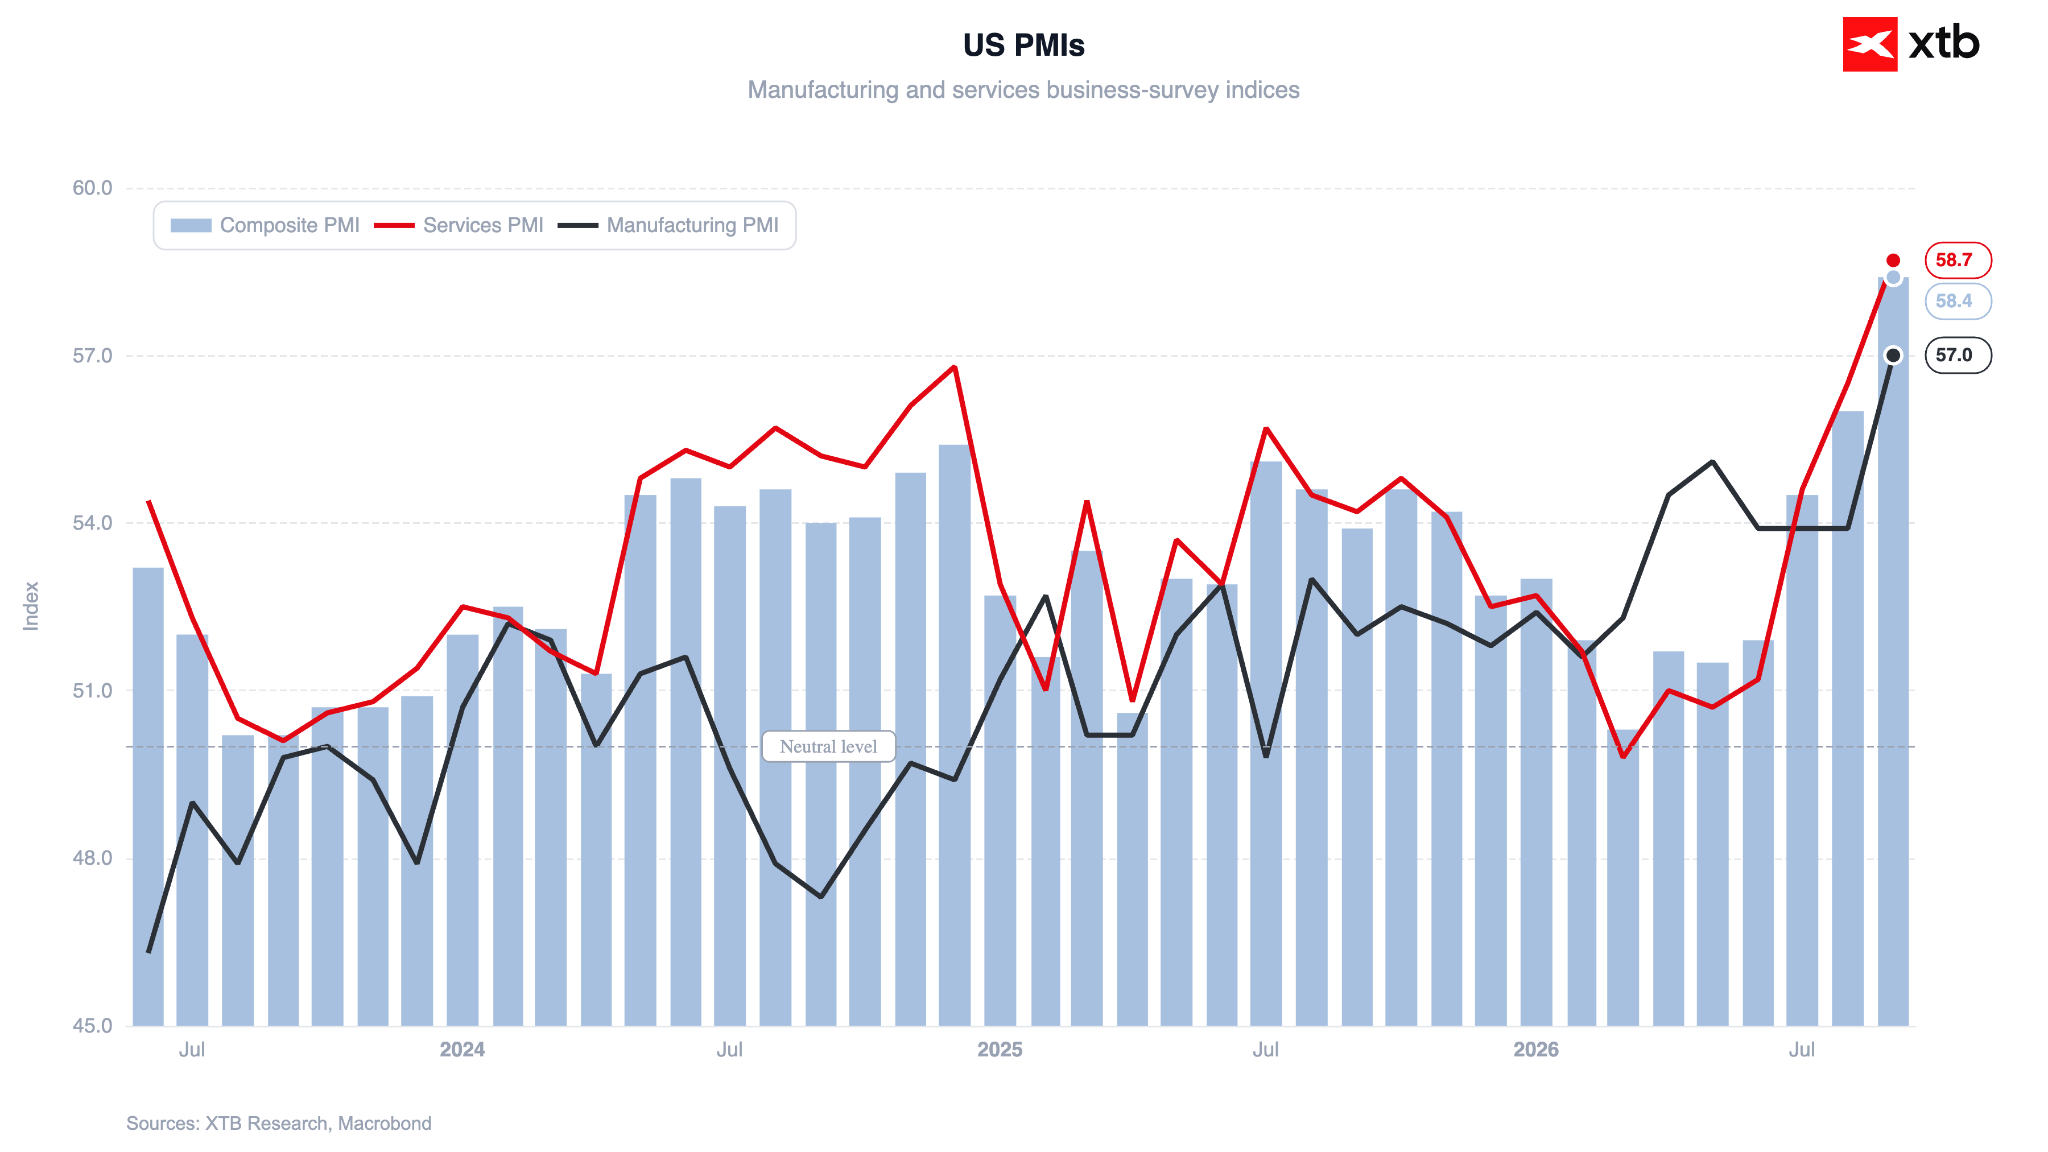 Source: XTB Research, 24.09.2026
This provides a further argument for continued monetary policy tightening by the Fed. Concerns regarding an overheating economy and the necessity of further rate hikes to contain inflation are increasingly coming to the fore.
Market-implied probability of the rate-hiking cycle continuing as early as October has risen above 70%. The repricing was supported by FOMC policymakers Michael Barr and John Williams. The former stated that further policy adjustment was likely, while the latter noted that a rate increase before the end of the year would be reasonable.
Oil remains an important factor in this context. Brent crude continues its upward trajectory today (+1.6%). The movement in WTI is more modest, yet still noteworthy (+1.2%).
The sell-off was further exacerbated by weak demand for debt evident during Wednesday's 5-year bond auction. The Treasury Department's bond buyback programme also disappointed. Long-term bond purchases capped at a maximum of 6 billion dollars were announced for today, whereas the market had anticipated a significantly larger scale.
Impact on Other Assets
A further rise in yields is placing pressure on the equity market, particularly visible in technology stocks. Futures contracts indicate a decline of nearly 1% for the Nasdaq 100 index in pre-market trading. Pressure on the S&P 500 is somewhat lower (-0.5%).
Precious metals are also weakening, as they serve for many investors as a direct alternative to bonds offering increasingly higher returns.
Figure 2: Gold (2026)
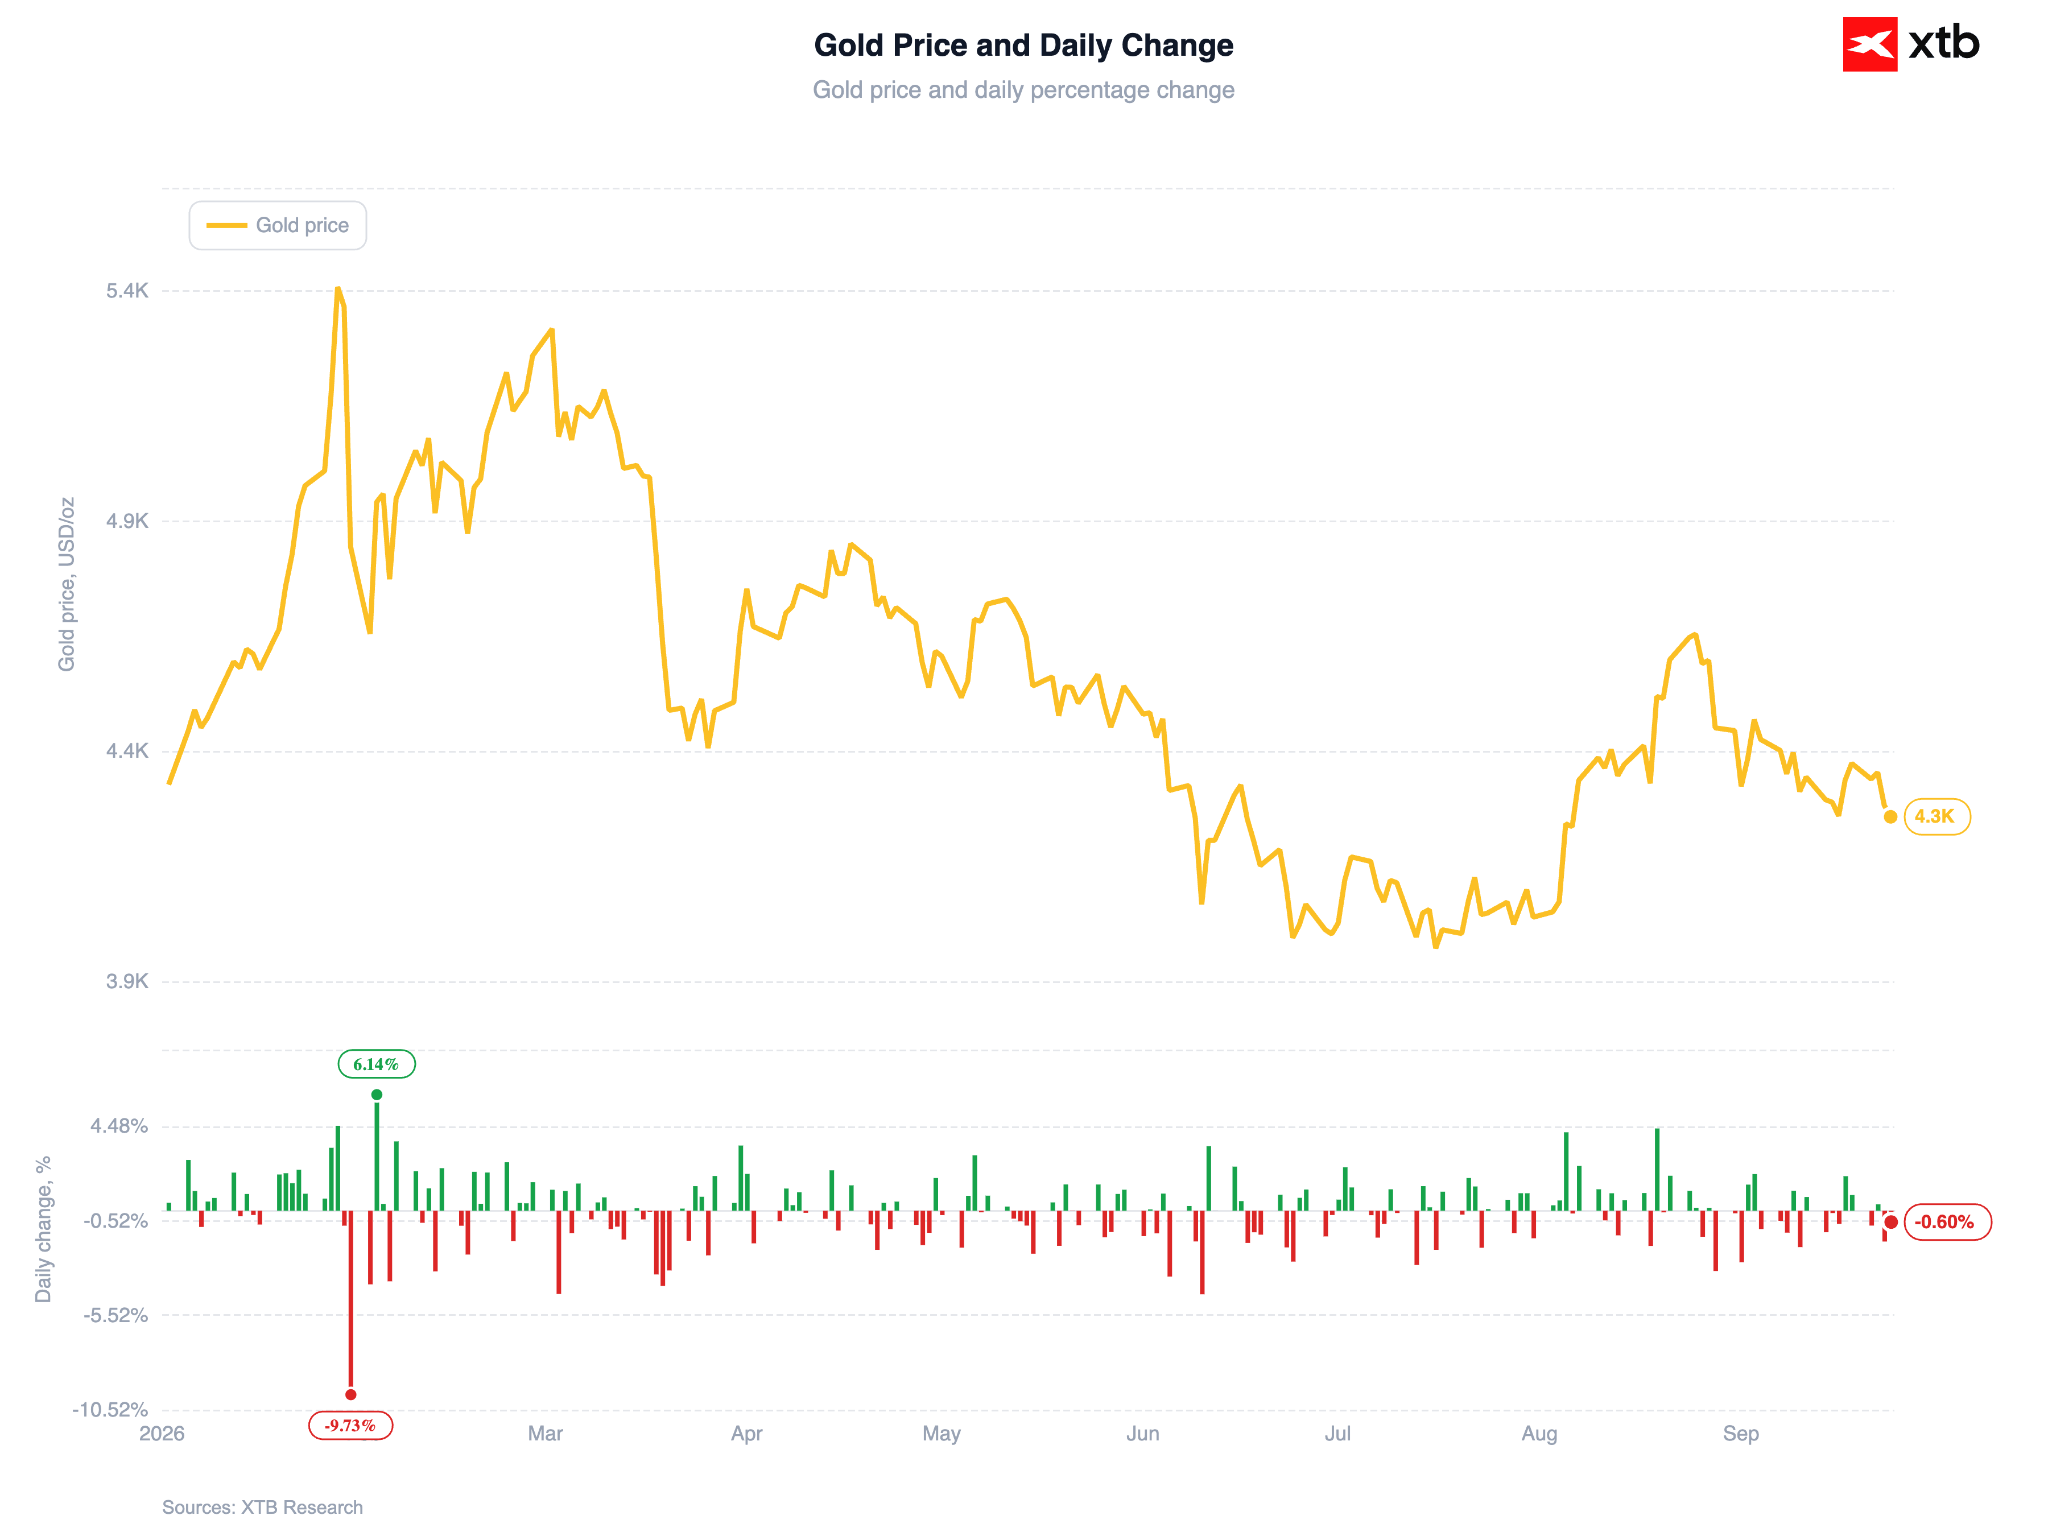 Source: XTB Research, 24.09.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)


US Diesel Export Ban: Is It a problem for Europe?



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)

US Open: Nasdaq drops from the all-time high (23.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.