


Wall Street index futures are gaining between 0.2% and 0.3%, while investors’ attention today will focus primarily on the September US labor market report: NFP, the unemployment rate and wage growth, which could have the strongest impact on expectations for the Fed. In Europe, attention will turn to the preliminary euro area CPI reading, particularly core inflation, as a stronger print could limit the ECB’s room to ease monetary policy.
- Despite the cautious rise in US equities, demand for safe-haven assets continues to dominate global bond markets. Yields are falling in the US, Japan, Australia and New Zealand, while US Treasuries are holding most of Thursday’s price gains. The defensive tone reflects a combination of risks, including tensions in credit markets, elevated commodity prices, persistent inflationary pressure, and political and fiscal uncertainty.
- Yesterday’s rebound in bonds pushed the 10-year Treasury yield back from its highest levels since 2002. Even so, the S&P 500 recovered its initial losses after US manufacturing data showed a sharp increase in raw material costs, keeping inflation concerns alive.
- Europe remains the weaker link. Concerns over France’s fiscal and political outlook continue to support a higher risk premium on French debt, while German bonds remain relatively stable. Asian indices are also down around 0.6%, with China’s Hang Seng standing out negatively after falling nearly 3%.
- Sentiment across equity markets is clearly weaker. Asian indices are heading for their worst week since July, while European equities are on track for their weakest week since April. Pressure is also visible in the UK, where long-dated gilt yields briefly climbed above 6%, highlighting the scale of stress in the bond market.
- The US Dollar Index remains strong and is heading for a third consecutive weekly gain, supported by the relative resilience of the US economy. Brent crude has paused its advance and is trading near $102 after two consecutive positive sessions, while copper is heading for its biggest weekly decline since May.
- For today’s US NFP report at 12:30 PM GMT, consensus expects nonfarm payrolls to rise by around 90,000, while the unemployment rate is seen holding at 4.1%. Geopolitics also remains an important risk factor, particularly amid tensions between Washington and Tehran, which continue to sustain uncertainty around inflation and energy prices.
- Fed Vice Chair Philip Jefferson suggested that policymakers may need more time to assess whether further rate increases are necessary. New York Fed President John Williams made similar remarks earlier, saying there was no urgency to consider another hike following September’s rate increase.
- Donald Trump said that, based on the information he had heard so far, Iran may have been behind the foiled terrorist attack in Israel. The Pentagon is reportedly considering deploying another aircraft carrier and an additional 10,000 troops to the Middle East, while the US is deploying additional Patriot air-defense systems to Saudi Arabia and near Qatari energy facilities, according to Axios.
- Iranian sources cited by Mehr News reported that a supertanker with a capacity of around 2.5 million barrels, which was allegedly transiting the Strait of Hormuz “illegally,” was struck about 8 km off the coast of Oman. The vessel is reportedly on fire, although the reports still require independent confirmation.
- Vladimir Putin said yesterday that Russia is ready for peace talks and wants to conclude them as quickly as possible, but only on terms Moscow considers acceptable to the Russian public. He also said Russia needs security guarantees regarding Ukraine, while referring to Russian territorial gains in September. Ukraine said Russian forces struck one of the bridges today and shelled Kyiv.
- Nike shares (NKE.US) are falling 8% to their lowest level since 2013. The company reported first-quarter EPS of $0.48 versus $0.44 expected, down from $0.49 a year earlier, while revenue came in at $11.21 billion versus the $11.33 billion consensus. Nike brand revenue reached $10.95 billion versus $11.09 billion expected. Gross margin improved to 42.8% from 42.2% a year earlier, but EBIT in China came in at $248 million, well below the $312.2 million estimate, while inventories totaled $7.80 billion versus $7.96 billion expected. The company also expects fiscal 2027 revenue to decline by a high-teens percentage and adjusted EPS to come in at $1.15-$1.35, underlining ongoing pressure on demand and profitability despite the improvement in gross margin.
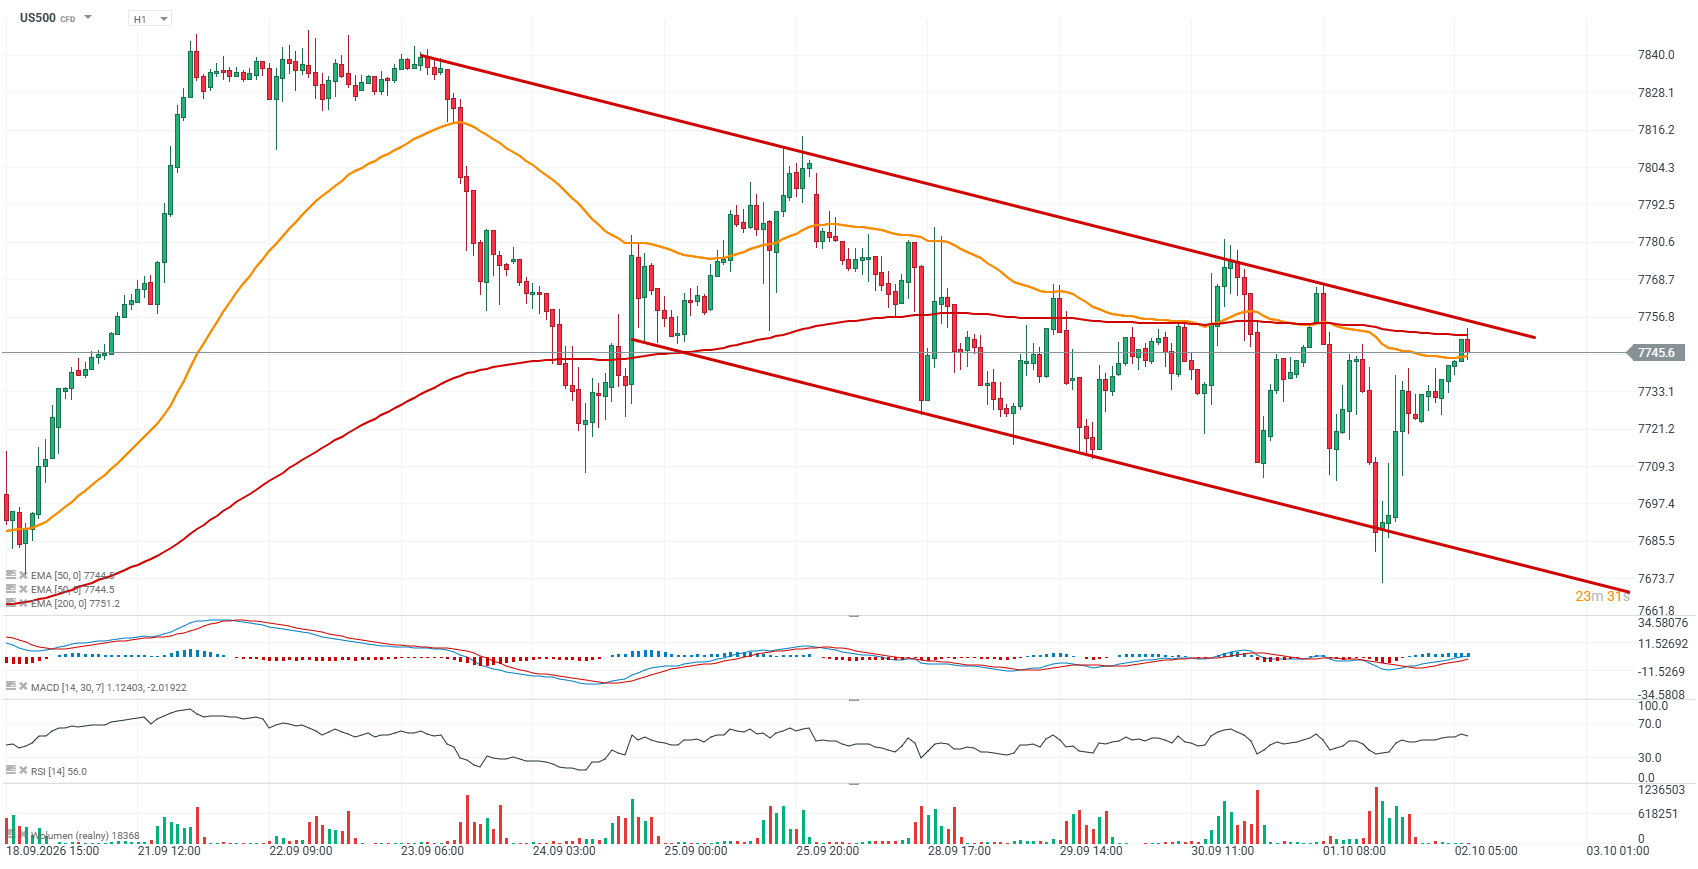
US500 chart (H1 interval)
Since September 23, the S&P 500 futures contract has pulled back and is currently trading near the upper boundary of a descending price channel, where 7,750 points appears to be a key resistance level, while the lower boundary is around 7,670 points. The benchmark is also testing its 200-day exponential moving average (EMA200) on the daily chart, and a breakout above this level would be a key short-term challenge.
 Source: XTB



Market Wrap: A 4% surge in oil prices weighs on indices (08.10.2026)

Chart of the Day 📉 DE40 Falls 0.7% and Tests Key Support Amid Weak European Market Sentiment (October 8, 2026)
Morning wrap: Wall Street and precious metals attempt to stabilize as oil gains nearly 2%

🚩 Caterpillar shares extend decline, down 30% from record high