


S&P 500 futures (US500) are rebounding by more than 1% after several weaker sessions, on a day dominated by the highly anticipated stock market debut of AI giant Anthropic (ANT.US). Tomorrow's scheduled monthly options expiration (OpEx) could also trigger a significant reshuffling of positioning across derivatives markets, particularly options and futures.
-
Leverage among long/short hedge funds has fallen to its lowest level in at least a decade, while the S&P 500's forward P/E ratio has declined to its lowest level since 2023.
-
Market positioning has undergone an extraordinary rotation, with defensive sectors outperforming technology stocks by a margin not seen since 2002.
-
Nasdaq 100 futures are rebounding nearly 1.8% today, outperforming US500, although the technology-heavy index has significantly underperformed the broader S&P 500 over recent months.
-
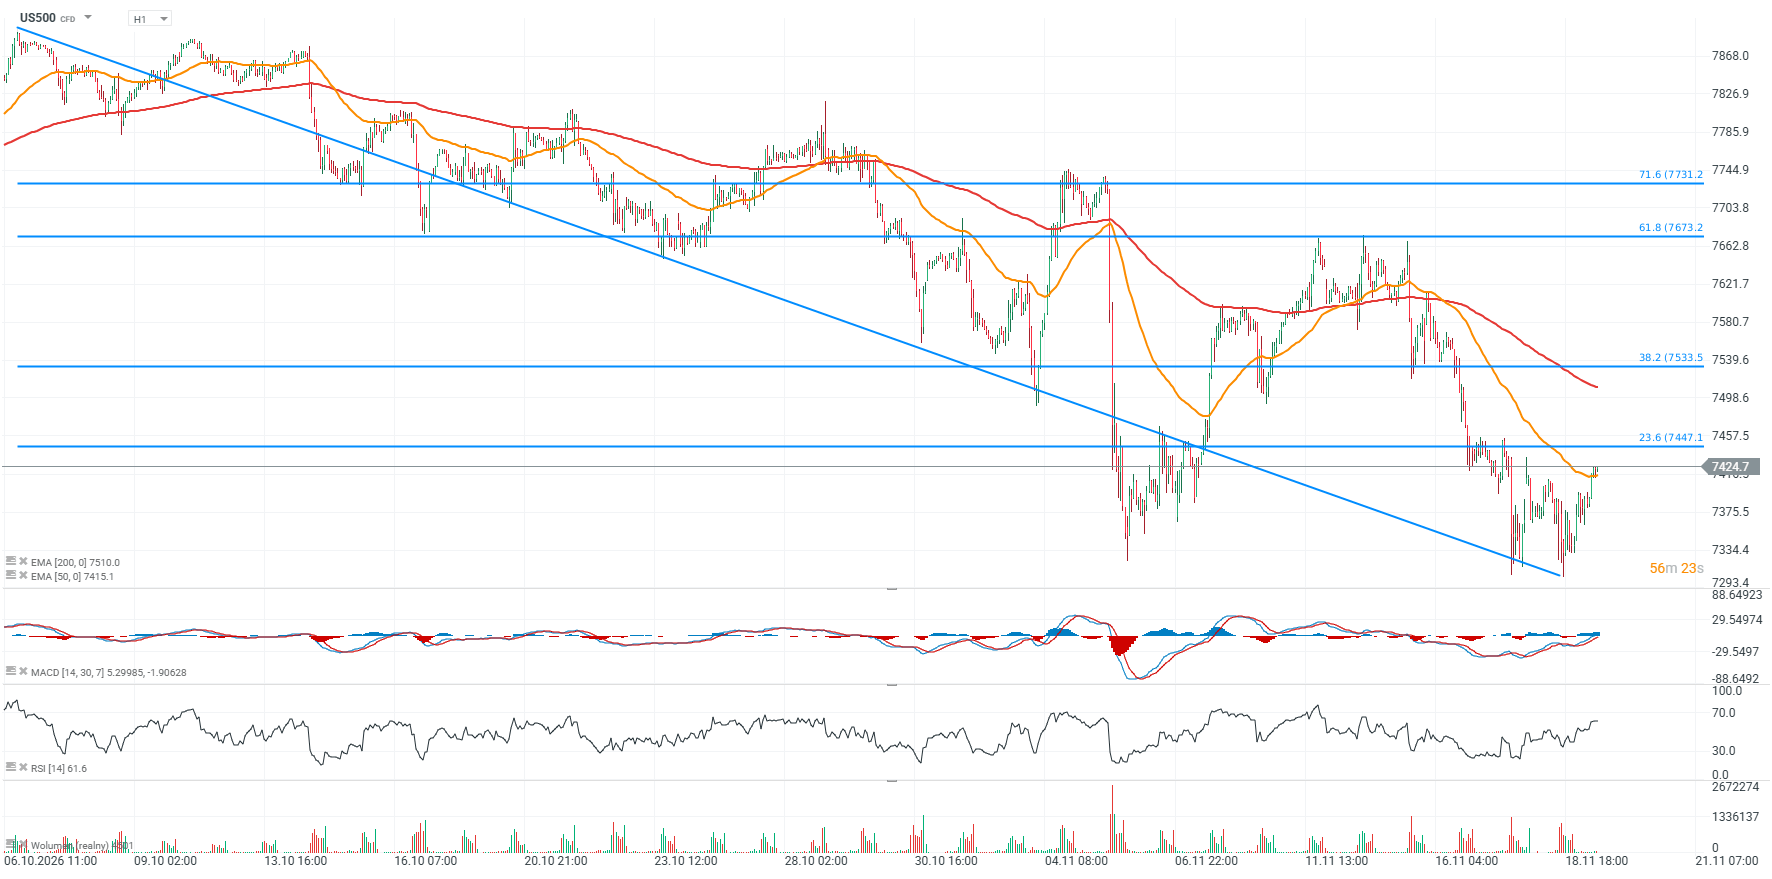
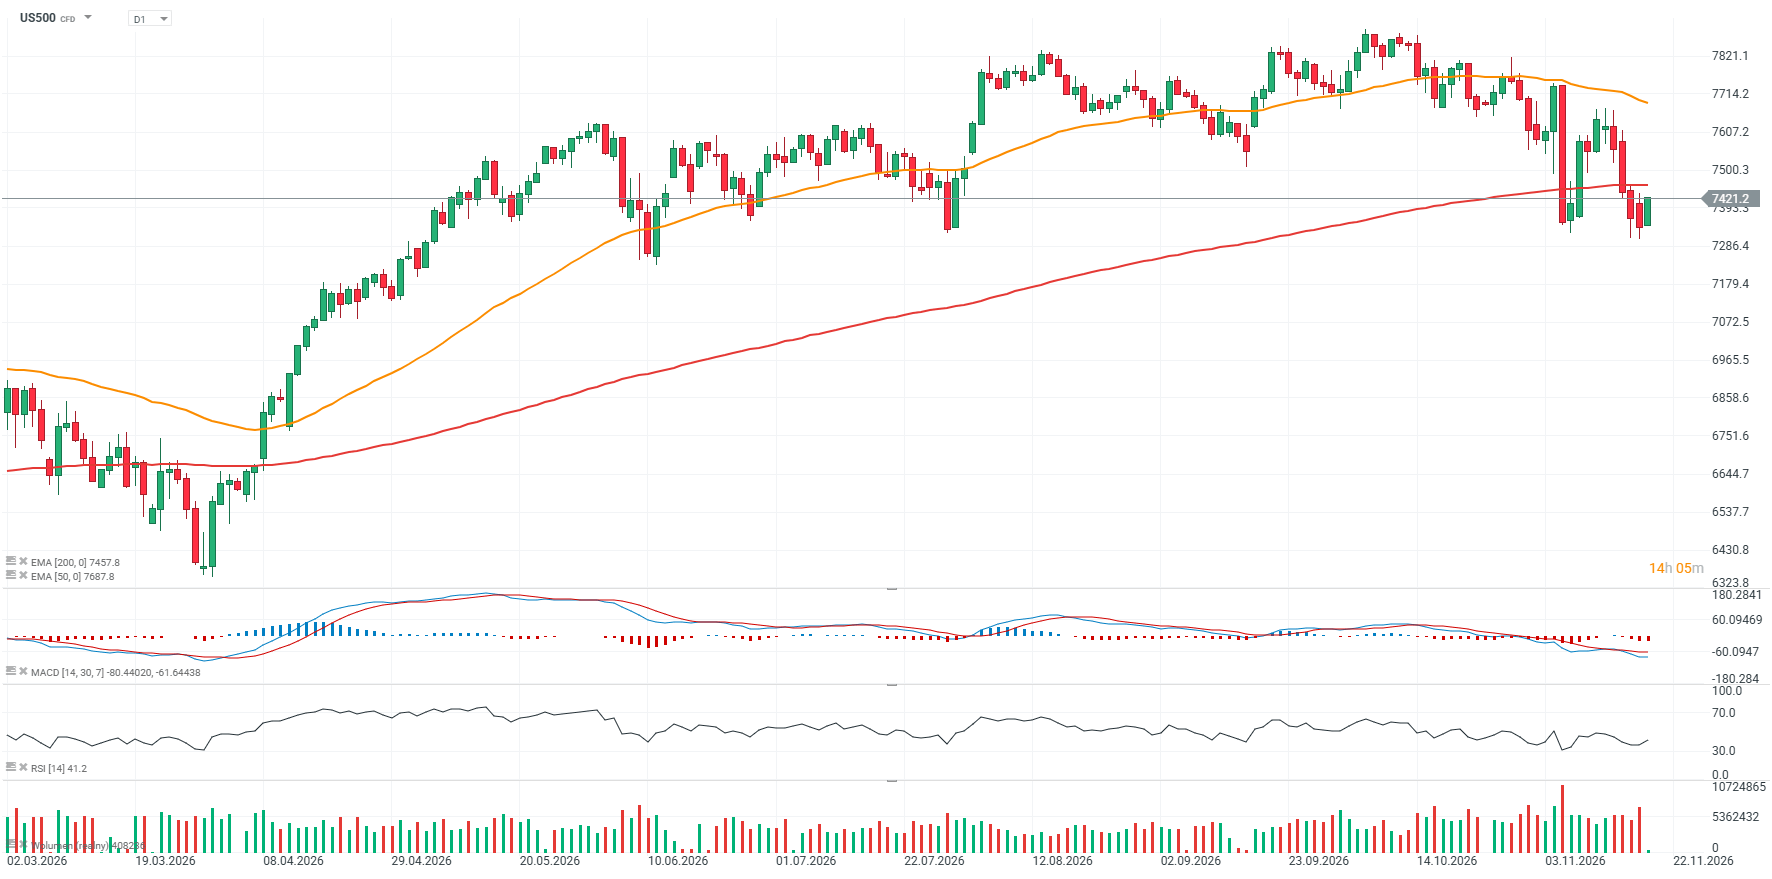
The technical outlook for US500 remains challenging, as the index is trading below its 200-day exponential moving average (EMA200, red line). However, the 7,300-point region has once again provided support.
US500 technical analysis: Could a double bottom be forming near 7,300 points?
S&P 500 futures have recently staged three strong rebounds after approaching the 7,300-point region, confirming this area as an important short-term support zone. If the current rebound continues and develops into a V-shaped recovery, this level could mark the local bottom of the correction. For buyers, the next key challenge will be overcoming the 23.6% and 38.2% Fibonacci retracement levels of the latest downward move, located near 7,450 and 7,530 points, respectively. The most significant resistance lies around 7,670 points, corresponding to the 61.8% Fibonacci retracement and reinforced by recent price reactions.
 Source: XTB
Source: XTB
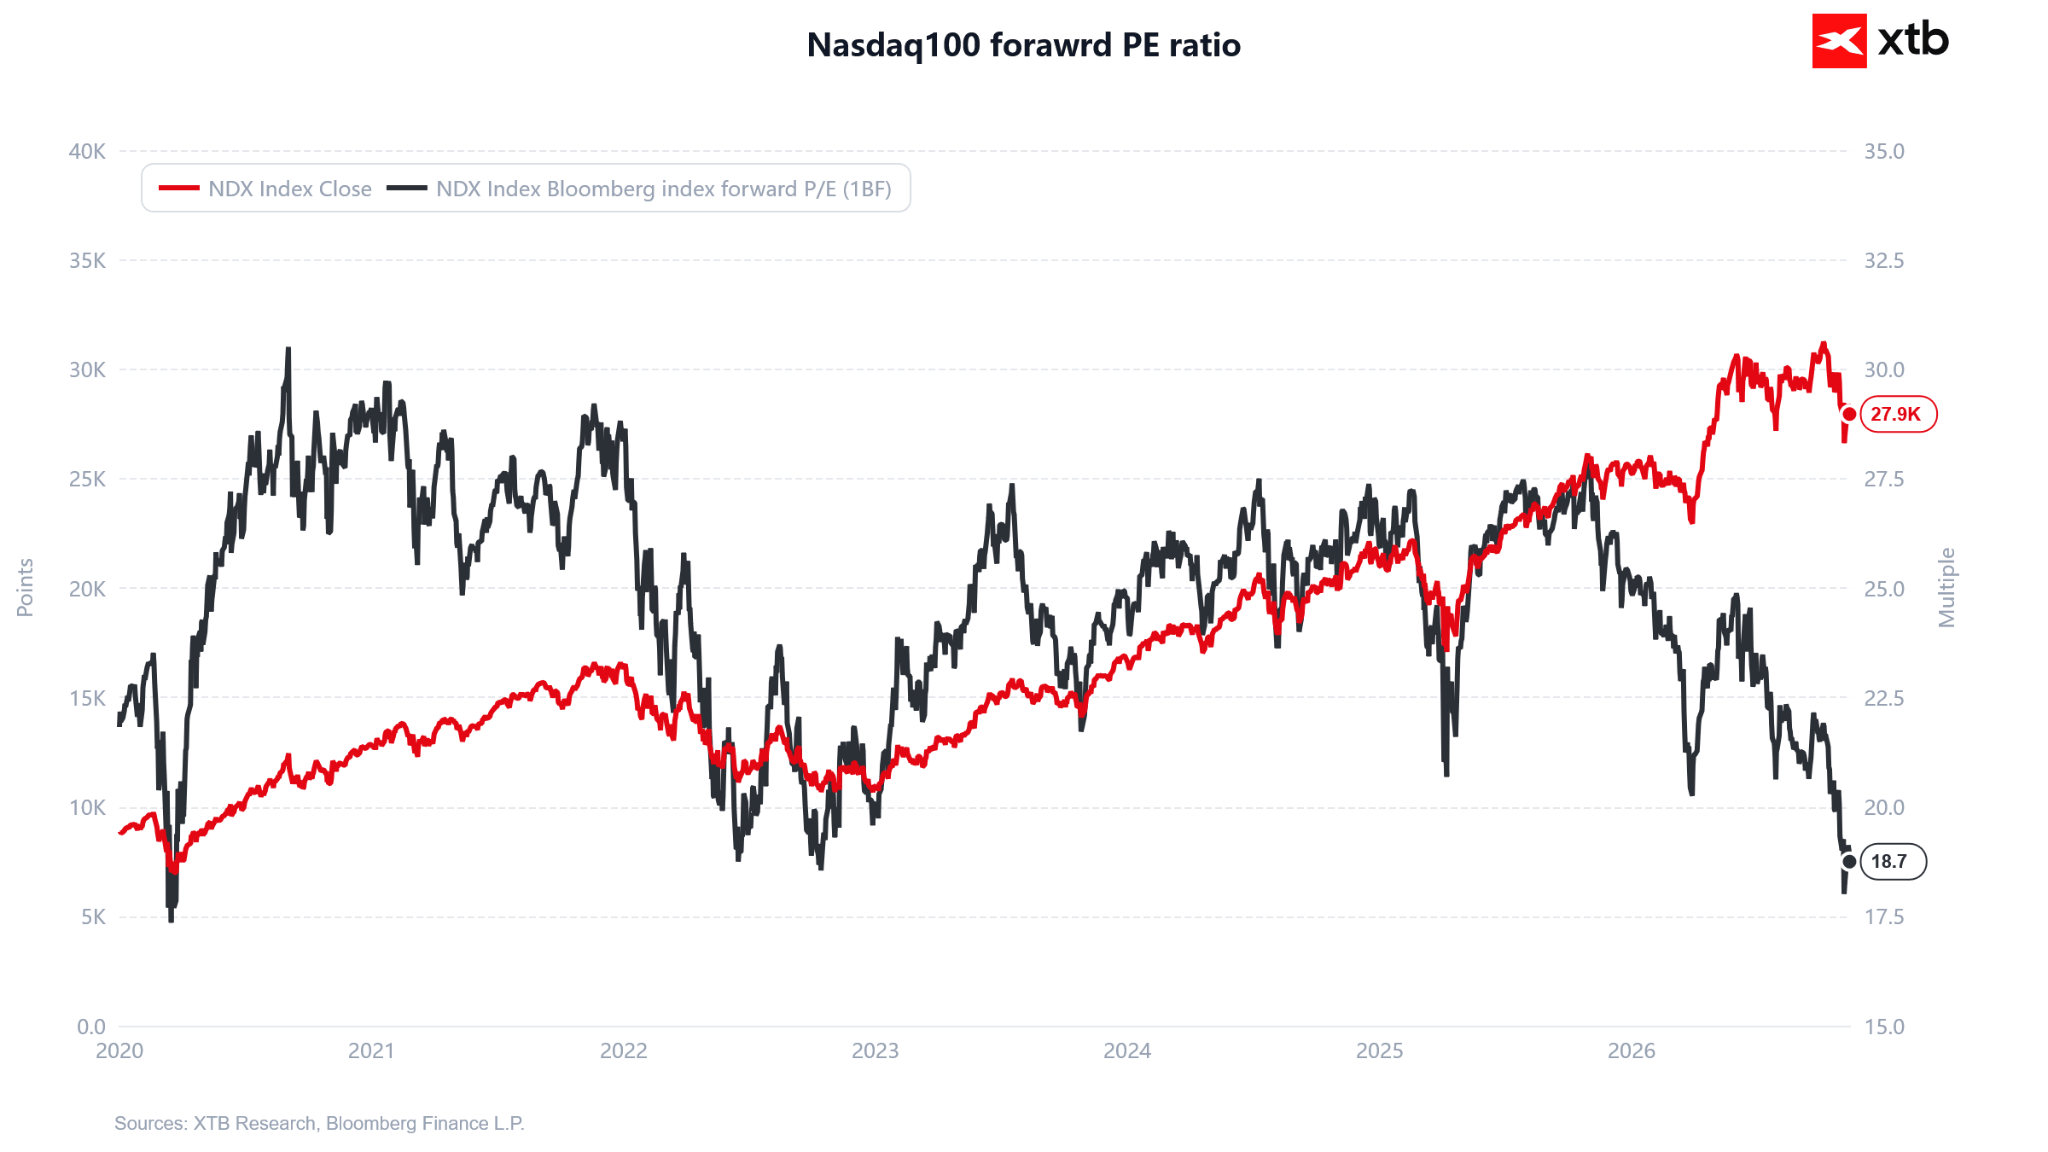
The Nasdaq 100's forward P/E ratio has fallen to 18.7, reaching one of its lowest levels since 2020, even as the index itself remains near 27,900 points. This reflects a substantial compression in US technology stock valuations, with companies now trading at significantly lower multiples of expected earnings than in previous years. Interestingly, the forward P/E ratio periodically exceeded 30 in 2020 and 2021, whereas its current reading is even below the lows recorded during the 2022 bear market. Such a sharp decline in valuation multiples, while the index remains near historically elevated levels, suggests that projected corporate earnings have grown considerably faster than share prices. From a fundamental perspective, the Nasdaq 100 has therefore become relatively cheaper in terms of expected earnings, although this does not automatically imply that the index is undervalued, particularly given elevated bond yields and the risk of downward earnings revisions.
Source: XTB Research
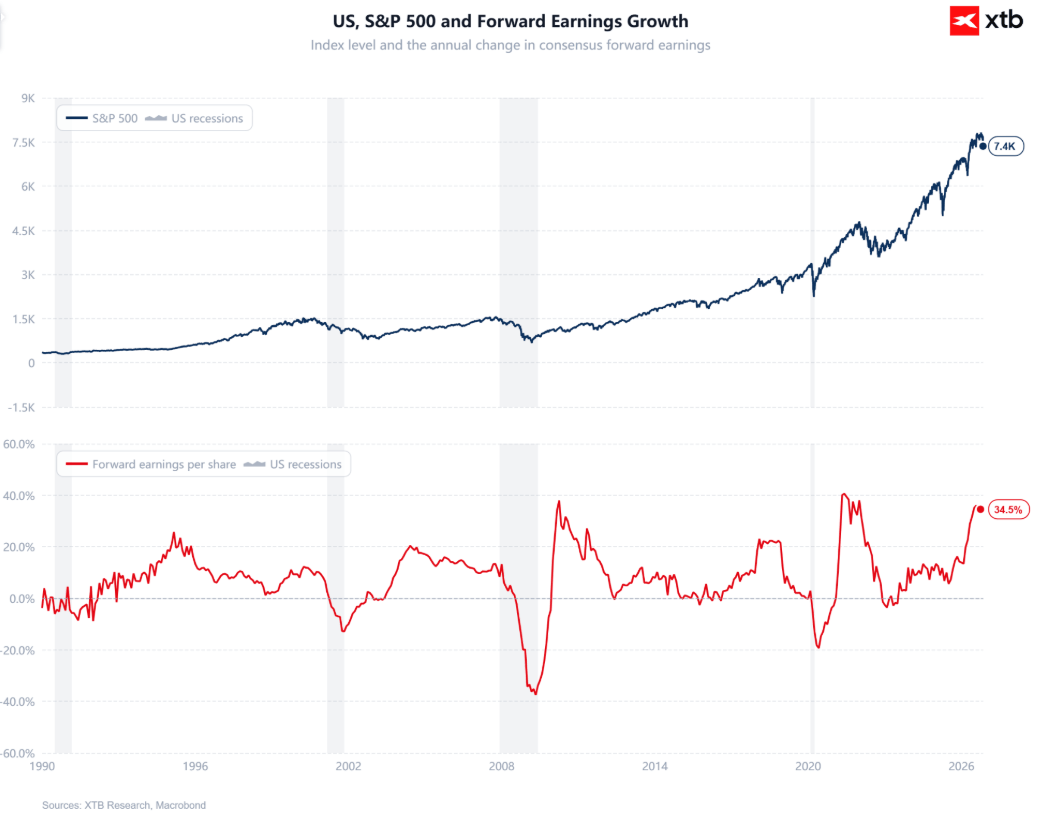
The S&P 500 remains near 7,400 points, while the year-over-year growth rate of consensus forward earnings per share (EPS) has accelerated to 34.5%, reaching one of its highest levels since 1990. Historically, comparable accelerations in expected earnings growth have occurred primarily during economic recoveries following recessions, including in 2009 and 2021. However, the US economy is not currently in recession, making the scale of the improvement in earnings expectations particularly notable from a historical perspective. Such strong earnings momentum may partly explain why US equity valuations have remained elevated despite rising bond yields and the Fed's restrictive monetary policy. At the same time, exceptionally high earnings expectations increase the risk of investor disappointment, particularly if an economic slowdown or weaker-than-expected returns on artificial intelligence investments lead analysts to revise their EPS forecasts downward.
Source: XTB Research

Market Wrap: Anthropic Lifts Sentiment, but a Hawkish Fed Keeps the Dollar High


🔼 US100 surges 2%


The ANT Feelgood Factor



Morning Wrap: Time for the largest stock market debut in history (19.11.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.