


The tech stock rout does not look to be over, and could be broadening as we start a new week. Nvidia’s stock price is lower by another 2% in the pre market, and its rivals, that had benefited from the chip giant’s initial demise, are also playing catch up this morning. AMD’s share price is lower by 4.2% in early trading, even though it eked out a gain last week.
Nvidia dragged deeper into China chip smuggling scandal
Nasdaq and S&P 500 futures are also pointing to declines later today, while European stocks are generally mixed. The headlines over the weekend implicated Nvidia more deeply in a chip smuggling saga that allowed Chinese companies access to its most advanced chips.
The Nvidia scandal continues to be the financial story with the most legs this week. Reports of shareholder pressure to restore Jensen Huang as CEO adds an element of chaos to his resignation last week, and complicates the picture for new CEO Colette Kress ahead of her earnings call on Tuesday. Added to this, US lawmakers are also advancing efforts to tighten export controls to stop sales of advanced AI semiconductor chips from reaching China.
Regulation headway for AI sector hurts entire AI sector
Both Republicans and Democrats are behind enhanced legislation to stop this from happening, and they are planning to give government control to stop sales of chips if there is suspicion they may be going to China. Wide ranging legislation, which is already making headway in Washington, would be a new regime for the AI sector, which has been regulation-light until now. This is why Nvidia’s competitors are falling today, as any legislation is likely to target the entire sector, and not just Nvidia. This could enhance selling pressure on AI stocks in the short term.
Diesel drop brightens outlook for inflation and Treasuries
Markets were tested from multiple angles last week, from tech scandals to the hot CPI print. While the tech scandal continues to develop, there is some better news on the inflation front. US diesel prices fell below $6 per gallon on Monday, to $5.99, which may fuel hope that energy prices could start to moderate and cool US CPI.
US Treasuries have calmed after last week’s rout that saw the 2-year Treasury yield rise by 28bps, and the 10-year Treasury yield close the week at 5.14%. The 30-year mortgage rate in the US is now at 7.5%, which is weighing heavily on the US housing sector. Any sign that inflation is cooling, and that the Fed does not need to hike by as much as expected, could benefit the broader market rebound. Dow Jones futures are mostly flat today, and European indices with low tech exposure are also rising.
Bad news mounting for US indices
A continued sell off in the tech sector may see European stocks outperform their US peers as we move through the rest of this year. Interestingly, US stock markets proved to be remarkably resilient to the turbulence at Nvidia last week. Both the Nasdaq and the S&P 500 notched gains of more than 2% for the week, however, the torrent of bad news including the Microsoft outage and the grounding of all flights in and out of the US at the end of last week, is starting to take its toll.
Investors show signs of nervousness
While equities rose last week, there are other signs that investors are getting more nervous, and this could hit risk sentiment in the coming days. The dollar rose sharply last week, and the dollar index jumped by more than 1% and remains close to 103.50. Fixed income also repriced lower, and yields rose, as mentioned above. While US CPI was the main driver, the impact of surging Treasury yields was global, with other developed sovereign debt markets also selling off.
There is still no deal between the US and Iran, and there were reports of more Iranian attacks on US allies in the region, including Bahrain. This paused the decline in the oil price, which rose 3% last week. At the start of the week, the price of Brent crude is down a notch and it is trading at $95.50 per barrel.
China slowdown intensifies
Earlier on Monday, China reported some weaker than expected economic data. Retail sales growth for October slowed sharply, industrial production was weaker than expected last month, and the investment slump deepened further. The Chinese economy is experiencing a sharp slowdown, and its reliance on foreign demand, and foreign semiconductor chips, leave it exposed to external shocks as we move closer to the end of the year.
Overall, tech is the chief focus on Monday, and the continued slump in AI stocks is dominating markets. Expectations of enhanced political and regulatory pressure for the sector is weighing on all aspects of the AI trade, from Nvidia to Caterpillar, a key player in the data centre construction industry, which is at risk from a slowdown after the US Midterms.
There is also a huge amount of economic data, earnings and mega cap IPOs this week. See below, as we take you through the can’t-miss events in the week ahead.
1, Nvidia results:
There will be strong interest in the Nvidia results. The company is expected to deliver another monster earnings report, but the question is, does it matter for the share price? Also, what happens to the broader AI sector, since Nvidia has been an integral figure linked to the financing of smaller AI companies, especially neocloud businesses?
Investors won’t just want to hear the massive revenue figures for last quarter, but also how the restrictions on their most advanced chips getting to China will impact sales. Analysis by short seller Culper, released earlier this year, found that potentially 20% of Nvidia’s computing revenue was driven by illegal sales to China. Some put the figure as high as 40% of data centre revenue is linked to illegal chip smuggling.
If these sales channels to China are blocked, this could cause massive repercussions for the stock price. For example, the valuation may not look as cheap as it does currently, and the prospect of $1 trillion in revenue for Nvidia’s fiscal year 2028 now looks under threat.
It will be interesting to see if new interim CEO Colette Kress brings this up, or tries to estimate what it means for revenues. If she avoids this topic, instead choosing to wait for the outcome of internal and official US investigations, it could ignite another sell off in the stock price.
Kress has a tough job this week, she will want to put a brave face on the events of recent days, but there are so many complex overhanging questions, that any attempt to provide forward guidance will be immediately challenged by the market.
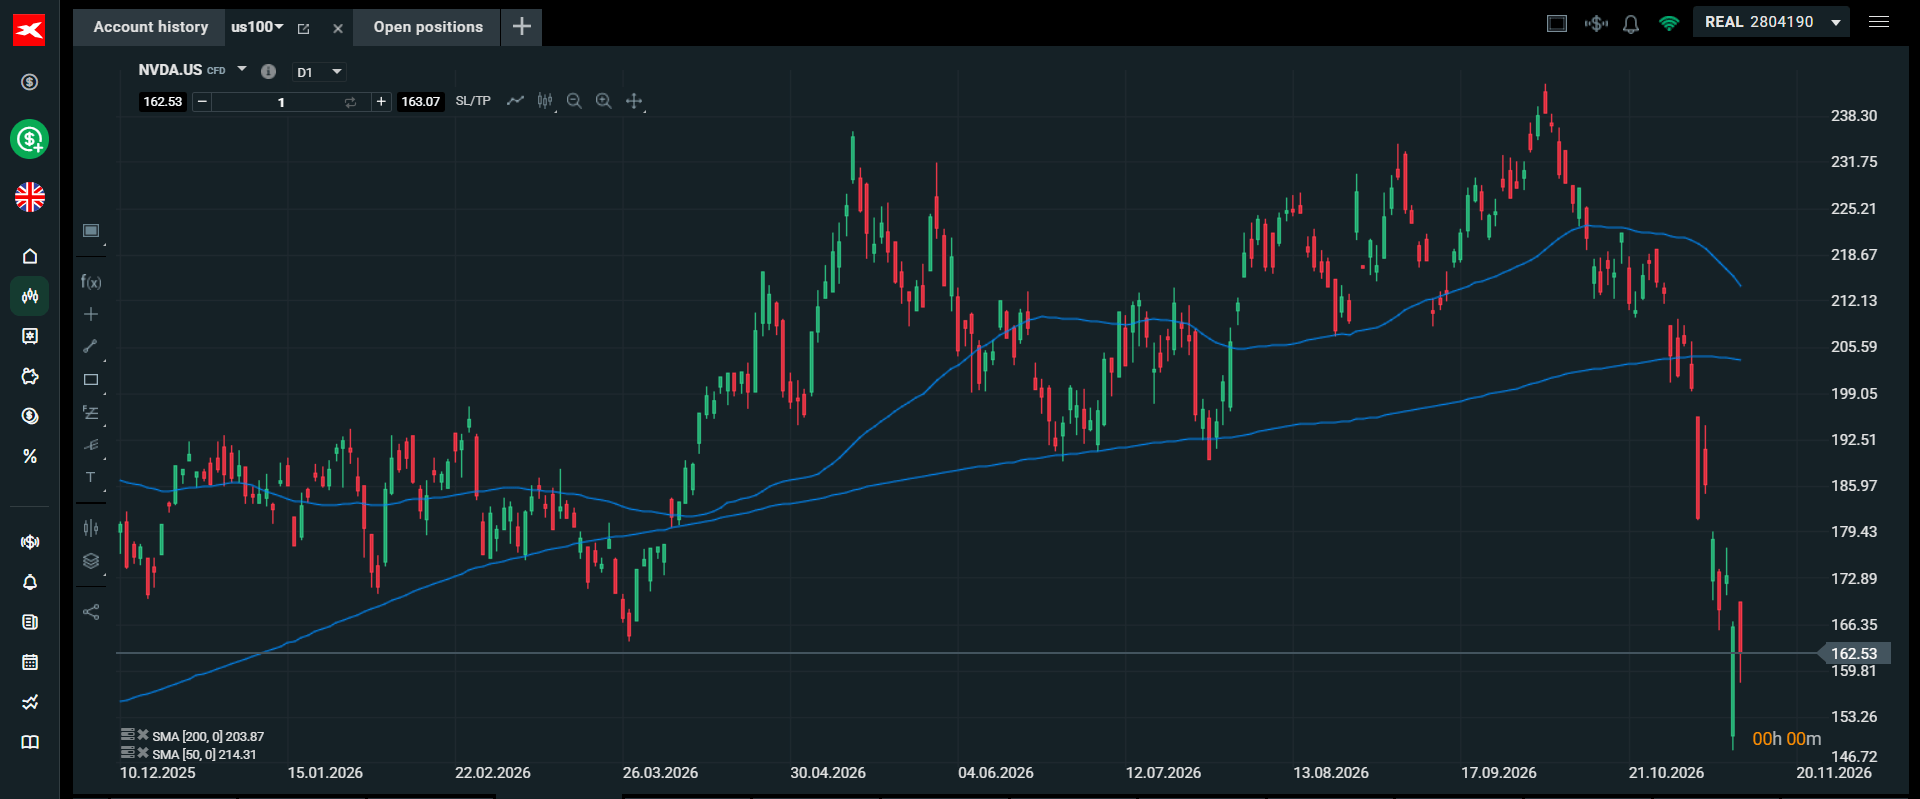
In the short term, the stock price may have climbed back above $160 last week, but it remains vulnerable to another sell off. We will be watching to see if $150 stays as support if the earnings report triggers more downside pressure on the stock.
Chart 1: Nvidia share price, will $150 continue to hold?
Source: XTB
2, Anthropic IPO
This highly-anticipated IPO is launching in the middle of an AI crisis. They are the first of the big AI Labs to list on the market, and the ticker name will be ANT. The stock will price on November 18th, and initial estimates suggest that the price will be between $70 - $78 per share, although reports suggest that the order book is six times oversubscribed, so early trading could see the stock trade at a much higher price than this.
A successful IPO is important for Anthropic, and also for the entire AI sector. Nvidia has been a major financier for the likes of Anthropic and other AI Labs. This financing is likely to come under greater scrutiny now that Jensen Huang has left Nvidia. While other sources of funding will be available, if Anthropic attracts strong investor interest this week then it suggests that the stock market is another option for some of the more mature AI Lab businesses going forward.
3, Economic data
US retail sales and housing data will be watched closely, along with weekly jobless claims, to see if momentum in the labour market remains strong. Consumer confidence on Friday is also worth watching. In the coming weeks, consumer confidence could improve if the decline in diesel costs is sustained.
FOMC minutes will also be dissected by the market. A hike in December is now fully priced in, the bigger debate is whether the Fed hikes by 25bp or 50bps. Investors will be looking for clues to see if a larger hike is likely.
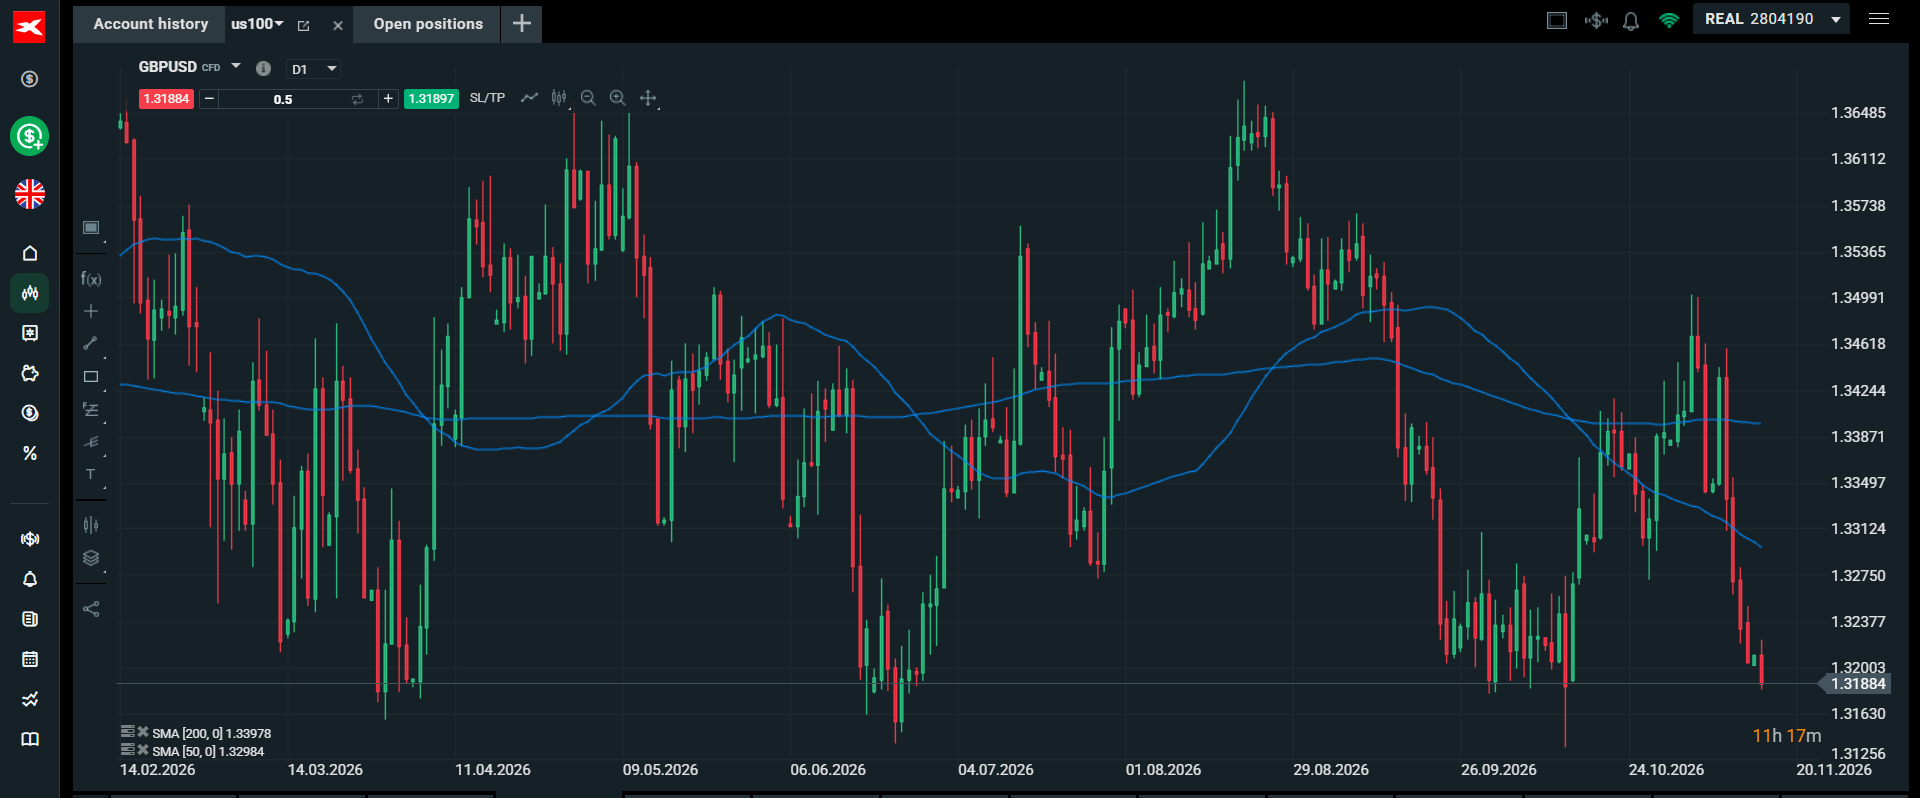
The UK will also see some critical economic data releases this week, including labour market statistics and CPI on Wednesday. Public sector finances are also worth watching. The market is looking for signs of stabilisation in the labour market, while the CPI rate could post a hefty 0.5% monthly increase in headline CPI, driven by energy costs. There is currently a 91% chance of a 25bp rate hike in December, we doubt that the CPI will come in below expectations, so expect further upside for UK Gilt yields this week, which may support the pound.
Chart 2: GBP/USD, the dollar has made a comeback
Source: XTB

Market Wrap: Weak data from Europe and Asia, market awaits Warsh


⚪Chart of the Day: Silver. The market tests yearly lows, while fundamentals worsen.


Morning Wrap: Weak Chinese data and sell-off in Asian chips hit sentiment ahead of Warsh's speech


Daily Summary: PPI Inflation slows down, but EURUSD approaches 1.10
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.