


Financial markets are in a strange position as we move to the final weeks of Q3, uncertainty and volatility continue to grip markets, but the oil price is falling and European and US stocks are poised to open higher later on Monday.
Market stresses are concentrated in sovereign bonds, and European and US yields had another scare late on Friday, and moved higher. This suggests that Wednesday’s rate hike from the Federal Reserve only provided temporary relief.
Watch diesel and petrol to find out what central banks do next
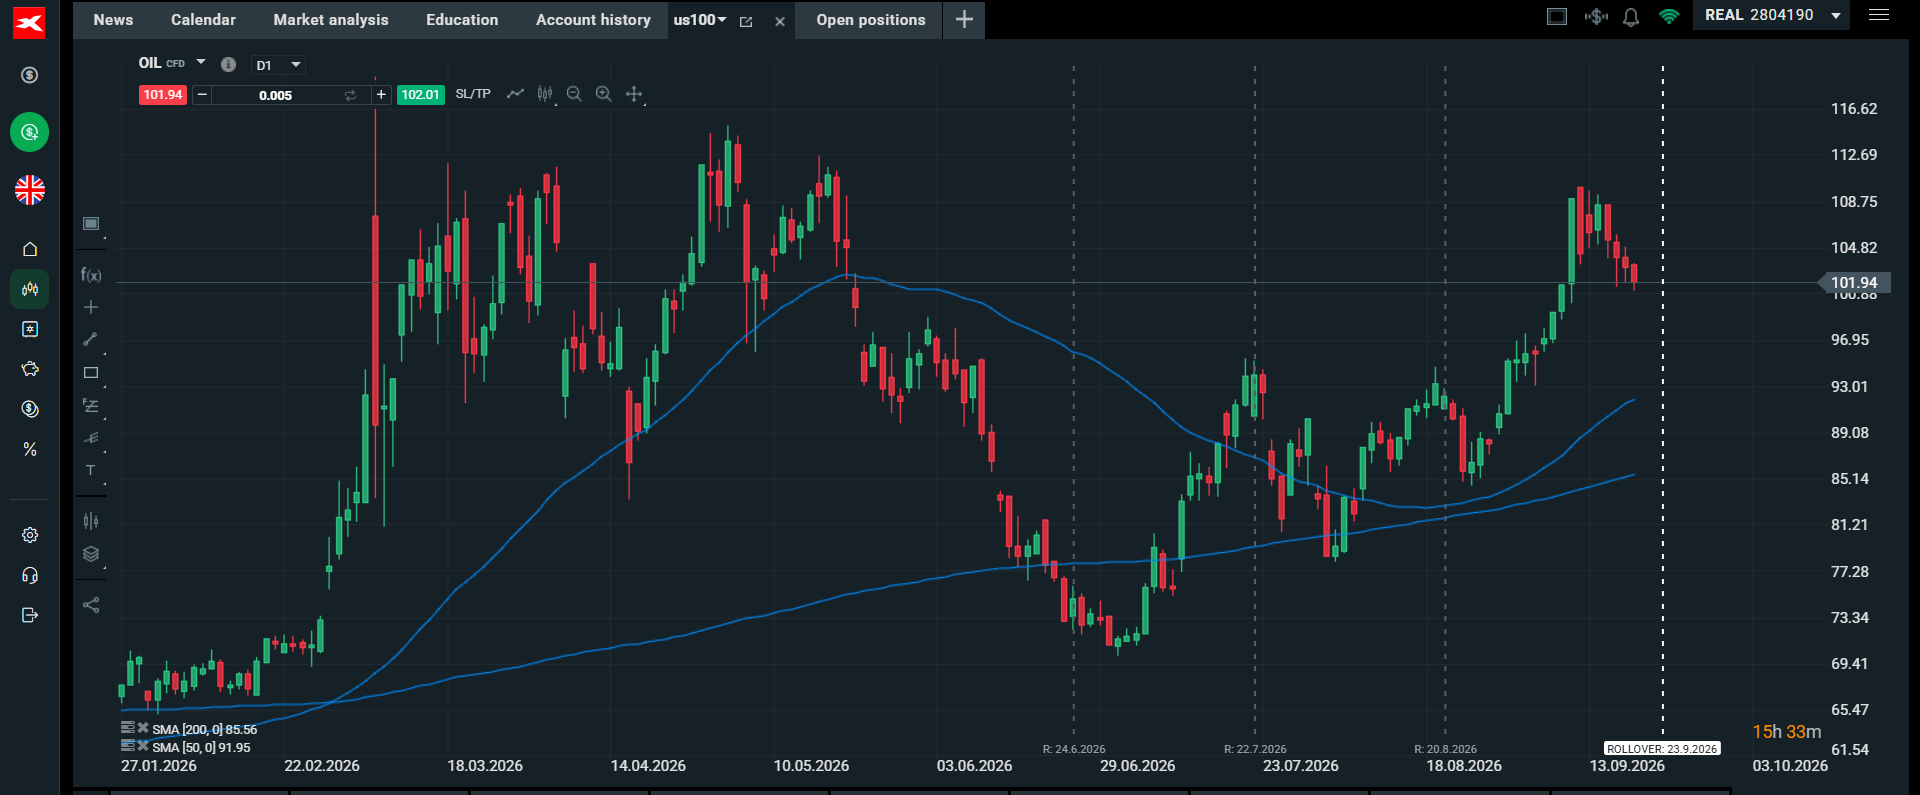
Oil prices are falling at the start of a new week, the Brent crude price is down 1.4%, which is boosting sentiment towards stocks. Brent crude futures prices also fell 3% last week. However, the refined products market is superseding the crude oil price when it comes to the inflation outlook and bond market volatility.
Chart 1: Brent crude oil
Source: XTB
Why the bond market is impacted by fuel prices, not just the oil price
US diesel prices rose to a record last week, and in the UK, unleaded petrol prices at the pump rose to 161.66p per litre, a fresh 4 year high. These prices feed directly into the CPI basket, and the fact that refined products are continuing to rise to multi-year highs changes the calculations for bond investors, who are demanding a higher premium to lend to governments who may have to bail out their citizens with energy support packages.
IMF warns about debt levels
Even the IMF has spoken out about record levels of global debt, saying that governments must do more to narrow budget deficits and rein in debt levels. When the IMF says that fiscal consolidation must take place, surely governments’ should listen? However, if this weekend’s newspapers are anything to go by, then our government is expected to tinker at the edges with more growth-destroying tax rises instead of much-need spending cuts. Due to this, I would expect the political risk premium attached to UK Gilts to grow, and for UK bonds to continue to get sold off, even if the bank of England is willing to slow down, and in some cases stop, its QT programme.
French fiscal woes back in spotlight
Gilt markets suffered another scare on Friday, along with French sovereign debt. French bonds were particularly hard hit, and 2-year and 10-year yields both rose 10bps each. This pushed the 10-year yield to its highest level since 2007. Price action in the bond market in recent weeks suggests that capital is still fleeing bond markets.
Budget risks for Gilts
As we move into the final weeks of Q3, the focus remains on the bond market, and sovereign debt remains vulnerable to further sell offs. This is an acute problem for the UK bond market, as we are just over a month out from the Budget. The Bank of England announced a comprehensive overhaul and slowdown of its QT programme last week, which includes slowing the pace of its balance sheet unwind to £46bn over the next 8 years, down from £70bn, and it also enacted an immediate pause on Gilt sales until April 2027, bringing it inline with other major global central banks.
If long end UK yields start to rise even after this development from the BOE, then it would suggest that quantitative tightening was never the main cause of rising bond yields in the UK. This would leave the Gilt market, and the chancellor, in a very precarious position.
Why are equities so resilient?
In the long term, if there is less capital directed to sovereign bonds, this should be good news for equities and physical assets like commodities. However, there has been a flurry of traditionally bad news for equities in recent weeks including higher inflation, higher interest rates and the Fed being willing to keep interest rates higher for longer. However, the AI trade remains robust and earnings growth is ensuring that stocks are propped up for now.
Russian risks
For obvious reasons, the bond market is likely to remain in focus this week, as commodity prices remain elevated. Over the weekend, two developments could ensure that refined product prices remain elevated. News that Saudi Arabia is halting more oil exports to Europe after attacks on its oil infrastructure, adds to supply concerns, while Ukraine fired its largest ever drone attack on Moscow over the weekend, targeting the city’s main oil refinery.
This news comes after half of Russia’s 6 largest diesel-producing refineries have cut or completely halted output in September because of a spate of Ukrainian drone attacks. This highlights how geopolitical risks are stacking up for energy prices and the global economy. This has already knocked sentiment in the sovereign bond markets, but equities have so far been resilient to the threats facing the real economy.
Asian and US stock indices were the top performers last week, and the Vix index, which measures S&P 500 volatility fell. European stocks were laggards, but losses were fairly mild. Technology and healthcare did the heavy lifting for the S&P 500 last week, and the AI trade ended the week higher. The Philadelphia Semiconductor index rose 1.5%, defying fears from AI executives about a need for a deceleration in AI development.
This week we get some timely economic indicators as well as a resumption of Fed speakers. This will be important to gauge how far and fast this rate-hiking cycle will go, which could have big ramifications across financial markets, but most intensely in the bond market.
1, UK public sector finances
Public sector finance data arrives on Tuesday at a time of intense volatility for the UK Gilt market. Concerns are growing about the rate of UK government borrowing, and the lack of effort to rein in spending. The IMF is speaking out about this on a global scale, but the UK is at the forefront of concerns about highly indebted nations.
The August public finance data is expected to show that borrowing rose by £15.7bn in one month. The context to this report was weaker July data, with borrowing running above OBR projections. Net debt now stands at 94.1% of GDP, and the figure is set to get bigger with another bumper borrowing month.
August 2025 saw higher than expected borrowing of £18bn, due to rising benefit costs. The benefits bill has not got any smaller under this Labour government, so the risks are balanced towards a larger than expected borrowing/ deficit figure.
2, Global PMIs
These will be scrutinised to see how resilient underlying economies are as we move through the second half of this year. The Atlanta Fed’s GDPNow estimate of US GDP for Q3 is 5.1%, which is a remarkable figure considering the challenging backdrop of rising energy costs.
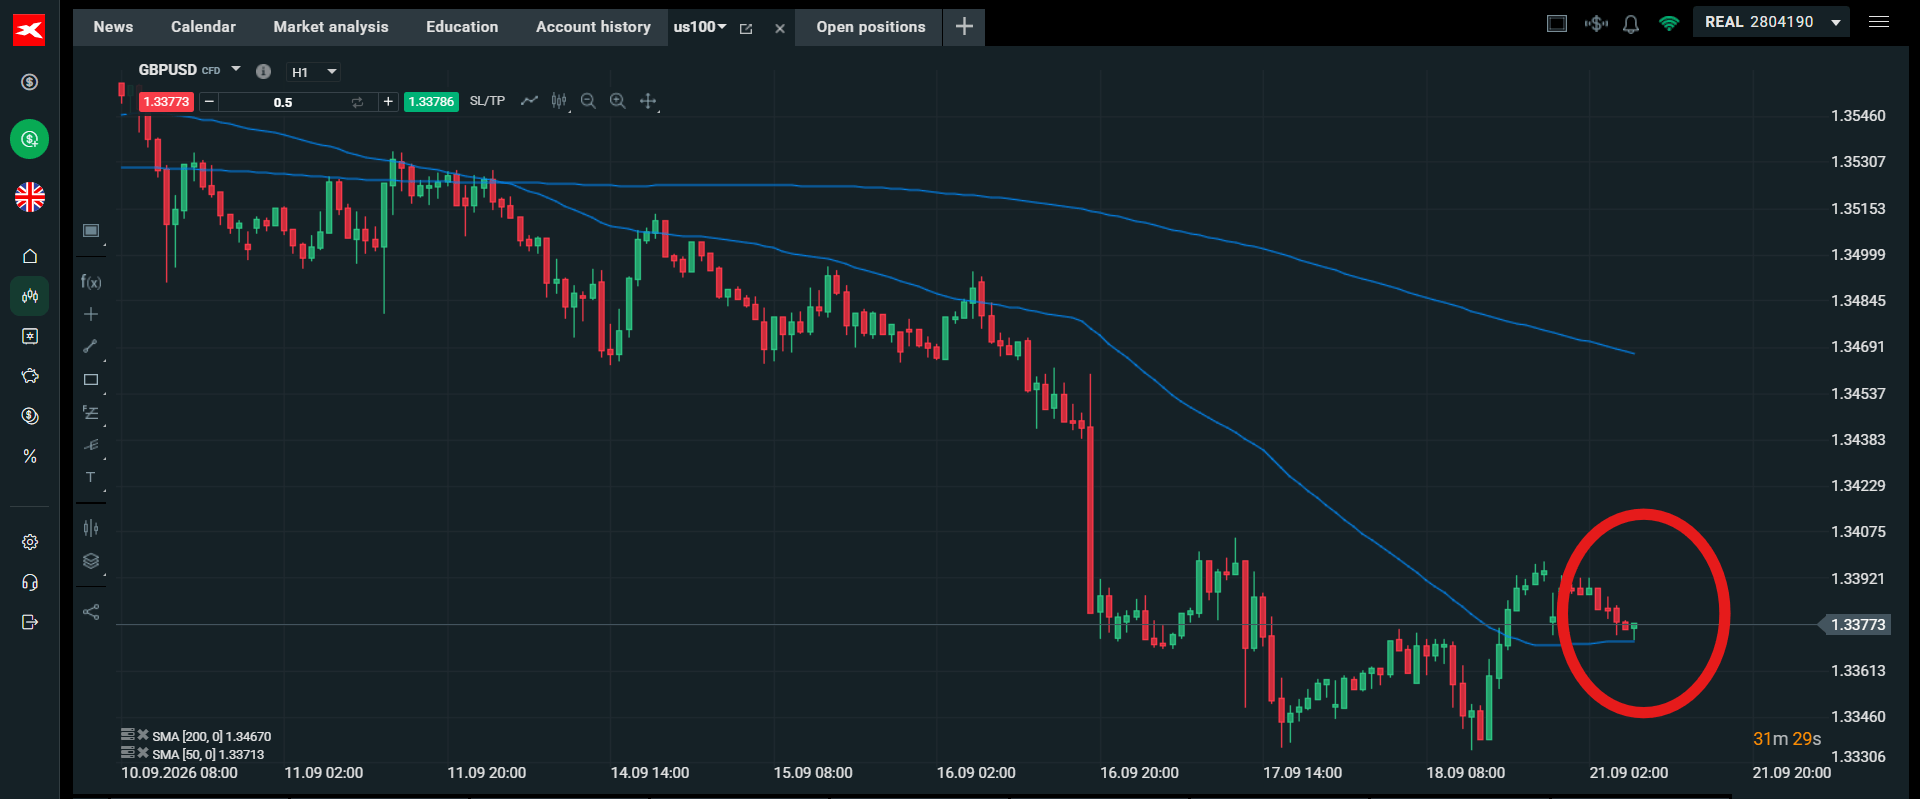
The UK economy is not growing at the same rate as the US, but it is also showing a level of resilience many did not expect, along with an upgrade to productivity. Can the PMI data show that this resilience has continued for the UK? If yes, then GBP could recover, and GBP/USD may climb back above $1.34, after suffering a brutal 0.88% drop last week.
Chart 2: GBP/USD finds a ST bottom at $1.3330
Source: XTB

Economic Calendar: Day of central banker speeches led by Lagarde (21.09.2026)

Morning briefing: Trump-Xi in the shadow of geopolitical tensions (21.09.2026)


Daily Summary: Bitcoin Excites Investors Despite the Fed's Hawkish Shift🏛️


What could halt the uptrend❓
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.