


Today, all eyes of investors are on a single event: the evening's FOMC decision. The market is pricing in a more than 90% chance of the first US interest rate hike since 2023.
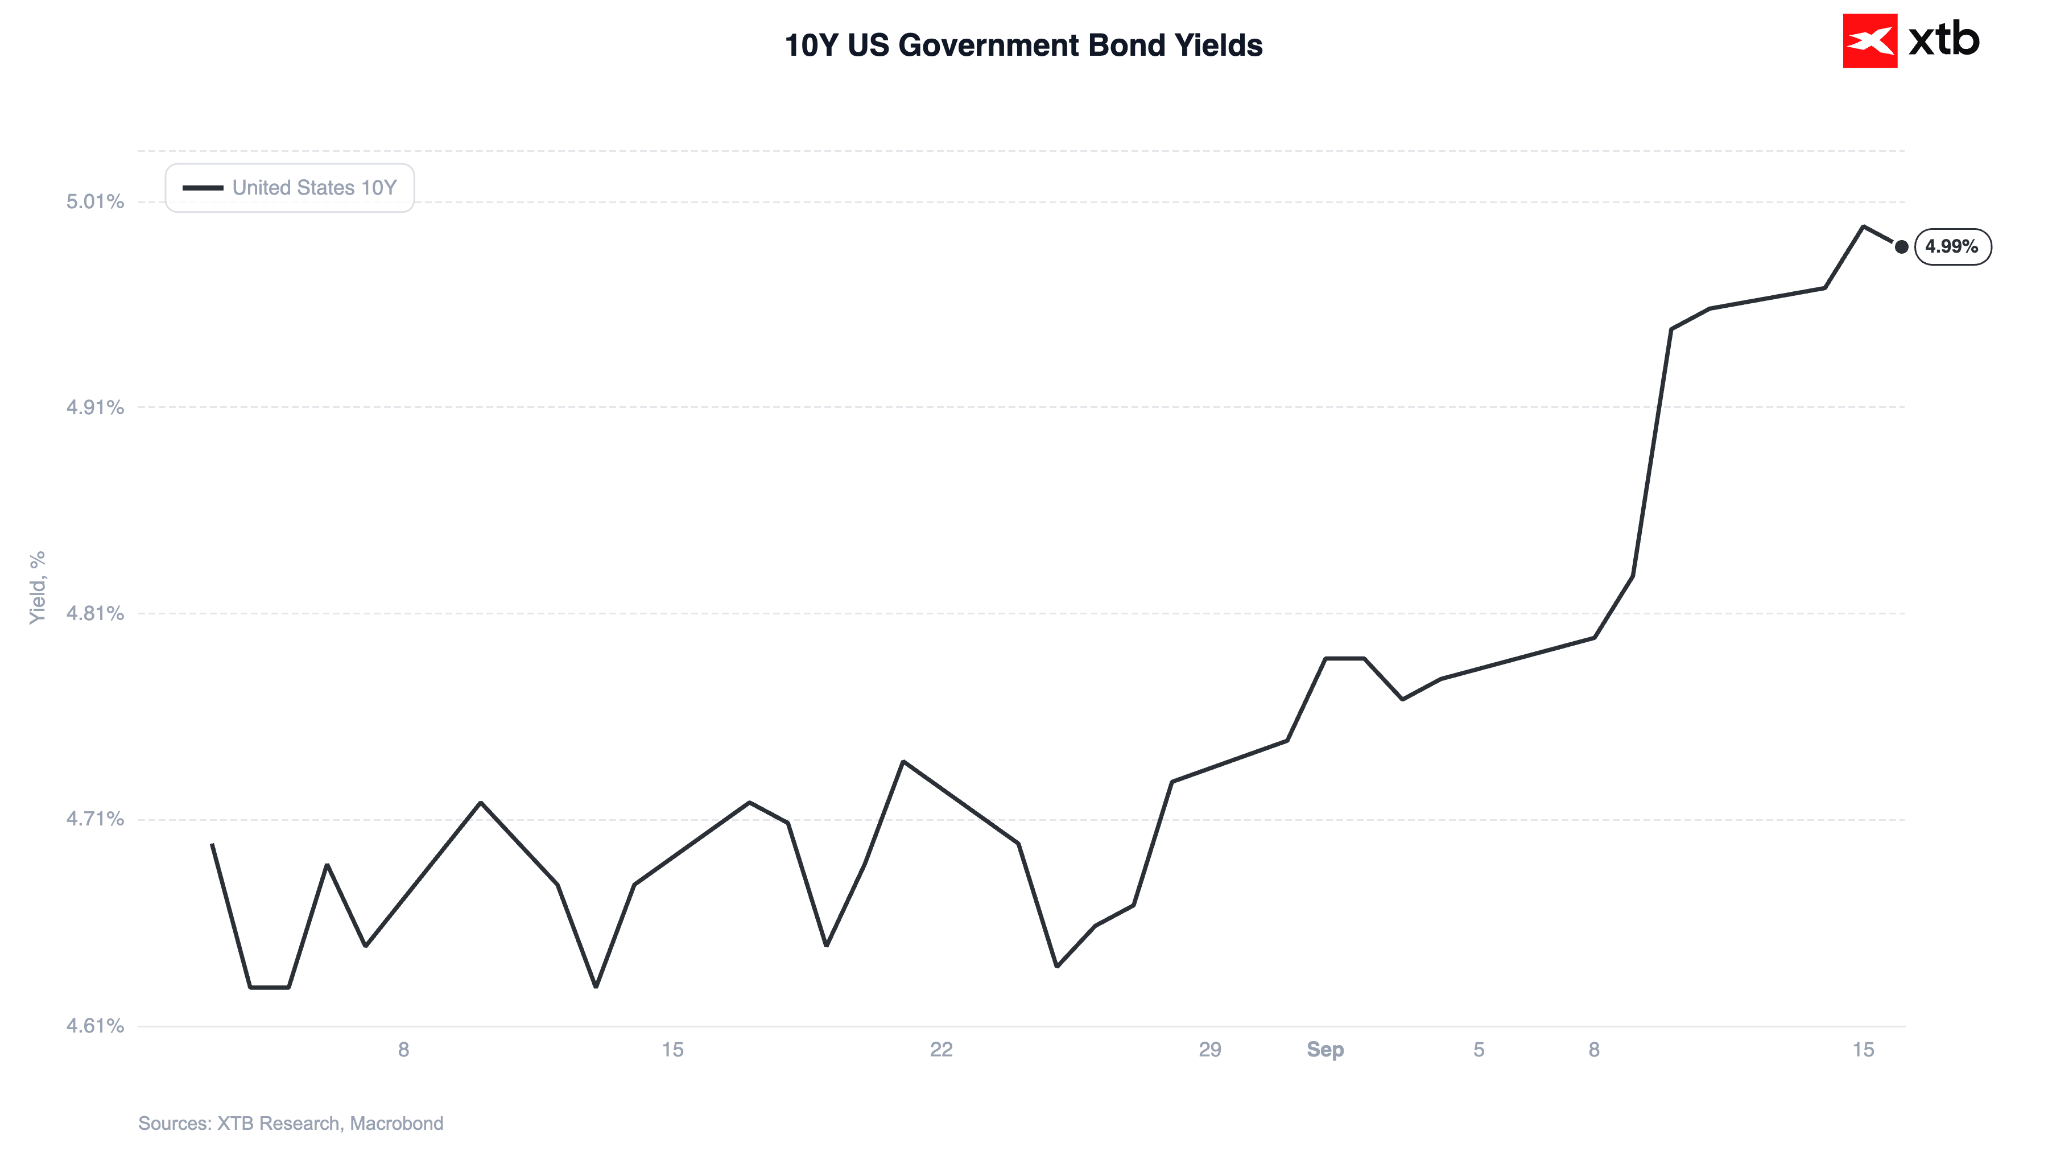
Ahead of the committee's decision, US 10-year Treasury yields have pulled back slightly from yesterday's peak (5.04%, the highest level since 2007), providing a brief respite for both equities and gold.
Figure 1: US 10-Year Government Bond Yields (08.2026 - 09.2026)
 Source: XTB Research, 16.09.2026
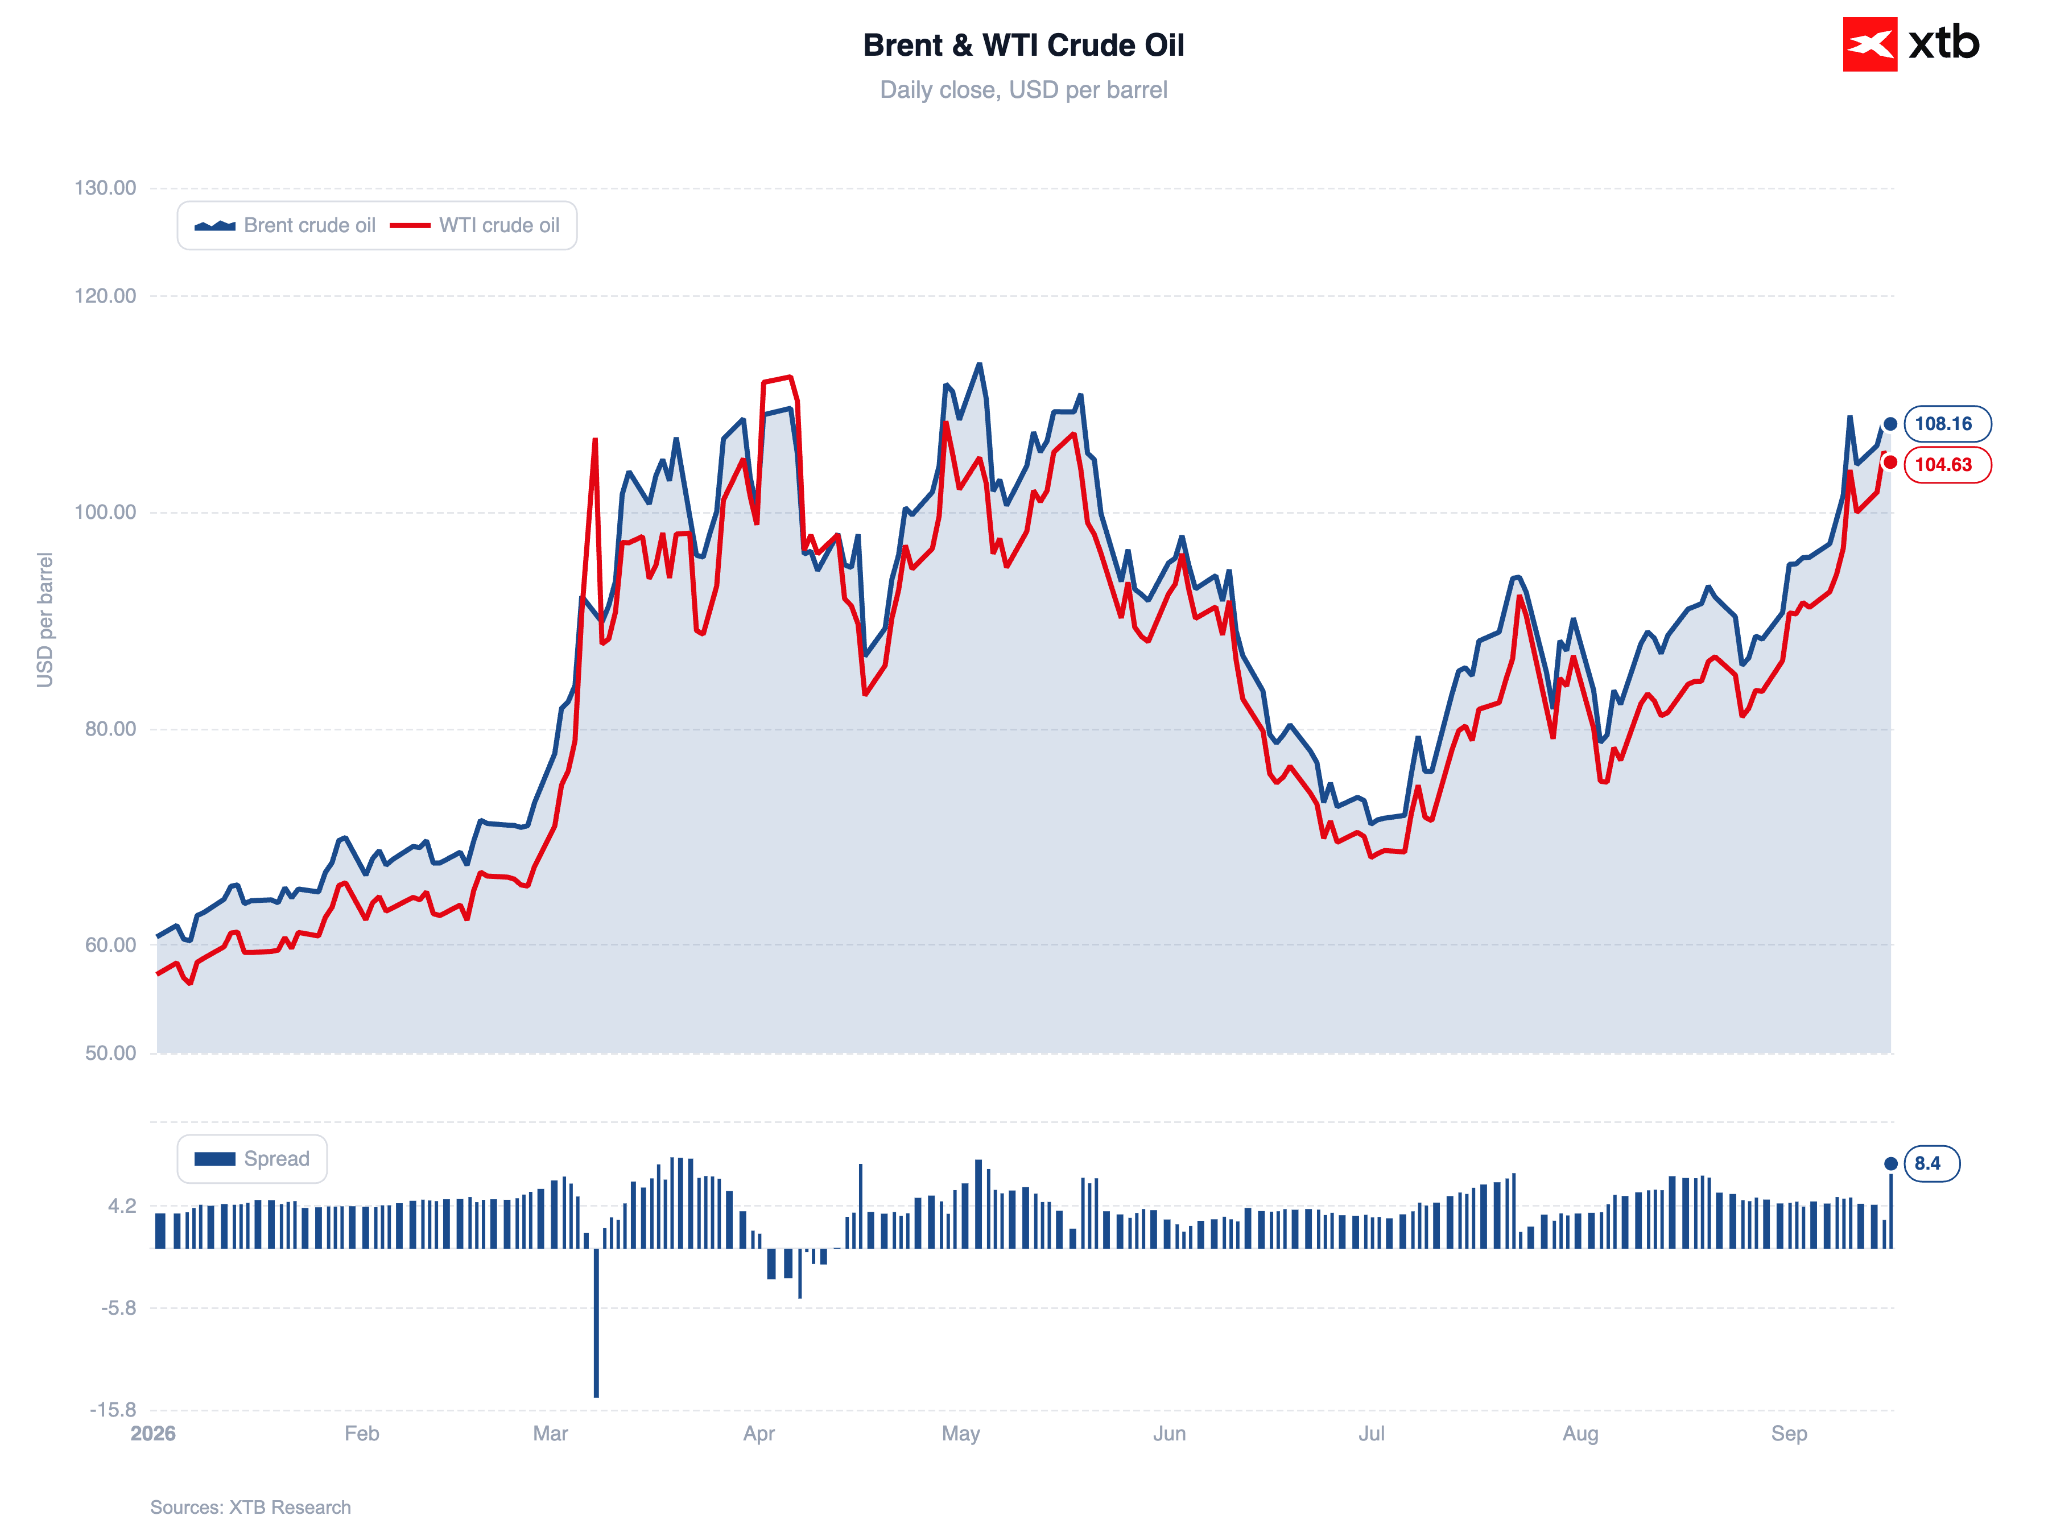
Oil has also paused its frantic rise, although it remains uncertain when the damaged Saudi East-West pipeline will resume operations. Brent is down by around 0.6% today, hovering near 108 dollars a barrel. Gold is gaining 0.8%, recovering part of the losses sustained earlier in the week.
Figure 2: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 16.09.2026
Slight declines in oil prices and bond yields are contributing to a modest improvement in market sentiment. Asia is trading in the green (although gains are relatively small). South Korea's Kospi is leading gains (+0.9%), supported by the resolution of a wage dispute at SK Hynix. The Nikkei and Shanghai Composite are also posting modest increases. Wall Street futures are marginally higher as well.
📈 Macroeconomic Data and Monetary Policy
Ahead of us is the most anticipated Fed meeting of the year. The market currently seems almost convinced that the statement, scheduled for release at 7:00 PM, will mention a 25 basis point interest rate hike – the first since July 2023.
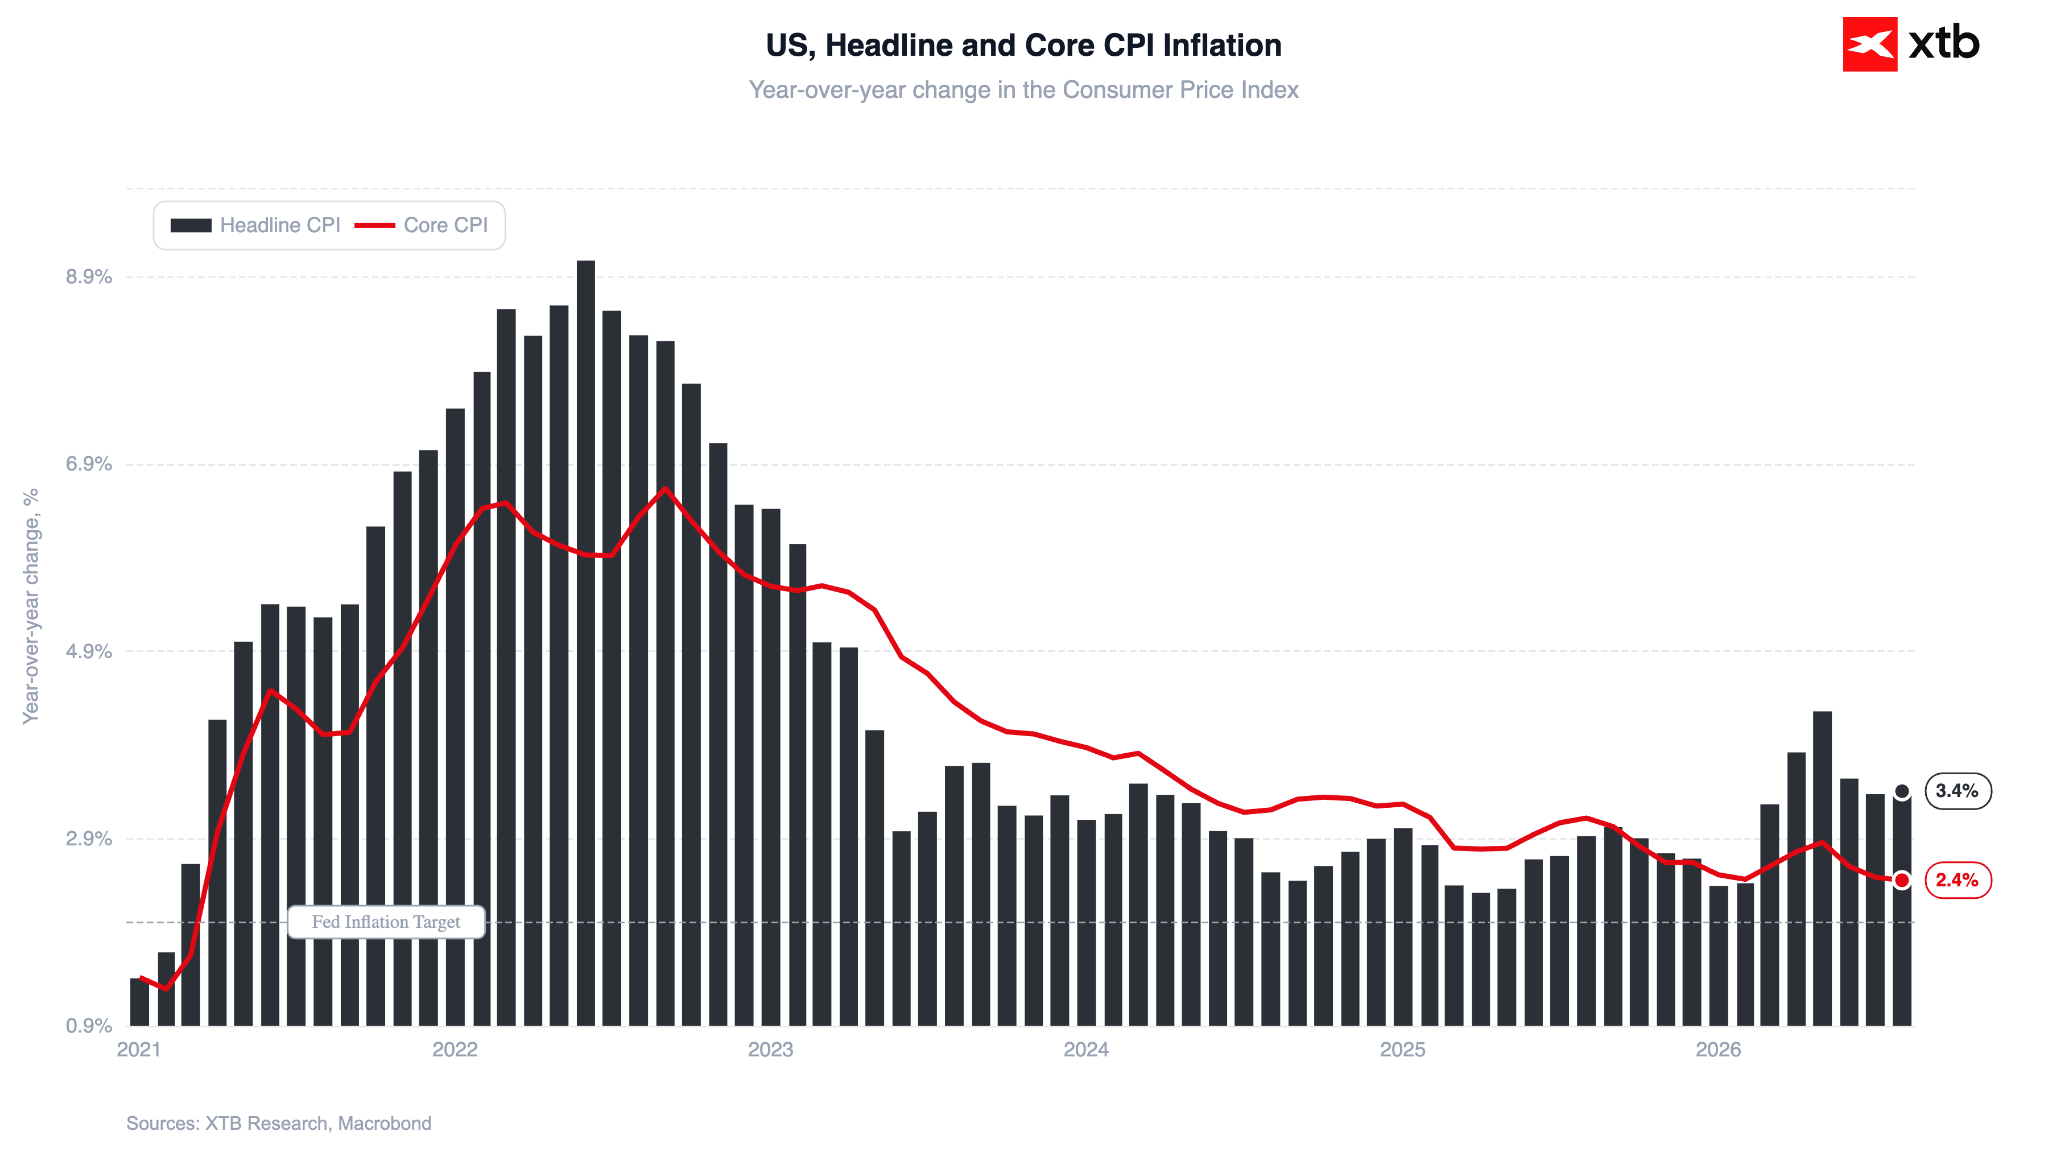
Last week's inflation reading, which according to Christopher Waller was supposed to tip the scales one way or another, provided no definitive answer, showing a fall in core inflation to 2.4% year-on-year. Markets focused their attention on the slightly higher-than-consensus monthly increase (0.3%), though in our view this is not sufficient to justify a rate hike.
Figure 3: US CPI Inflation (2026 - 2027)
 Source: XTB Research, 16.09.2026
Arguments for monetary tightening can be found in elevated services sector inflation (3.1%), though even here the momentum does not appear overly concerning. According to the Fed Wage Growth Tracker, wage growth is accelerating (4.1% in August), which could stimulate consumption in the coming months; however, current levels (less than 1% in real terms) do not seem poised to fundamentally alter the outlook. This is especially true given that American consumer spending over recent months (and indeed quarters) has relied heavily on dwindling savings, which will inevitably need to be rebuilt.
This does not mean, of course, that a rate hike lacks justification or is macroeconomically irrational. It can be argued in several ways. A key factor that could justify an upward move is the highly strained situation in the energy commodities market. High oil and LNG prices have not significantly spilled over into the US economy so far, but an acceleration of this process over the coming months cannot be ruled out.
A decision to raise rates could certainly be made as a form of "frontloading" – acting preemptively to prevent the potential need for much harsher tightening in the future. If the Fed indeed opts for such a move on Wednesday, it may raise questions as to why a hike was not delivered back in July, as macroeconomic data published since then has provided little additional support for the tightening thesis. Notably, the "frontloading" argument was advanced at the time by dissenting policymakers who voted in favour of a rate increase.
📈 Equities
Asian stock markets are mostly higher – Japan's Nikkei 225 is up 0.3%, China's Shanghai SE Composite gains 0.5%, while South Korea's Kospi advances 0.9%.
Gains in the key South Korean index are driven partly by the resolution of a collective dispute at SK Hynix – union members (57% of voters) accepted a new bonus split: half in cash, half in shares. The previously proposed arrangement was 40% cash and 60% shares. The agreement concludes two weeks of negotiations following the rejection of the initial draft in August. Shares in the company are up nearly 3%.
In the background, debate continues over the pace of AI development. South Korea's Deputy Prime Minister, Kyunghoon Bae, declared on X that the country "cannot afford to slow down" its artificial intelligence efforts, distancing himself from calls by the heads of Anthropic and OpenAI to slow development. South Korea's stance aligns more closely with the tone of Mark Zuckerberg and Jensen Huang than that of Dario Amodei.
On Wall Street, S&P 500 futures are posting modest gains (+0.2%), representing a slight recovery following yesterday's declines:
- S&P 500: -0.5%
- Dow Jones: -0.6%
- Nasdaq 100: -0.7%
- Russell 2000: -0.8%
Figure 4: Dashboard for Nasdaq 100 (15.09.2026)
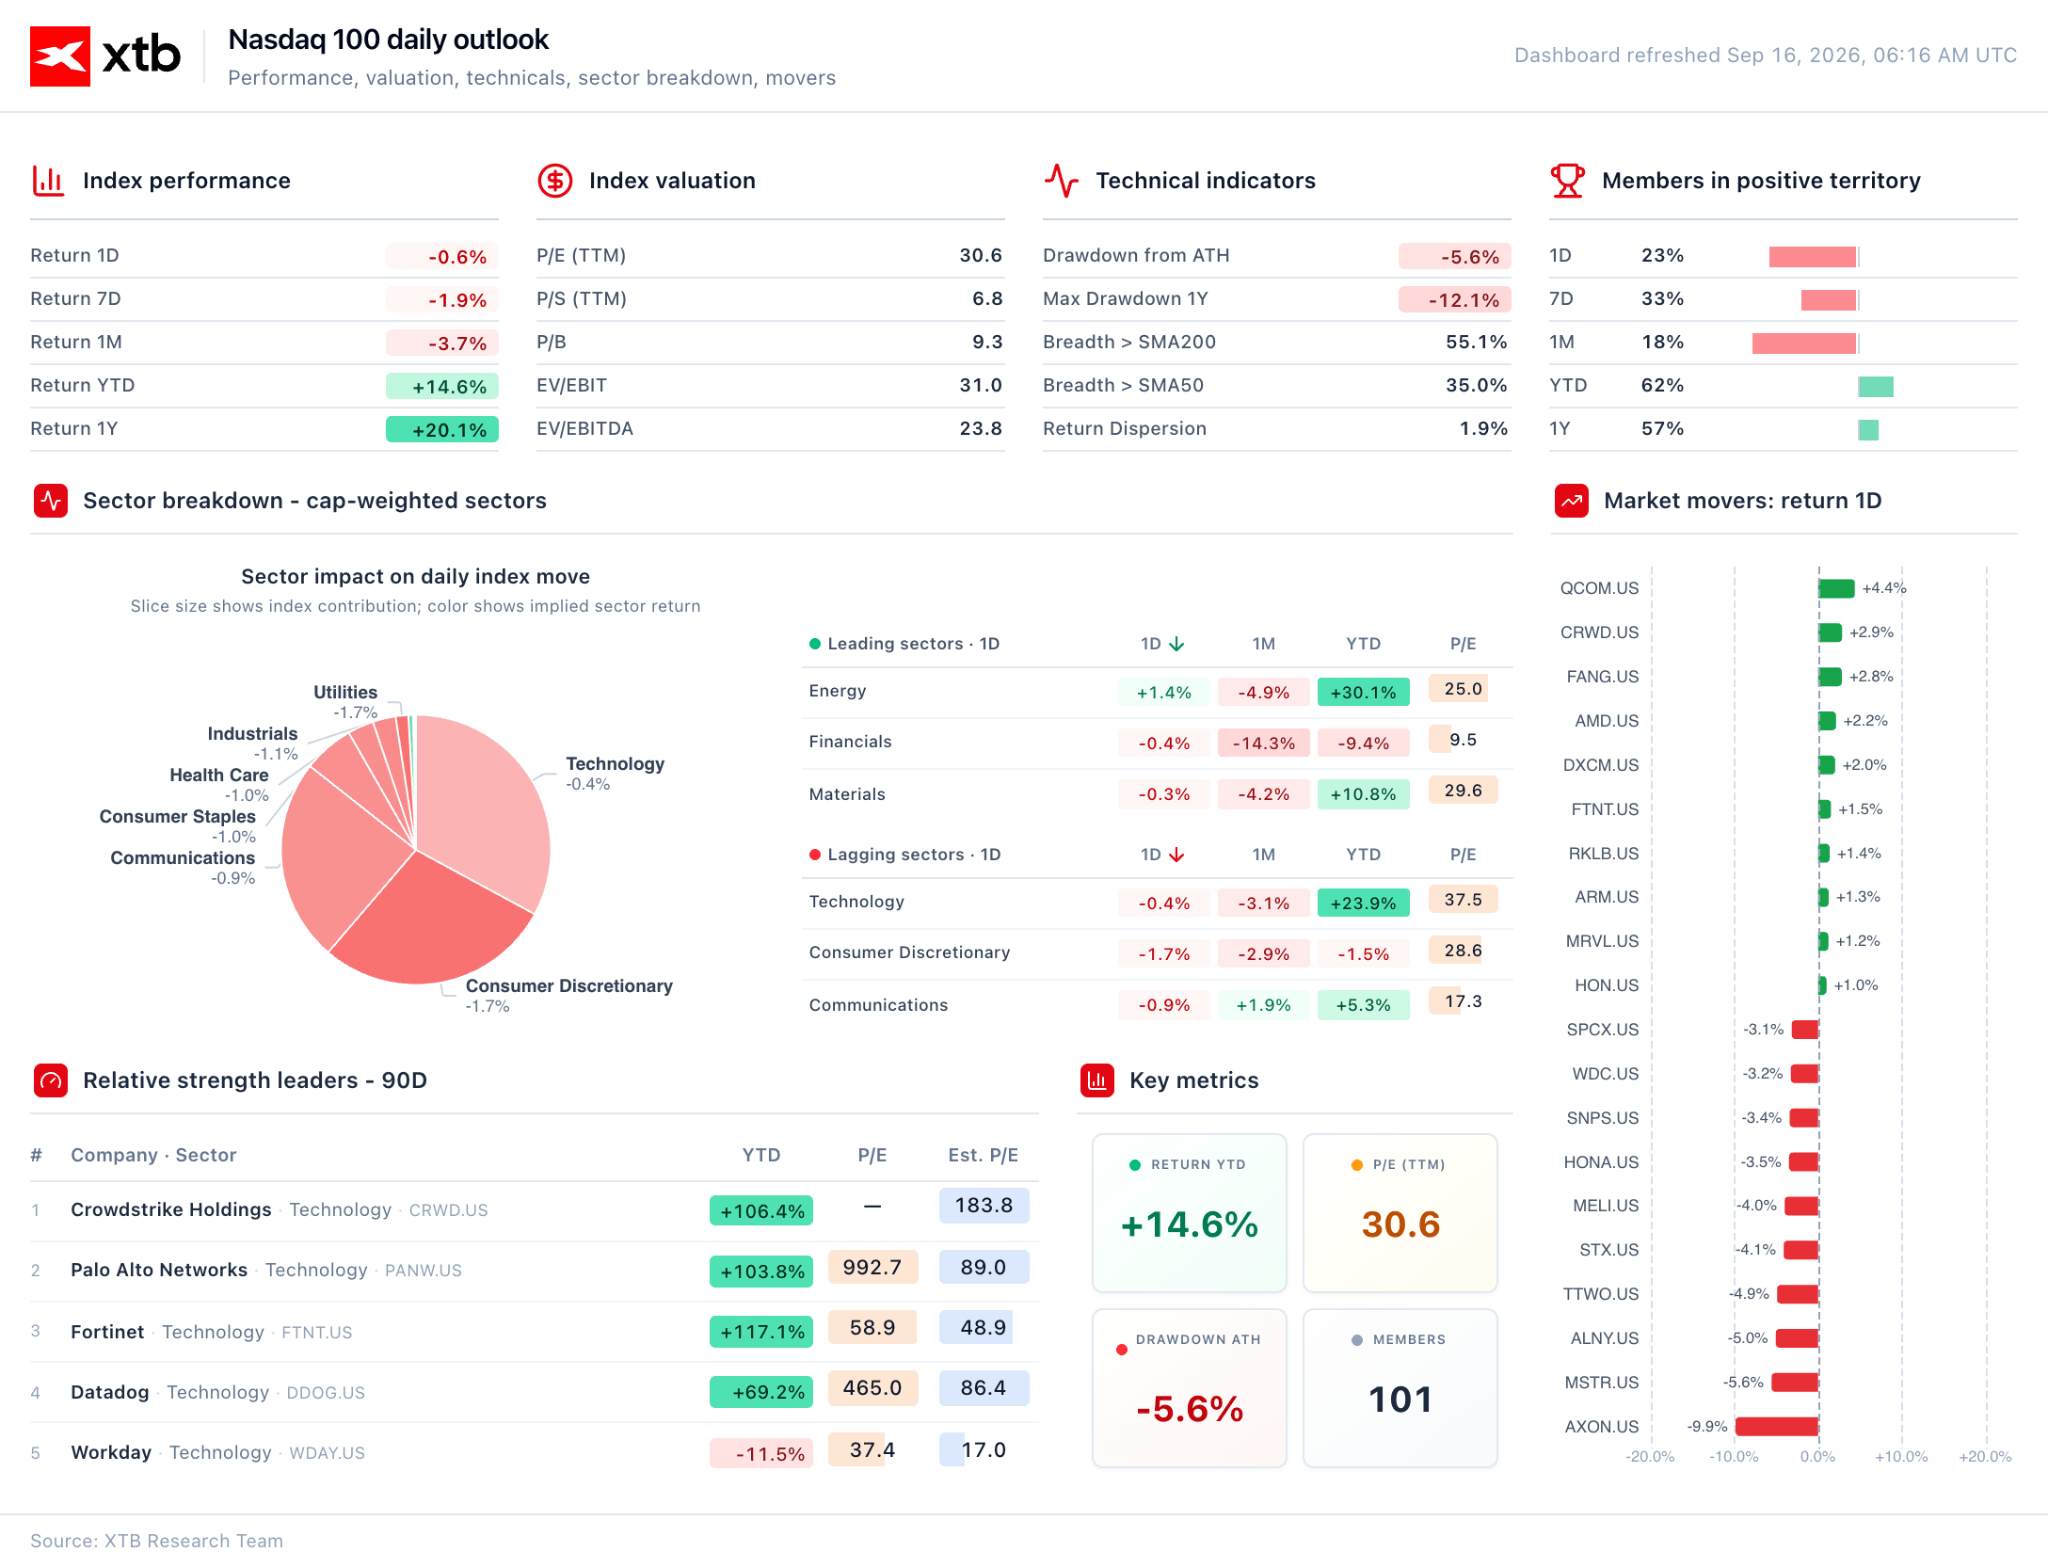 Source: XTB Research, 16.09.2026
It is worth noting that the VIX index, a key measure of expected volatility in the US equity market (the so-called "fear gauge"), remains surprisingly calm despite rising yields.
🌍 Geopolitics
On the diplomatic front, a telephone call took place between Oman's Foreign Minister, Badr Albusaidi, and US Secretary of State, Marco Rubio – the two parties discussed ways to de-escalate regional tensions and conditions for continuing diplomatic talks.
According to reports by the Wall Street Journal, Saudi Arabia plans to partially resume flows through the East-West pipeline within a few days, while full repairs to damaged pumping stations could take 6-8 weeks. In the meantime, Riyadh is delaying deliveries to certain European customers.
Growing uncertainty over Middle Eastern supplies is prompting Japanese refiners (Eneos, Idemitsu) to accelerate purchases of Omani crude – for delivery as early as October. Premiums for urgent deliveries are reaching up to 38 dollars a barrel over the Dubai benchmark, reflecting the severity of tension in the physical market.
Oil is pulling back after two sessions of gains – the market appears to be concluding that the scale of the rally driven by supply disruptions was overdone. Downward pressure is also stemming from an increase in US inventories – according to API data, crude stocks rose by 7.1 million barrels.
- Brent is down 0.6% (currently around 108 dollars a barrel)
- WTI is down 0.9% (slightly below 105 dollars a barrel)
Despite the correction, prices remain near multi-month highs.
🪙 Precious Metals
Gold is rebounding following a two-day sell-off, gaining 0.8% to around 4330 dollars per ounce (in Asian trading, prices reached as high as 4340 dollars). Silver is posting stronger gains, up 1.5% to 64.6 dollars. Precious metals are supported by a pull-back in 10-year Treasury yields below 5% (though the market still prices in a more than 90% chance of today's rate hike).
Figure 5: Gold (06.2026 - 09.2026)
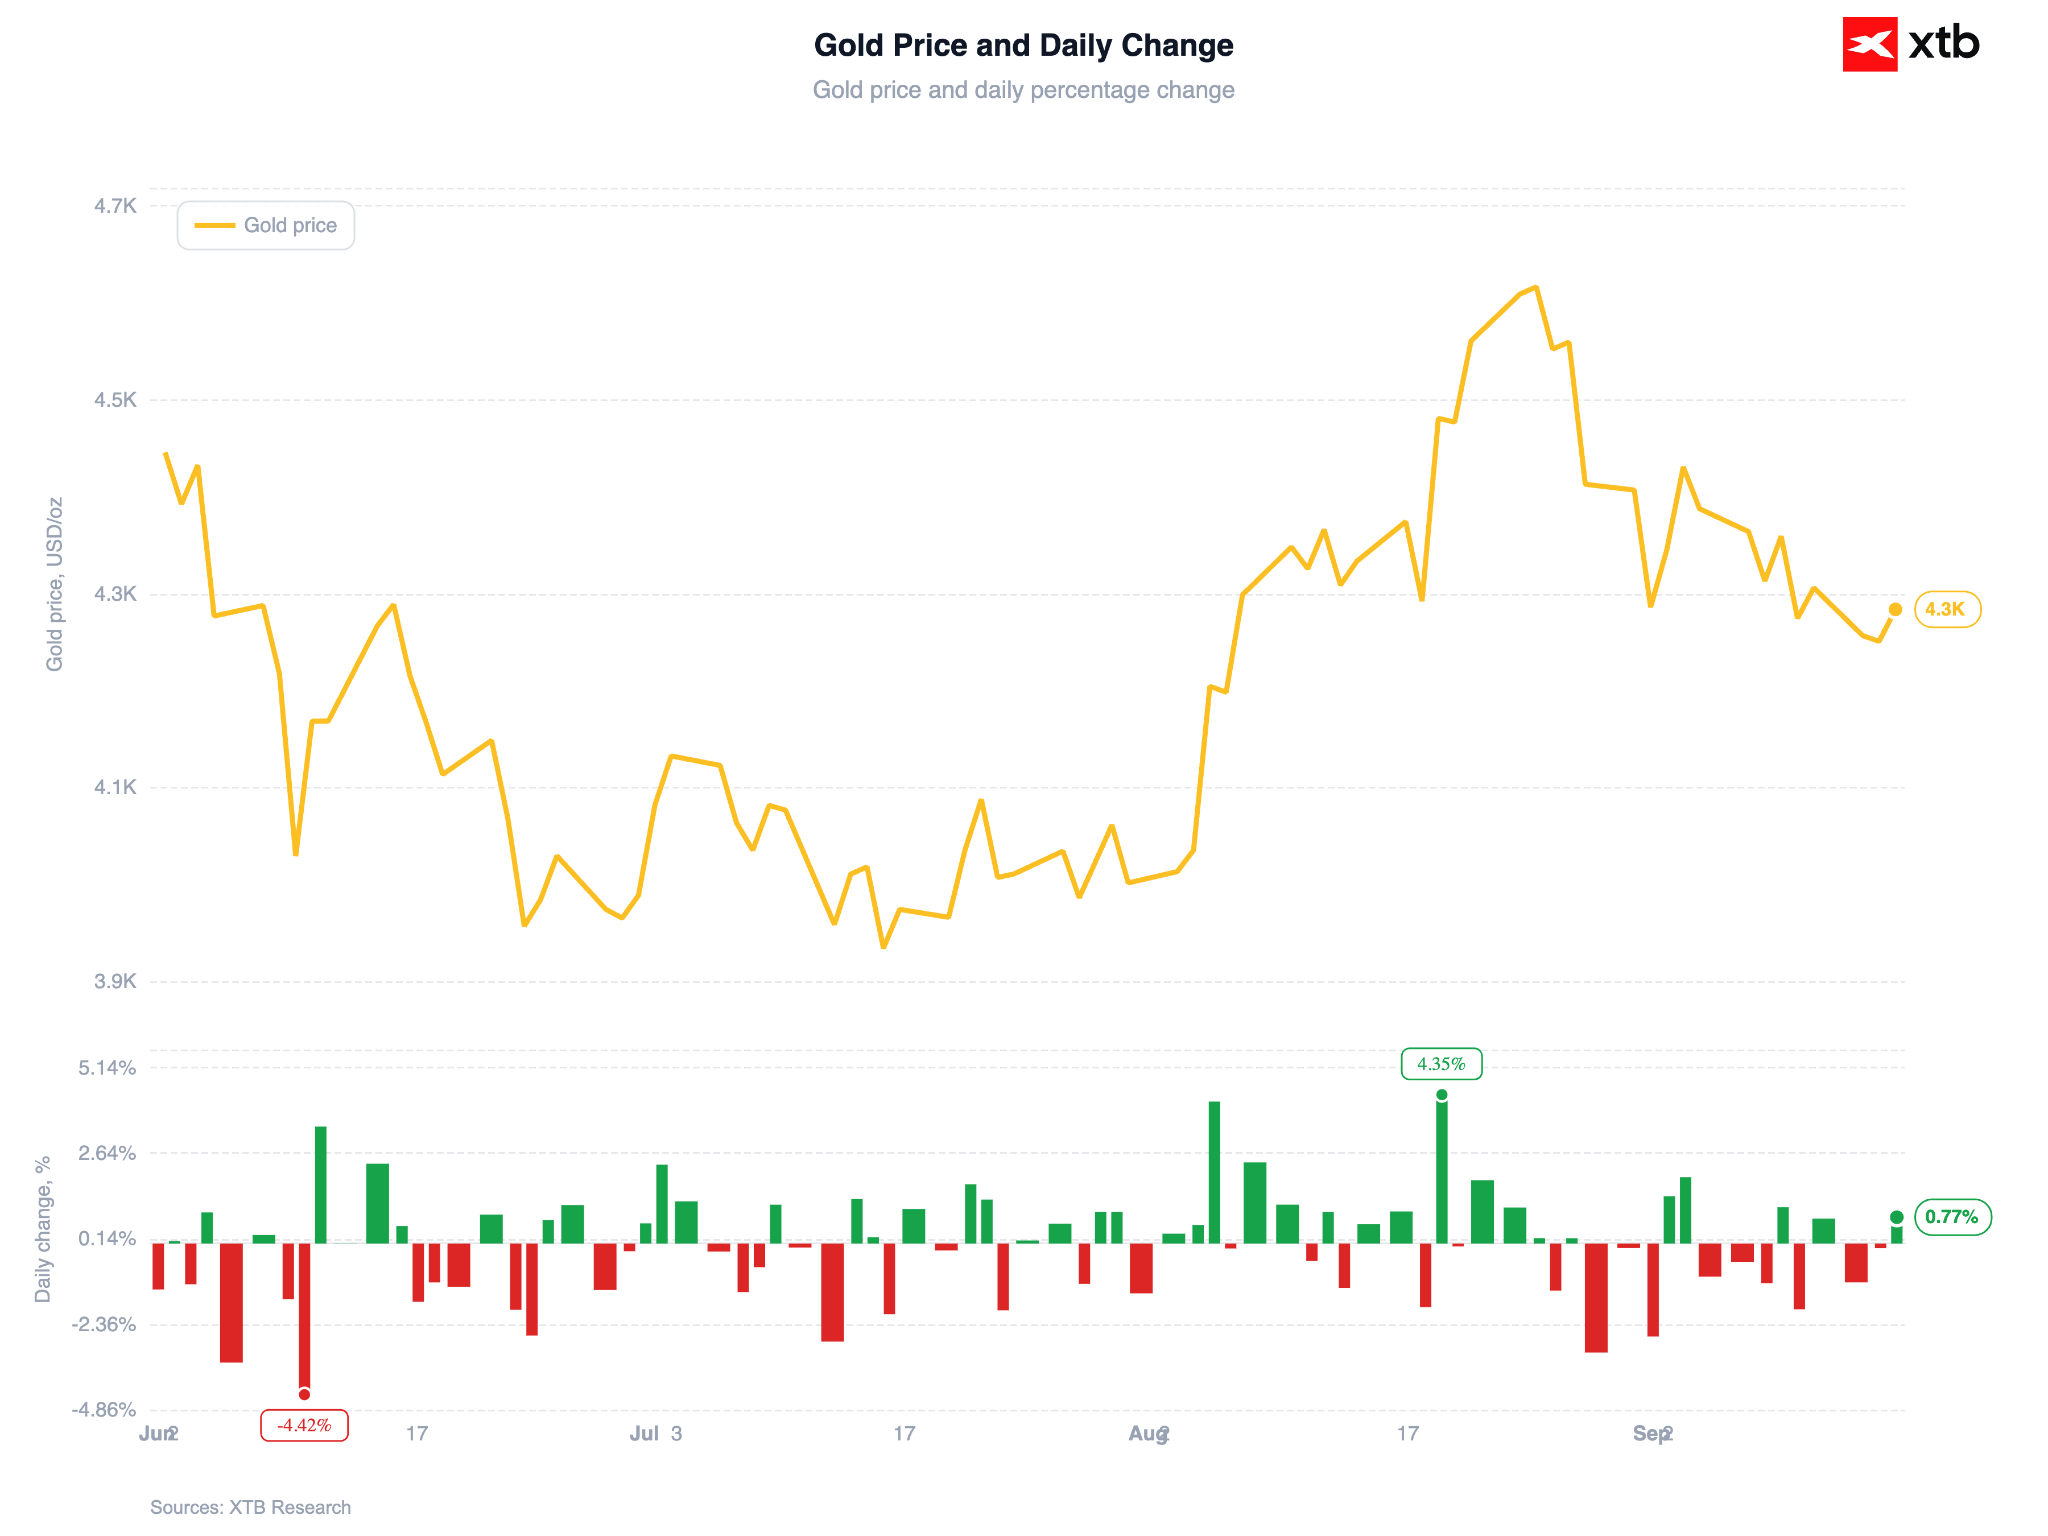 Source: XTB Research, 16.09.2026
The main uncertainty is no longer the rate hike itself, but what the Fed signals for the future – if Warsh leaves the door open to further tightening, gold may prove more vulnerable to downside risk.
💱 Currencies
The US dollar is strengthening for a third consecutive day against all G10 currencies (though the move remains exceedingly modest).
Figure 6: Major Currencies vs US Dollar (09.2026)
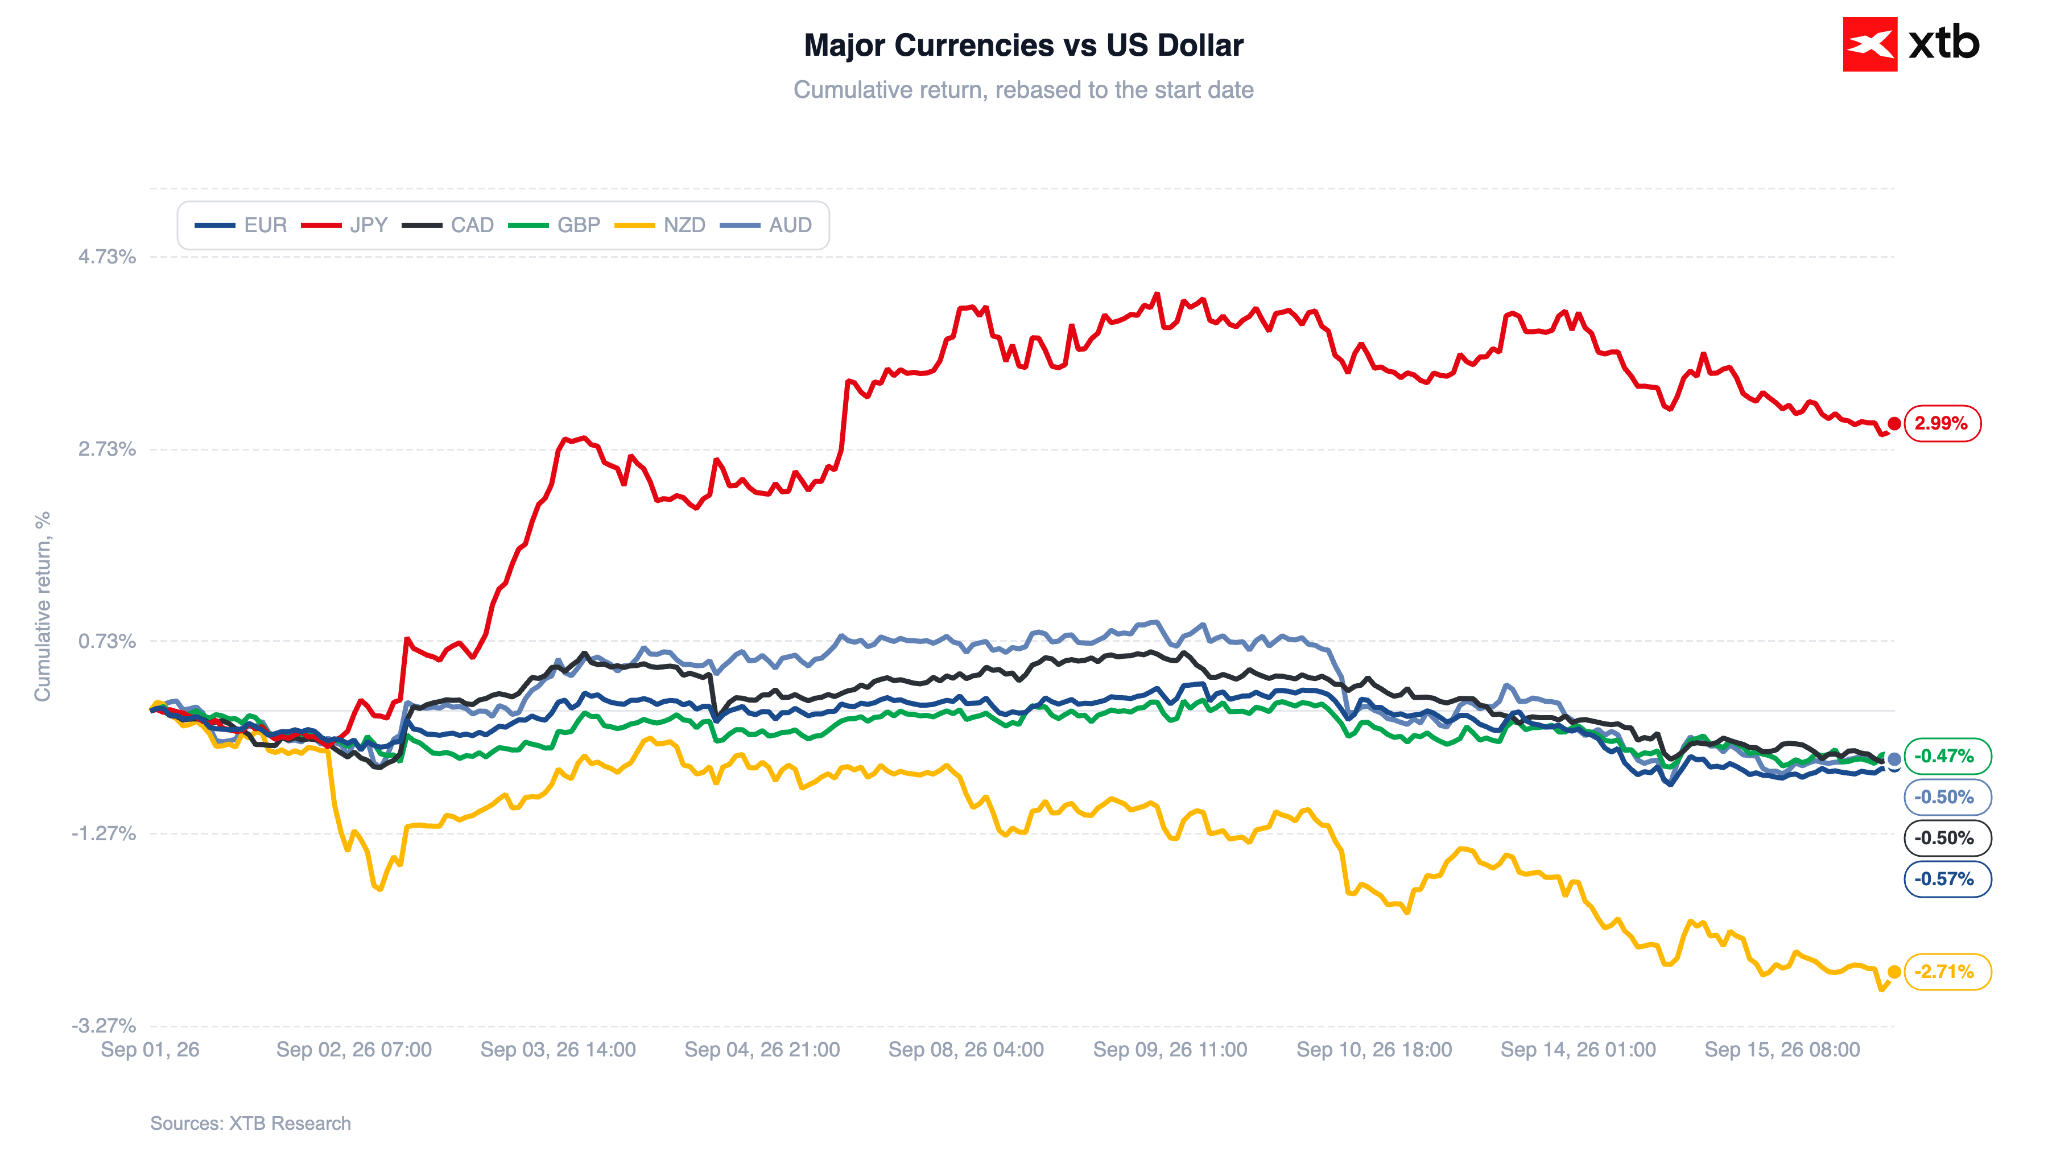 Source: XTB Research, 16.09.2026
₿ Cryptocurrencies
Bitcoin remains stable around 75,800 dollars (-0.1%), while Ethereum drops 0.3% to 2,400 dollars. The sector faces pressure following the US Senate's blocking of landmark crypto regulation legislation.
Figure 7: Bitcoin (2023 - 2026)
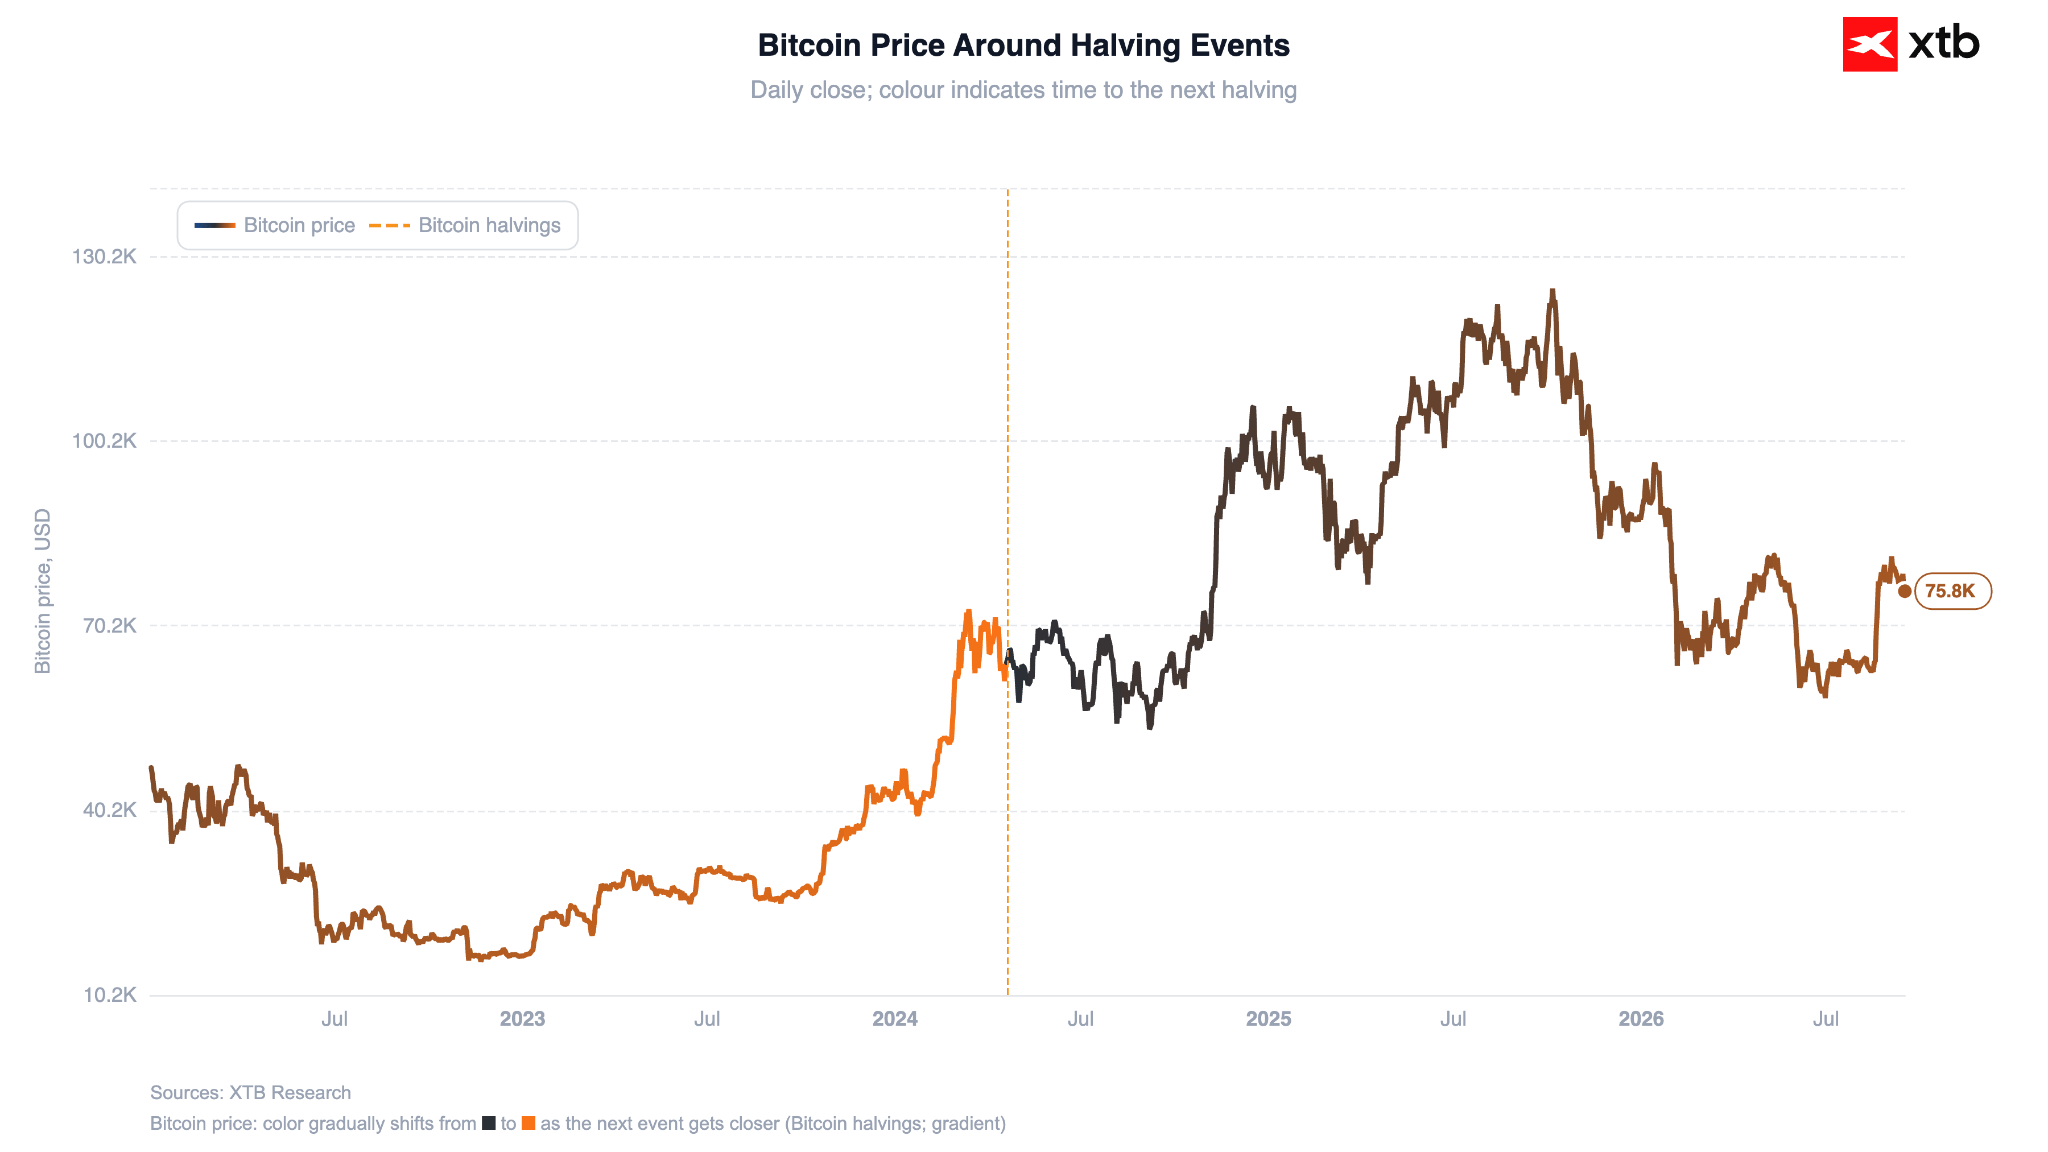 Source: XTB Research, 16.09.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB


Economic Calendar: Time for an interest rate hike? (16.09.2026)



Will Trump dissuade Fed from a rate hike? [FOMC Preview]

🟡⬇️Gold loses ahead of Fed decision

Chart of the Day: Gold at five-week lows - what stands behind the decline? (15.09.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.