


Geopolitical developments: U.S. President Donald Trump rejected Iran’s proposal for a conditional ceasefire and the reopening of the Strait of Hormuz within seven days, announcing that attacks would resume after the November elections. Tensions in the Middle East are rising—reports indicate that Iran fired a cruise missile in the Strait, while Yemen’s Houthis targeted Riyadh, disrupting airport operations. The US-China summit in Washington, D.C., which has concluded, yielded limited results, including a mere two-month extension of the trade truce and a preliminary agreement on tariff reductions and dialogue on artificial intelligence.
Economy: Profits in Chinese industry rose by just 4.2% year-over-year in August, the weakest performance this year, reflecting pressure from weak demand and high energy costs. In Japan, meanwhile, producer price inflation (PPI) jumped to 3.7% in August, reaching its fastest pace in more than two years. This coincided with the release of the minutes from the Bank of Japan’s July meeting, which indicate that some policymakers recognize the risk of higher inflation and support faster interest rate hikes.
Major market movements: U.S. stock futures (Dow Jones, S&P 500, Nasdaq-100) are trading lower ahead of the market open, erasing some of last week’s gains. These moves are a direct reaction to the sharp rise in U.S. Treasury yields, with the 10-year yield reaching 5.17–5.23%, its highest level since 2007. The rising cost of capital is particularly weighing on sentiment toward tech companies involved in AI infrastructure development, for which debt servicing is becoming increasingly expensive.
Asian Markets: The trading session in the Asia-Pacific region was marked by declines, driven by both the escalation in the Middle East and rising yields in the U.S. Japan’s Nikkei gave up its morning gains and is now trading slightly in the red, dragged down by a sell-off in U.S. Nasdaq futures. After a long weekend, South Korea’s Kospi plummeted 2.36% under the weight of a sell-off in tech giants, while China’s CSI 300 index lost 1.4% following weak industrial data. One of the few markets to post gains was Hong Kong, where the Hang Seng Index rose by about 0.6–0.7% thanks to strong performance in the energy sector.
Currencies: In the foreign exchange market, the major currency pairs are trading within fairly narrow ranges, with the New Zealand dollar currently performing the best. The U.S. dollar remains strong on the back of rising yields, and the USD/JPY exchange rate is up 0.32% this morning, trading around 157.75.
Commodities: Oil prices skyrocketed after the U.S. withdrew from the Iran deal—Brent crude rose 2.7% to nearly $100 per barrel, while WTI climbed 1.8% to about $94. Meanwhile, the strong bond market is taking a heavy toll on precious metals, raising the opportunity cost of holding them. Gold broke through a key technical support level, falling below $4,200 per ounce (-2.16%), while silver is down nearly 3.75%.
Companies: Shares of the Australian company Northern Star rose more than 9% after its board rejected a $27 billion takeover bid from Gold Fields, deeming it undervalued. In the United States, attention is focused on SpaceX, which is preparing the 14th test flight of its Starship rocket with the goal of achieving the first-ever entry into orbit. The U.S. administration is also considering a 90-day ban on diesel fuel exports, which, according to Goldman Sachs analysts, could lower domestic diesel prices but at the same time drive up gasoline costs for American consumers and hurt refinery margins.
Cryptocurrencies: The digital asset market is part of a broader trend of risk aversion triggered by rising yields. Bitcoin is down more than 1.6% this morning, slipping to just over $83,220.
Outlook for the Day: Markets will continue to react today to geopolitical turmoil and pressure from the bond market. Later in the week, key catalysts for investors will include Micron’s earnings report on Wednesday, which will set the tone for the semiconductor sector, and important U.S. macroeconomic data. Wednesday’s reading of the Fed’s preferred measure of inflation (PCE) and Friday’s U.S. jobs report are expected to determine the future path of interest rates.
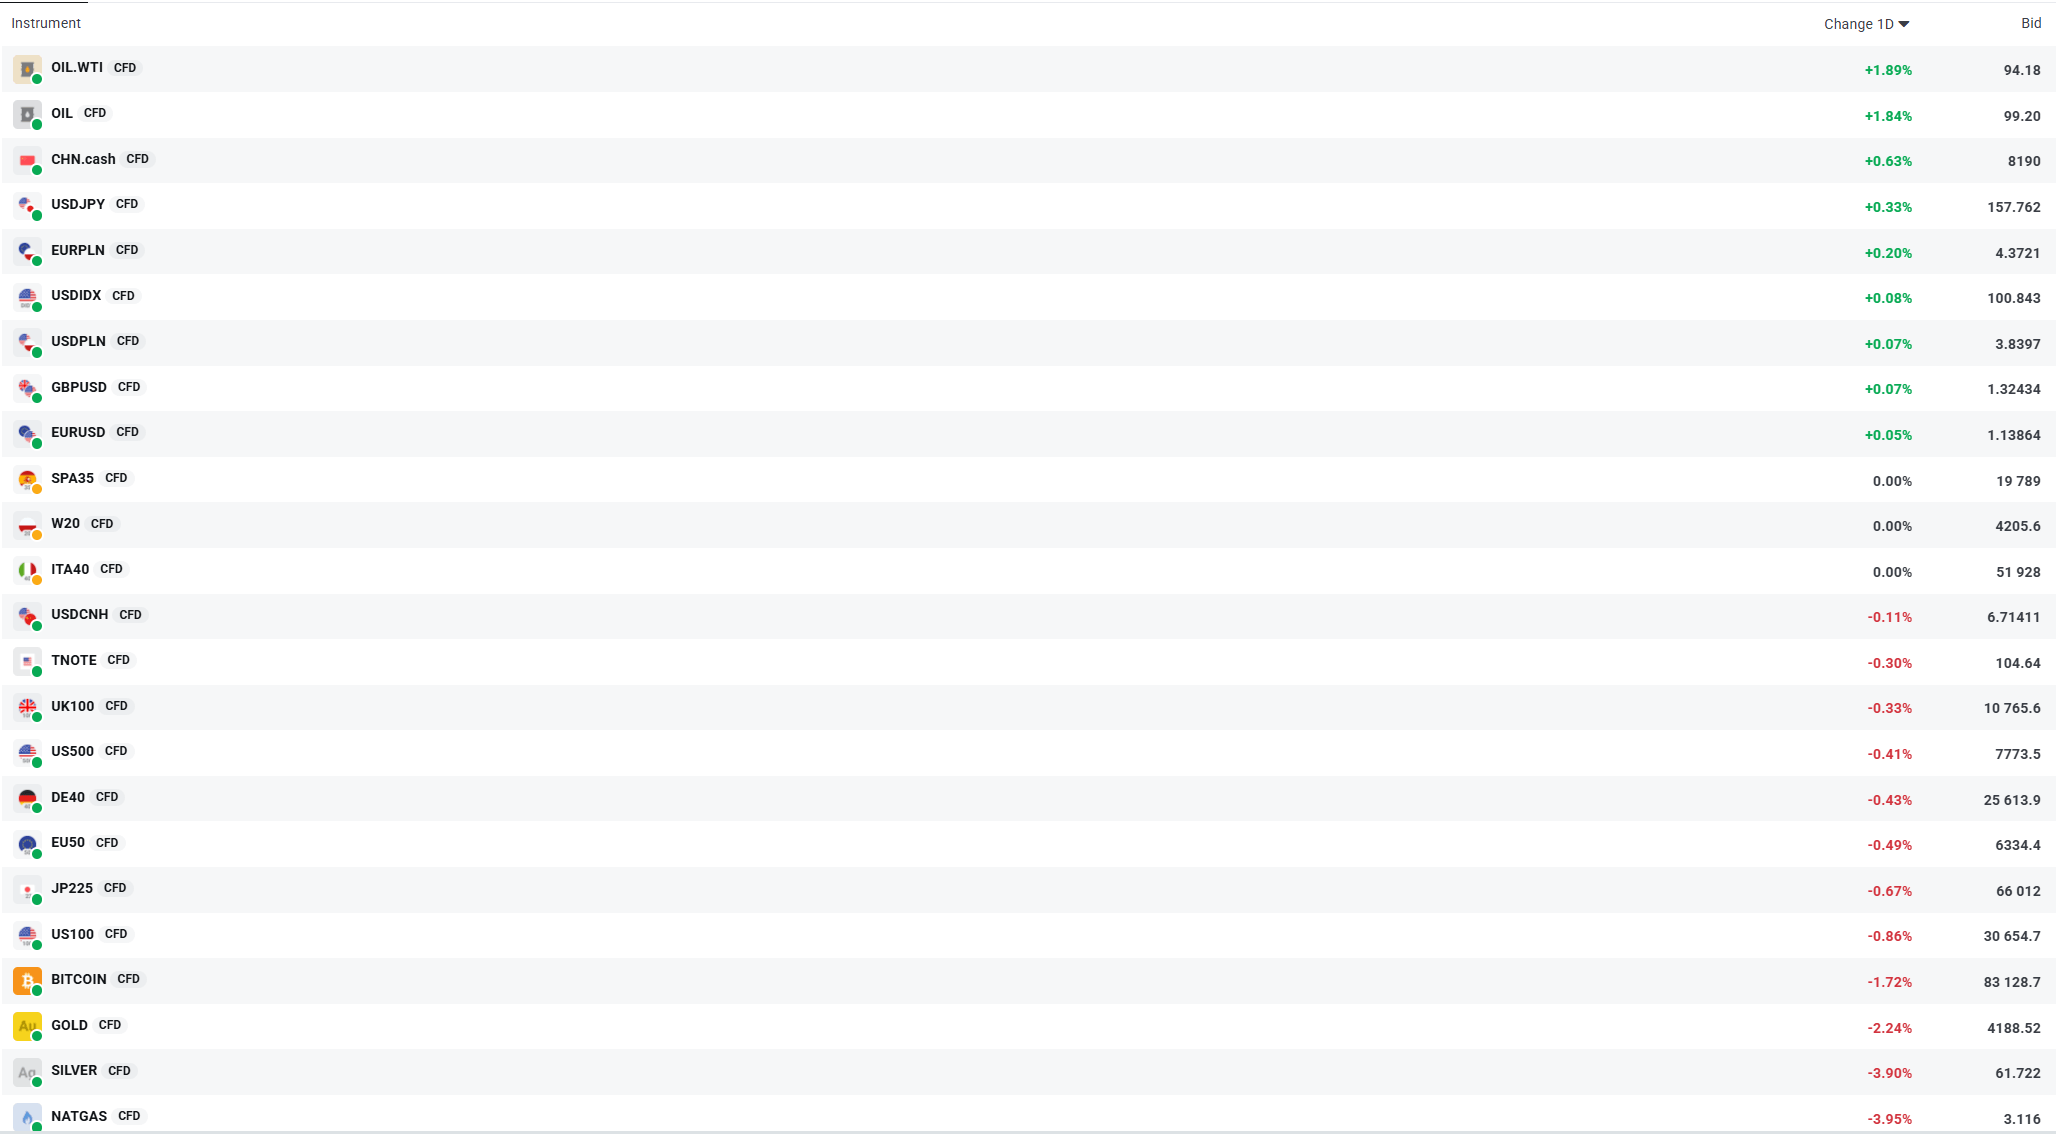
Volatility is currently evident in several selected instruments. GOLD is performing very poorly, down more than 2%, while SILVER is down nearly 4%. Source: XTB



The Week Ahead


Economic Calendar: Gold Prices Plunge Amid Central Bankers' Speeches🏛️

Daily summary: Nasdaq gains despite rising bond yields 📈 Oil below $100


3 markets to watch next week (25.09.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.