

- Oil prices fall again, which helps sovereign bonds rally
- Double whammy of good news for the UK Gilt market
- Market ignores Burnham spending pledges
- French- German sovereign yield spread surges
- US PCE a key test for Treasuries
- Micron results crucial for the AI trade

- Oil prices fall again, which helps sovereign bonds rally
- Double whammy of good news for the UK Gilt market
- Market ignores Burnham spending pledges
- French- German sovereign yield spread surges
- US PCE a key test for Treasuries
- Micron results crucial for the AI trade
Markets are in an upbeat mood this morning, and stocks and bonds are rallying together even though inflation in France was stronger than expected and UK GDP also received a surprise upside revision for the second quarter. This suggests that the main driver for sovereign bonds right now is the oil price.
Brent crude is slipping this morning, and the front month contract is trading around $96, which is a drop of more than 4% in a week. This is having an ameliorating impact on financial markets after a turbulent month, with European and US indices posting losses for September, although Asian stocks managed to post decent gains.
There was a double whammy of good news for the UK Gilt market this morning, with the upgrade to Q2 GDP, which was revised higher to 0.5% from the original estimate of 0.4%, This suggests that the UK economy was resilient to the effects the Iran war, the energy price surge and the rise in borrowing costs. Stronger services growth and rising household spending boosted the figure. This is fairly typical of the UK economy, which is service based, the real surprise was the strength of business investment and an improvement in the trade figures, which showed a boost in exports.
GDP per head was strong too, at 1.1%, the highest level since the post-Covid boom, growth is now running at a 1.1% rate for the first 6 months of the year, which is the highest rate in the G7. The Gilt market likes what it hears, and is leading a major recovery in sovereign bonds this morning. The 2-year Gilt yield is down some 8bps this morning, and the 10-year yield is down 7bps. September has been a volatile month for global bonds, especially Gilts, and even with this recovery, 2-year Gilt yields are still higher by 30bps and 10-year UK yields are higher by 20bps.
Strong growth is good news for the Gilt market when it is accompanied by dovish commentary from central bankers. Alan Taylor talked down the need for the BOE to raise interest rates, since second round inflation effects are not noticeable. If these do start to feed through to the economy then Taylor said that he would change his mind on rates. However, his remarks are a keen reminder that wage growth, especially in the private sector, remains contained for now, which could limit the BOE when it comes to raising rates.
The rally in Gilts is boosting the pound, which is leading the G10 FX space on Wednesday. GBP/USD is higher by 0.27% as the dollar slides. The euro is also making gains, as inflation concerns bite. French inflation was much stronger than expected and jumped to 3.4% from 2.6% in September. Although an increase was expected, this was worse than analysts feared. This is the fastest pace of inflation in France for 2 years, and French bonds are underperforming on Tuesday. This data will add pressure to the ECB to raise interest rates this year, as energy prices including diesel remain elevated, even if the oil price is retreating.
French inflation data has also caused another blowout in the French-German 10-year yield spread, which is now at 120bps, the highest level since 2012. There is also a fascinating link between politics and the cost of living. With inflation in France running at an elevated level, some political analysts argue that this could trigger a surge in support for Marine Le Pen and the far right, as we lead up to next year’s Presidential election. Populists in charge of a fiscally weak nation like France are likely to spook bond investors, and we could see this French bond premium maintained for the long term.
Politics didn’t influence the UK Gilt market, even though Andy Burnham seems to be making massive unfunded spending pledges. He announced a rethink of the pension triple lock, which will smooth out the increase to the state pension, during his speech at the Labour Party conference on Tuesday. At the same time he announced that he would put forward a plan for a national health-like social care service.
However, Burnham’s sums do not seem to add up. Any savings from scrapping the triple lock will take years to have an effect on the UK’s public finances, and Labour is now rowing back on its social care plan, saying that it would not include funding for residential care or bed and board. This is probably more sensible in the long run, but it does highlight the handcuffs on the PM right now. He didn't dare talk about tax rises, as massive increases in tax under Keir Starmer and Rachel Reeves were deeply unpopular with the electorate. Hence why the bond market is willing to ignore Burnham’s plans right now.
Elsewhere, the focus is likely to shift to the US, as we wait for PCE data this afternoon. We have yet to see UK yields diverge significantly from Treasuries, but if we get a stronger than expected PCE inflation, could we see US Treasury yields extend gains, and UK Gilt yields continue to recover? The market is expecting the annual rate of core PCE inflation to remain at 3.3% for August.
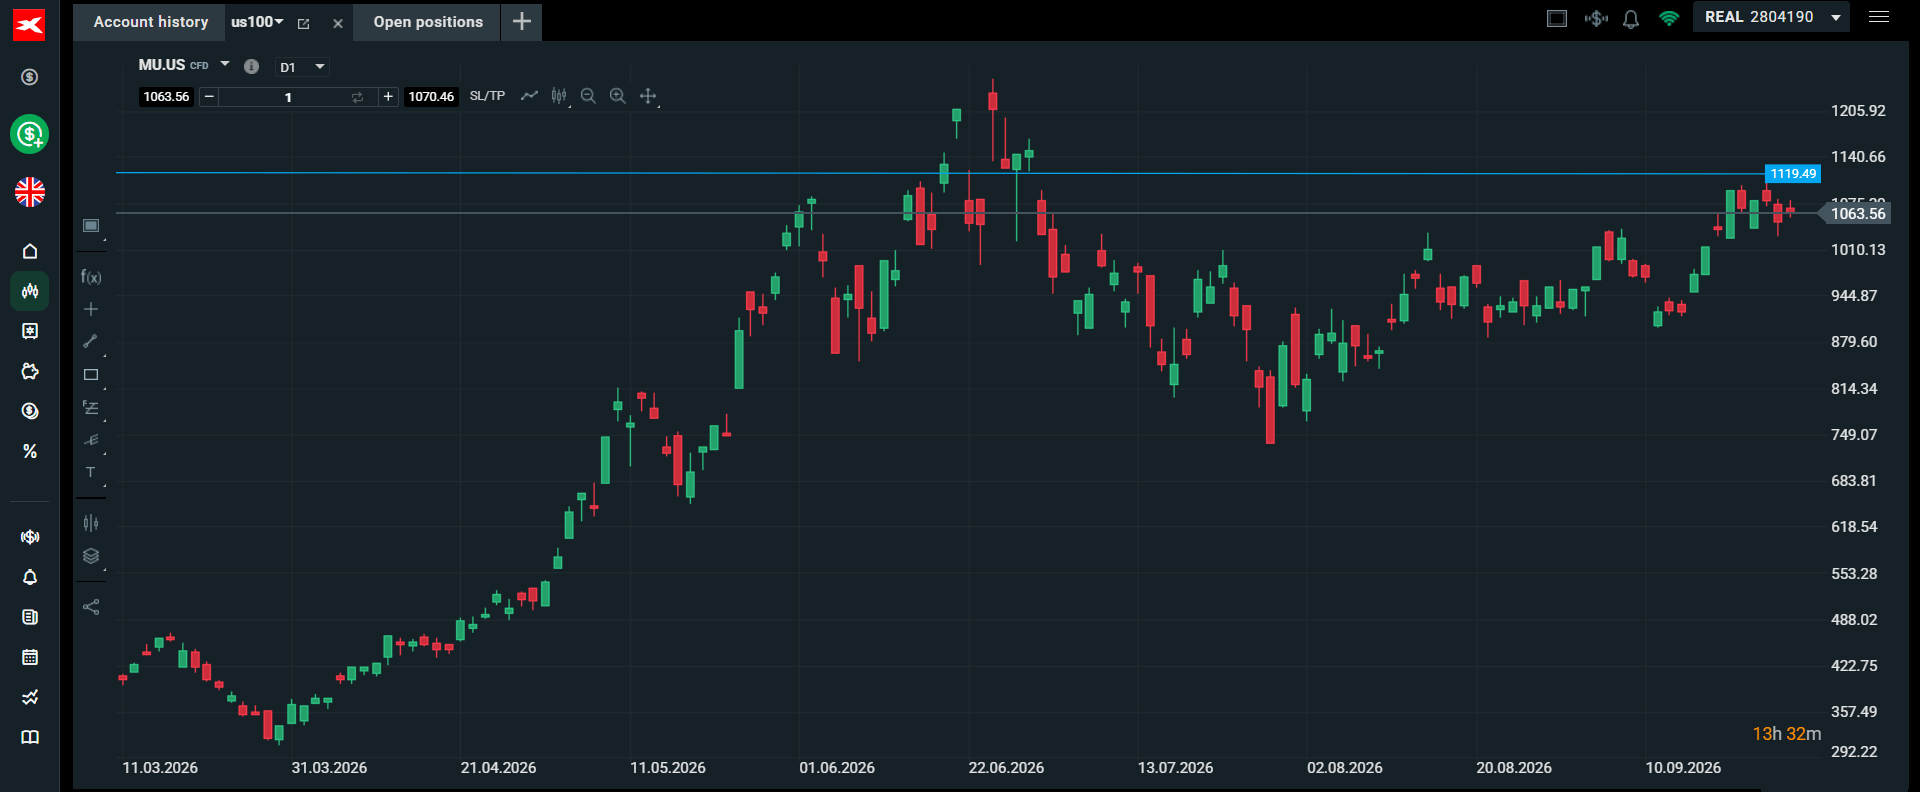
As we lead up to this data, US stock market futures are rising, and Treasuries are recovering, although they are underperforming European bonds right now. Micron, the high performance memory chip producer, will announce results tonight. This is seen as a key driver for the AI trade. Revenues are expected to come in at $50bn, with gross margin at 86%. The focus will be on the company’s quarterly outlook for revenue. The surge in memory costs means that the market expects a big number. The stock is priced for perfection, it is up by 15% in the past month, and by 260% YTD. This is why these results are crucial to US and Korean chip stocks in the short term.
Chart 1: Micron share price
Source: XTB


BREAKING: Drop in distillate stocks encourages oil to rebound


US OPEN: Lower Core PCE inflation gives relief to Wall Street, markets rise after GDP revision



PCE cools October rate hike expectations, as stocks surge into quarter-end
US PCE lower than expected, GDP beats expectations🗽Wall Street reacts
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.