


Sentiment in global equity markets has noticeably improved, and investor focus is shifting toward the upcoming US CPI inflation readings following the shock caused by Friday's strong US Non-Farm Payrolls (NFP) report. In Europe, the Sentix investor confidence index fell in November to around 2.4 pts (compared to just under 2.7 pts a month earlier), though it came in slightly above market forecasts of around 2.1 pts, signaling a gradual fading of global momentum.
Buyers dominate European trading floors, with the main driving force today being the strength of the banking sector; stock indices in Frankfurt and Paris are up over 1%, while Milan's FTSE MIB has surged more than 2%. Market calming and the return of risk appetite are confirmed by a sharp drop in the VIX volatility index, which is down more than 6% today. At the same time, clear sector rotation is visible in the market: Citigroup strategists downgraded US tech stocks in favor of cheaper European markets that are less vulnerable to AI-related turmoil, while hedge funds reduced positions in global Big Tech at one of the fastest paces on record.
FX Market
- EURUSD: The euro strengthens by over 0.4% against the weakening dollar, approaching the 1.12 level.
- GBPUSD: The pound gains over 0.5%, rising toward 1.3420 on the back of improving sentiment in the Old Continent and broad-based selling of the US currency.
- NZDUSD: The New Zealand dollar is today's top gainer, rising nearly 1% following the parliamentary elections that secured a second term for Christopher Luxon. The strong rally in the "kiwi" pushed the AUDNZD pair toward 2-month lows, even though the Australian dollar itself (AUDUSD) also gains around 0.7% against the weakening USD.
Commodities Market
- Copper contracts gain over 1%. While end-user demand remains moderate, the market is facing a severe shortage of physical metal: inventories in Shanghai warehouses have dropped to under 34k tonnes (less than one day's consumption in China), and supply to the Chinese market is constrained by DRC authorities halting over 500 trucks carrying mined material. As a result, physical cash premiums in Shanghai tripled within two weeks, and import surcharges surged by over 40% (a record since 2017).
- Brent crude falls by around 3%, while WTI slips below $90, losing over 2%. Oil is deepening last week's declines, as investors' sentiment was heavily influenced by Donald Trump's remarks suggesting a pause on further military strikes, alongside reports of possible steps toward de-escalation and peace talks regarding Ukraine, which noticeably reduced the geopolitical risk premium in crude prices.
- Gold gains over 1%, consolidating near $4,100 per ounce (up nearly 4% week-on-week), supported by a weaker US dollar and sustained central bank reserve buying.
European Equities
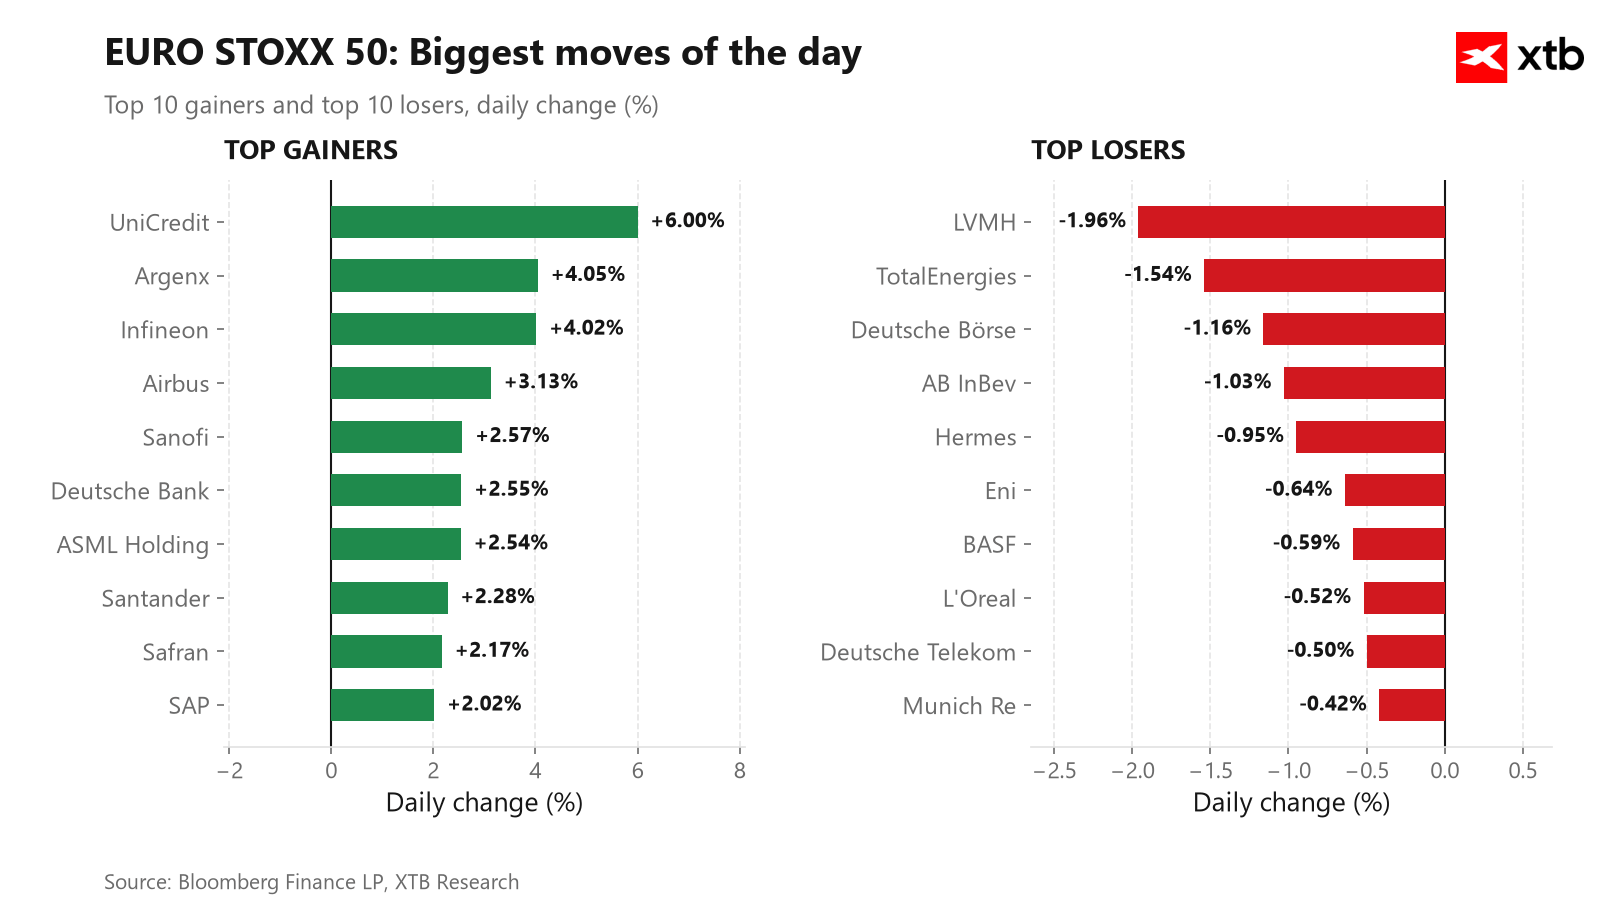
Top Gainers:
- UniCredit SpA (UCG.IT): Shares of the Italian bank are soaring, driven by strong quarterly earnings, an upgrade to its full-year net profit target to above €11.5 billion, and the announcement of an interim dividend of an impressive €3 per share (up over 5%,).
- Argenx SE (ARGX.BE): Shares of the biotech company rise following the acquisition of US-based Unnatural Products for up to $1.15 billion, significantly bolstering its peptide drug development platform (up over 4.5%).
- Infineon Technologies AG (IFX.DE): The chipmaker's shares gain, benefiting from a rebound in European semiconductor sentiment and incoming orders for power management components for AI data center infrastructure (up over 3%).
Top Losers:
- LVMH Moët Hennessy Louis Vuitton (MC.FR): The company leads declines, weighed down by concerns over weakening consumer demand in China and cautious outlooks for the luxury goods sector as a whole (down nearly 2.5%).
- Hermès International (RMS.FR): The stock trends lower, following broader cooling sentiment and profit-taking across the European fashion and premium luxury sector (down around 1.5%).
- TotalEnergies SE (TTE.FR): Shares of the French oil major face selling pressure, tracking lower crude oil prices in global markets following geopolitical de-escalation (down over 1.5%).



US OPEN: Falling Oil Prices and Dip-Buying Fuel Rebound as Nvidia falls

The Week Ahead


Nvidia’s Problems: A CEO's Scandal and Competitors Breathing Down Its Neck


Morning Wrap: Taiwan and Asia Are Halting the Chip Crash Despite the Nvidia Espionage Scandal 💡
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.