

- Commodity and bond market volatility likely to remain elevated
- Bond market pressures the White House
- What bond market volatility is telling us
- Room for further upside
- A peculiar bond market sell off
- Will Trump bend to the bond market?

- Commodity and bond market volatility likely to remain elevated
- Bond market pressures the White House
- What bond market volatility is telling us
- Room for further upside
- A peculiar bond market sell off
- Will Trump bend to the bond market?
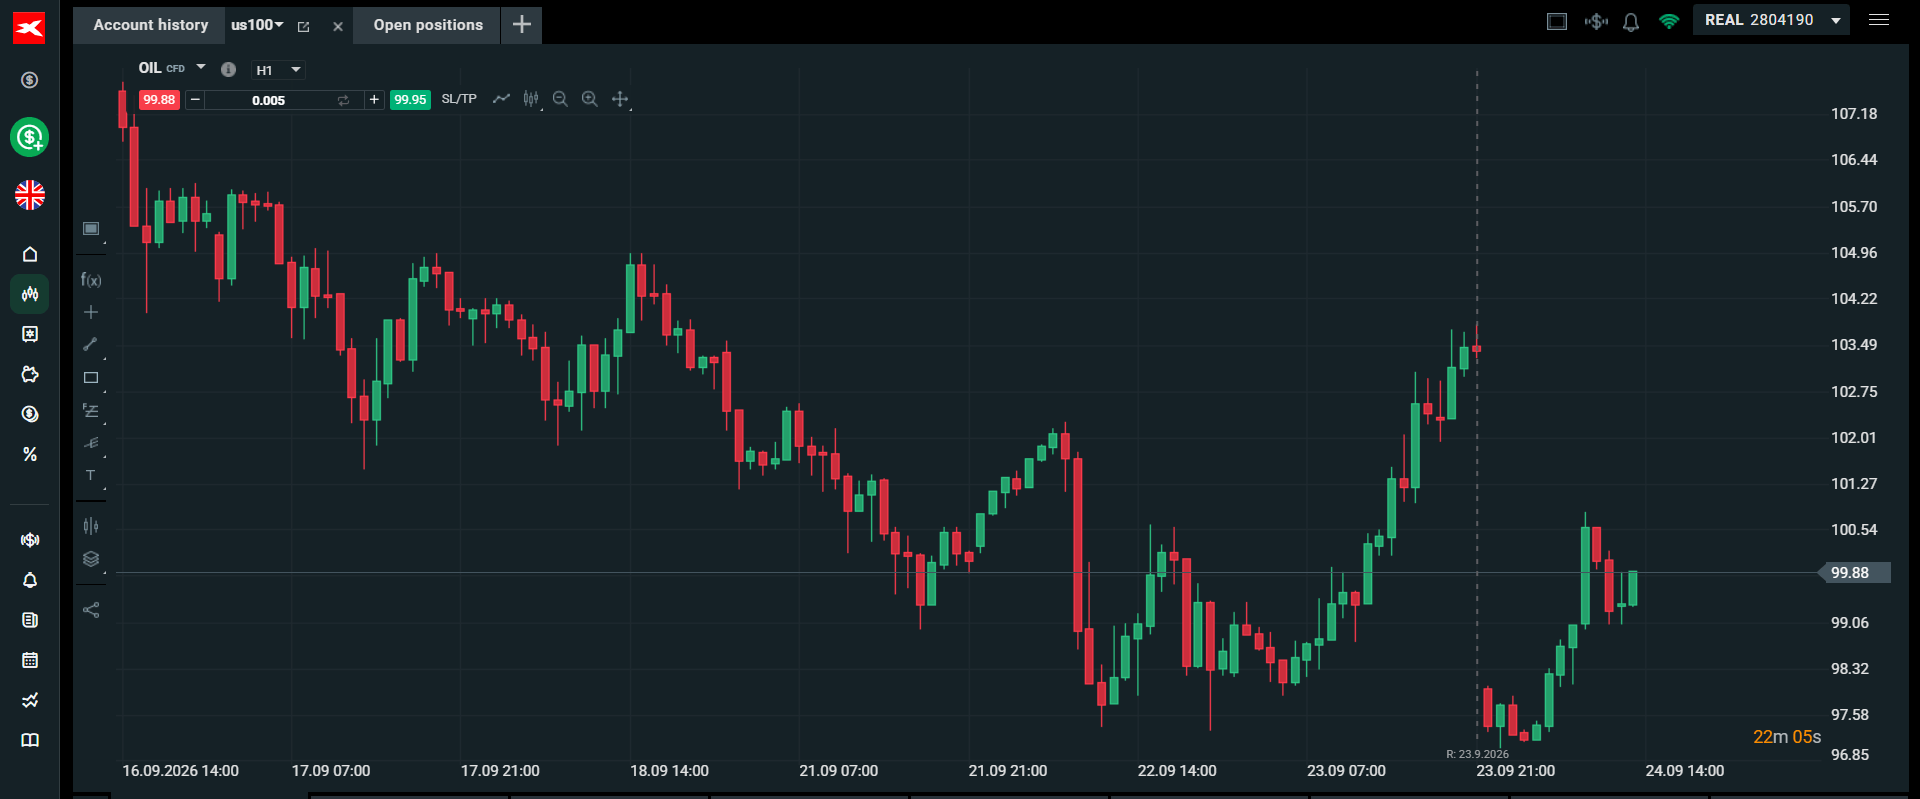
Markets are in recovery mode as we move into the US session on Thursday. Bond yields are bouncing around like a see-saw, up one minute and down the next. Brent crude spiked to as high as $106 per barrel earlier, before dropping 3%, and futures prices are now back below $100 per barrel.
There is no clear direction for markets. Are we in a bond crisis or not? Is the Iran war getting worse or is the situation improving? Are enough oil supplies getting through the Strait of Hormuz, and will Ukraine continue to target Russian refinery infrastructure?
Commodity and bond market volatility likely to remain elevated
While these questions remain unanswered, volatility will continue to dominate, especially in the commodity and bond markets. While equity markets have taken a knock in the last two sessions, the moves have been mild. Movements are fairly moderate in the FX space, although there is a clear preference for the dollar.
Bond market pressures the White House
Overall, even though there has been no clear theme or unifying direction for financial markets, the rise in global sovereign bond yields, 2-year yields are higher by 20bps in the US this week and by 14bps in the UK, are a sign that the bond market is starting to pressure the White House to bring an end to the Middle East war. The yield on long end US yields also rose to two decade highs earlier on Thursday before pulling back.
The average global bond yield is now close to 4%, the highest since 2007. The era of low yields is over and the cost of capital is likely to rise further with more rate hikes expected from the Fed and other major central banks.
What bond market volatility is telling us
It is rare to get movements this volatile in sovereign bond markets, which is another sign that sovereign debt is going through an uncomfortable adjustment period. Why is this? We think it is a combination of rising debt loads and deficits, resilient economic growth and rising inflation risks. These things together are anathema to the bond market and it is no surprise that yields are rising.
Room for further upside in bond yields
The fact that global bond yields have not yet stabilised is a sign that there is room for further upside, even though the 10-year yield is 5.13% in the US, 4.68% in France and 5.34% in the UK. The IMF warned on Wednesday that global public sector spending needs to be reigned in to bring down debt levels to more sustainable levels. However, the US is still borrowing to fund tax cuts and the UK is not showing any willingness to target its fiscal challenges. Thus, it is no wonder that bond markets are in flux.
A peculiar bond market sell off
The current bond market volatility is peculiar since there are no crises brewing in global economies, and developed economies are continuing to grow. The latest PMI data shows that most developed economies are expanding, some at a fast rate including the US. Due to this, a higher level of yields is warranted.
Added to this, if surging Treasury yields were a sign that a fiscal crisis is brewing, then we would expect other US assets to sell off. However, the dollar is still strengthening and moving higher with rising Treasury yields, while the Nasdaq reached a fresh record high earlier this week.
Why yields are likely to remain elevated
If there is a breakthrough in the war in Iran, this would ease pressure on Treasuries and other sovereign bonds, but it would not send yields falling back to pre-war levels due to inflation risks. The inflation crisis we are currently experiencing is a refined product crisis, not only an oil crisis. Diesel and petrol prices are at all time or multi-year highs, which keeps upward pressure on CPI and increases the chance of more interest rate hikes. These factors are driving sovereign bond yields to 2007 highs and beyond.
Will Trump bend to the bond market
In the short term, we think that the oil price and global bond yields will remain closely correlated. However, the Trump/Xi summit is likely to push the Iran war to the backburner for the next day or two. The weekend is when we might see if Trump does bend to the bond market vigilantes, and take steps to ease tensions with Iran. Until then, we expect the US/ China summit to extend the trade truce between the world’s largest economies, which could tame some of the market volatility we have seen in recent days.
Chart 1: Brent crude price, volatility has been elevated this week
Source: XTB



Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)


Bond yields highest since 2007


US Diesel Export Ban: Is It a problem for Europe?


Swiss SNB and Swedish Riksbank decided on interest rates 🍳 SEK and CHF react
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.