


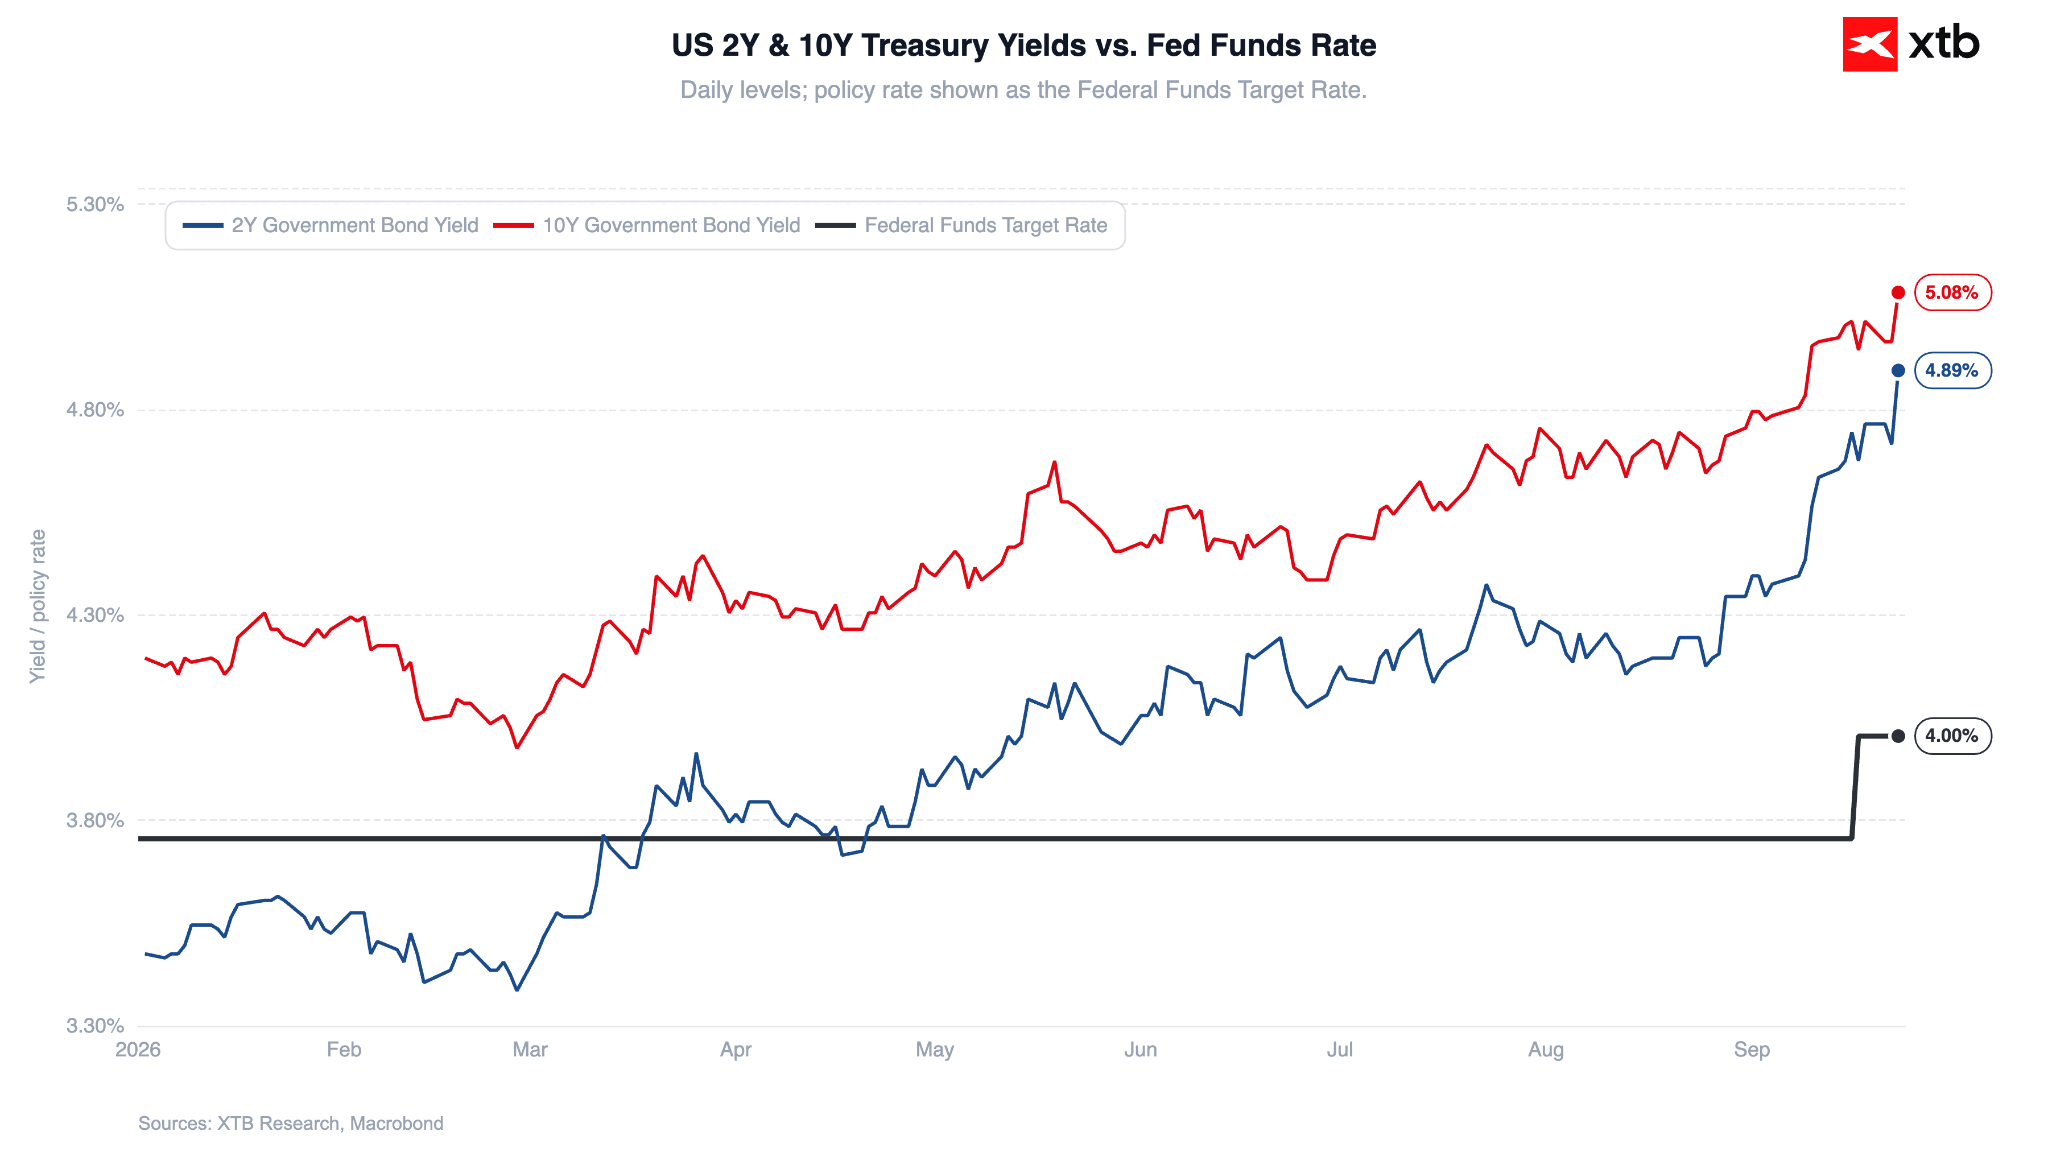
The US market opened lower today, with the S&P 500 (-0.5%), Nasdaq 100 (-0.7%), and Dow Jones (-0.4%) all trading in the red. Higher crude oil and natural gas prices, alongside rising US Treasury yields (with 10-year yields reaching 5.06%), continue to weigh on sentiment.
Market attention is increasingly focused on hawkish commentary from Federal Reserve officials, supporting expectations of further interest rate hikes. This has bolstered the US dollar, with the EUR/USD pair falling 0.5% today and breaking below 1.14 for the first time since July.
Investors are awaiting tomorrow's meeting between Donald Trump and Xi Jinping in Washington.
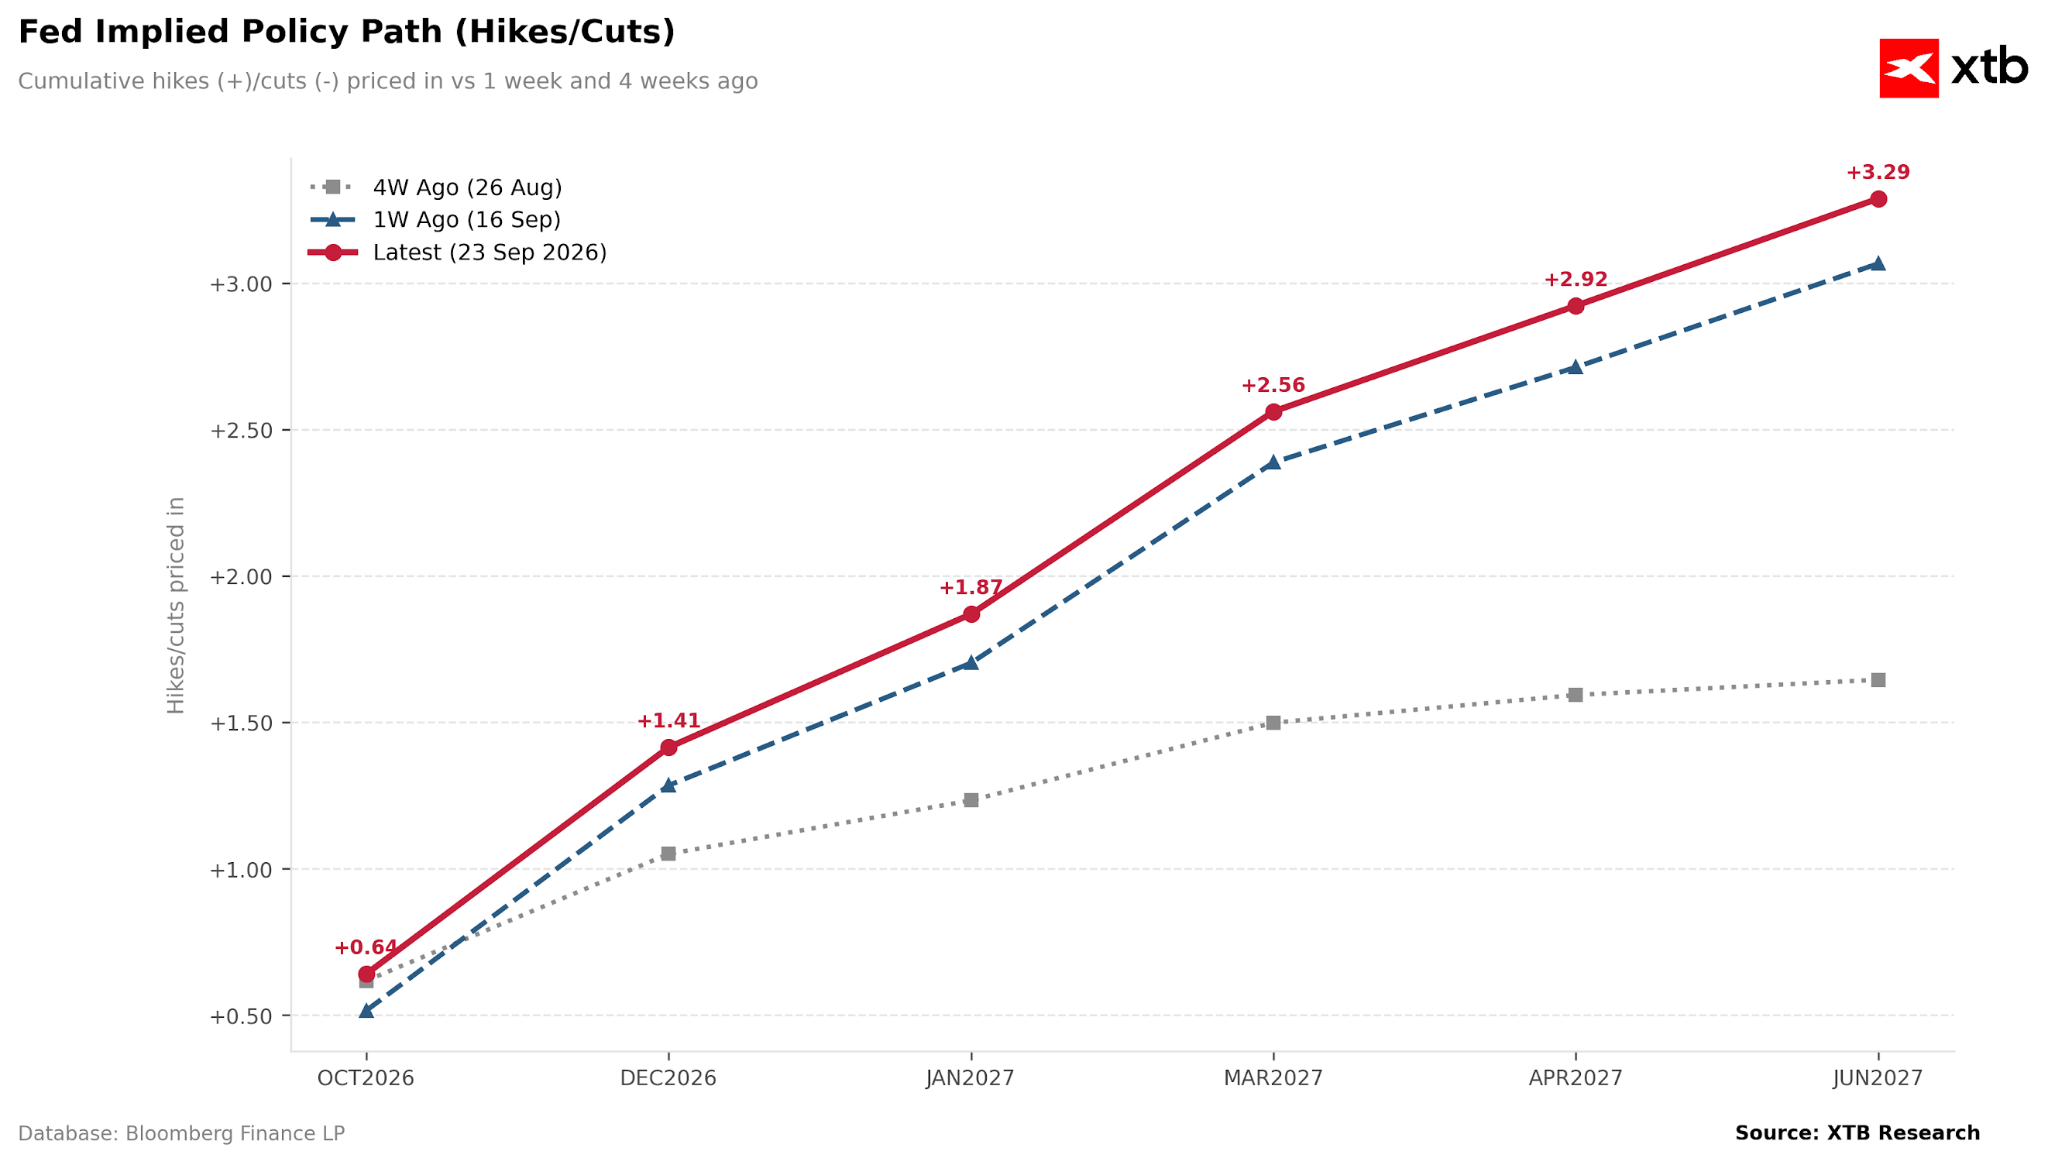
Markets Price in Dynamic US Rate Hikes
The US dollar extended the rally that began two weeks ago, driven primarily by rising expectations of FOMC interest rate hikes. Markets are now increasingly pricing in a rate increase at the October meeting, spurred by exceptionally hawkish comments from Fed officials and robust economic data.
Figure 1: Changes in Market Expectations for Federal Reserve Interest Rate Hikes (2026 - 2027)
 Source: XTB Research, 23.09.2026
Note: The path from 4 weeks ago refers to a lower base (i.e. the interest rate level prior to last week's hike)
Federal Reserve Governor Michael Barr emphasized the need for further rate increases during a speech in Chicago today. He noted that the US economy remains strong and the labour market robust, providing room for further monetary tightening.
Rising expectations of rate hikes are exerting pressure on fixed income markets. US 10-year Treasury yields rose by approximately 14 bps today to 5.08%.
Figure 2: US 2Y & 10Y Treasury Yields vs Fed Funds Rate (2026)
 Source: XTB Research, 23.09.2026
PMI Data Exceeds Expectations Again
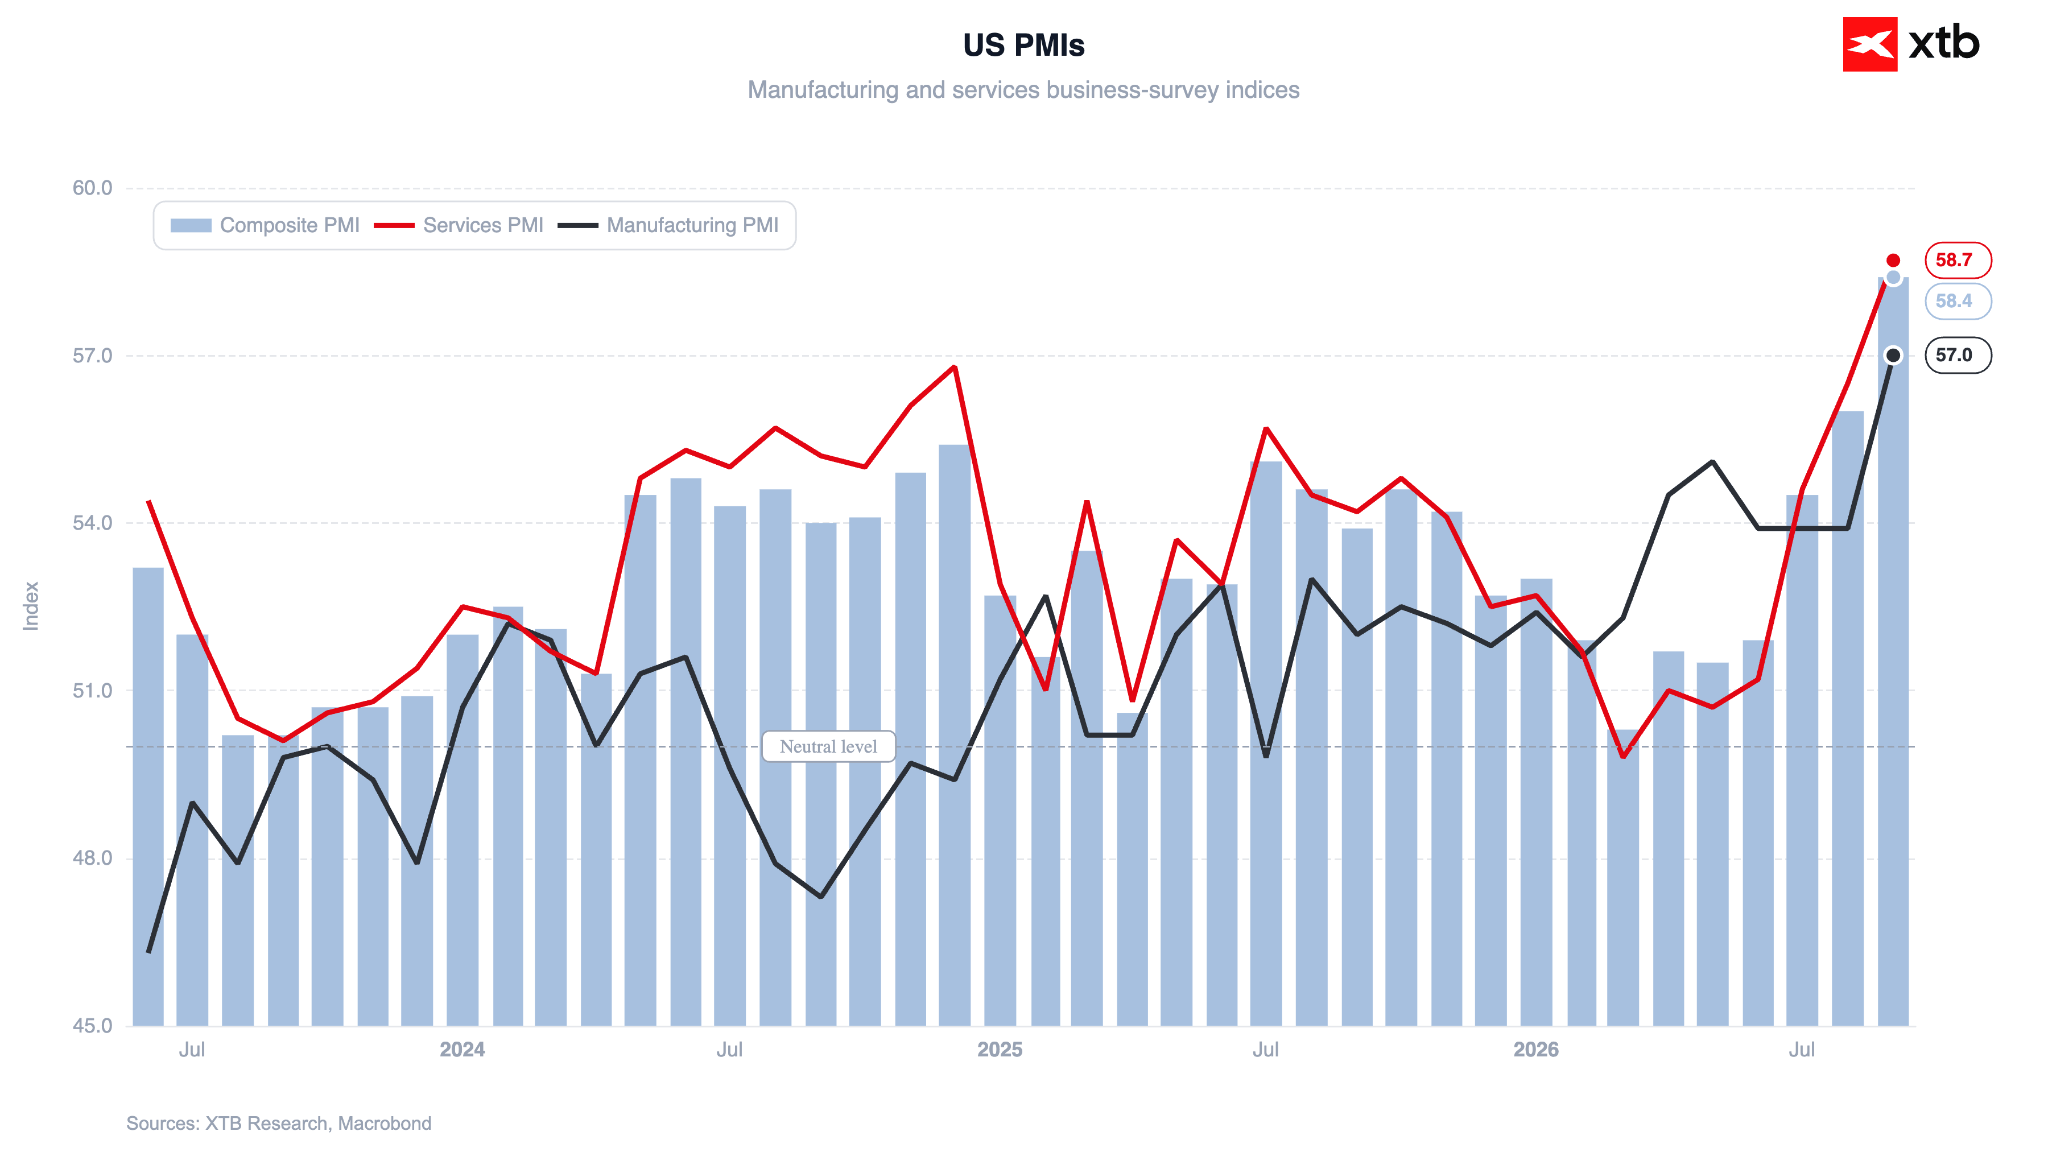
This economic strength was further confirmed today by key leading economic indicators from the US.
Figure 3: US PMI Survey Indices (2023 - 2026)
 Source: XTB Research, 23.09.2026
Indicators for both sectors came in significantly above consensus expectations. The services index rose to 58.7, while manufacturing climbed to 57.0. On a composite basis, these represent the strongest readings in 5 years, consistent with GDP growth of around 5%.
According to S&P's report, conditions in the labour market improved markedly, with firms aggressively expanding headcount to address substantial order backlogs. Furthermore, backlogs accumulated at the fastest pace since May 2022.
Cost pressures intensified once again, with businesses increasingly passing higher costs on to customers.
Oil Snaps Losing Streak
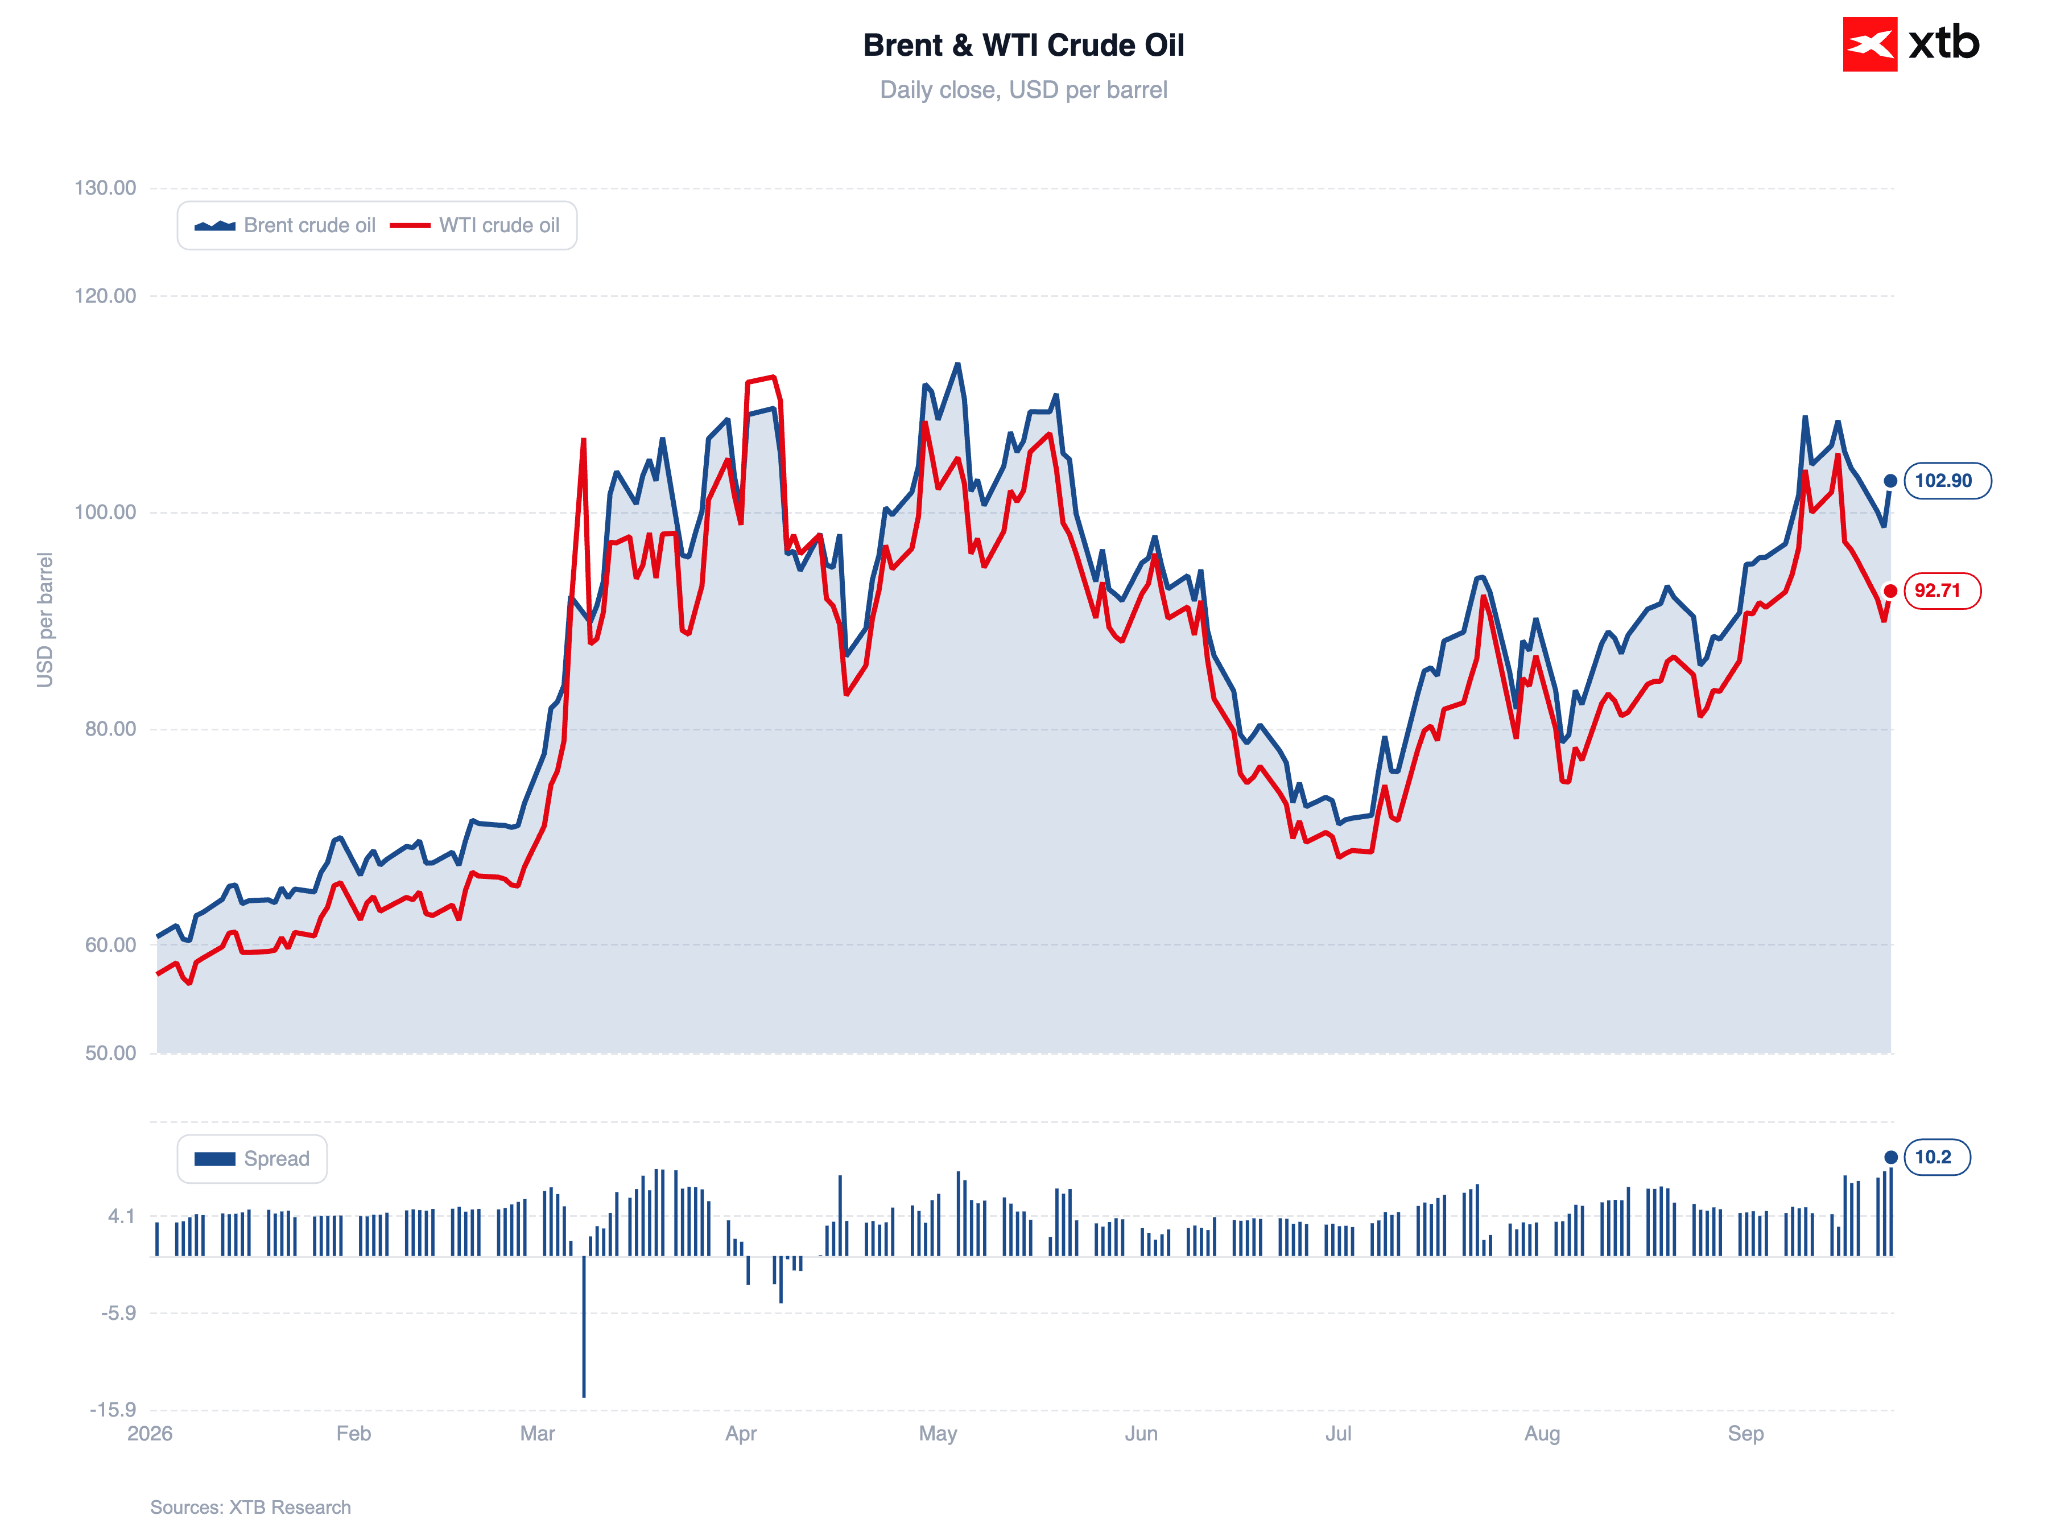
Brent crude gained over 3% today, rising back above $102 per barrel and snapping a multi-day losing streak. WTI rose 2.4% to just under $93 per barrel. President Trump signaled progress in US-Iran talks, though markets appeared largely unfazed by the remarks.
In this context, the US Department of Energy report noted a 3 million barrel increase in crude oil inventories for the week ending 18 September. Meanwhile, both imports and exports fell sharply, by 1.2 million and 1.6 million barrels, respectively. Gasoline inventories also declined (by 1.7 million barrels), while refinery capacity utilization fell to 94%.
Figure 4: Brent and WTI Crude Oil Prices (2026)
 Source: XTB Research, 23.09.2026
Wall Street Pulls Back
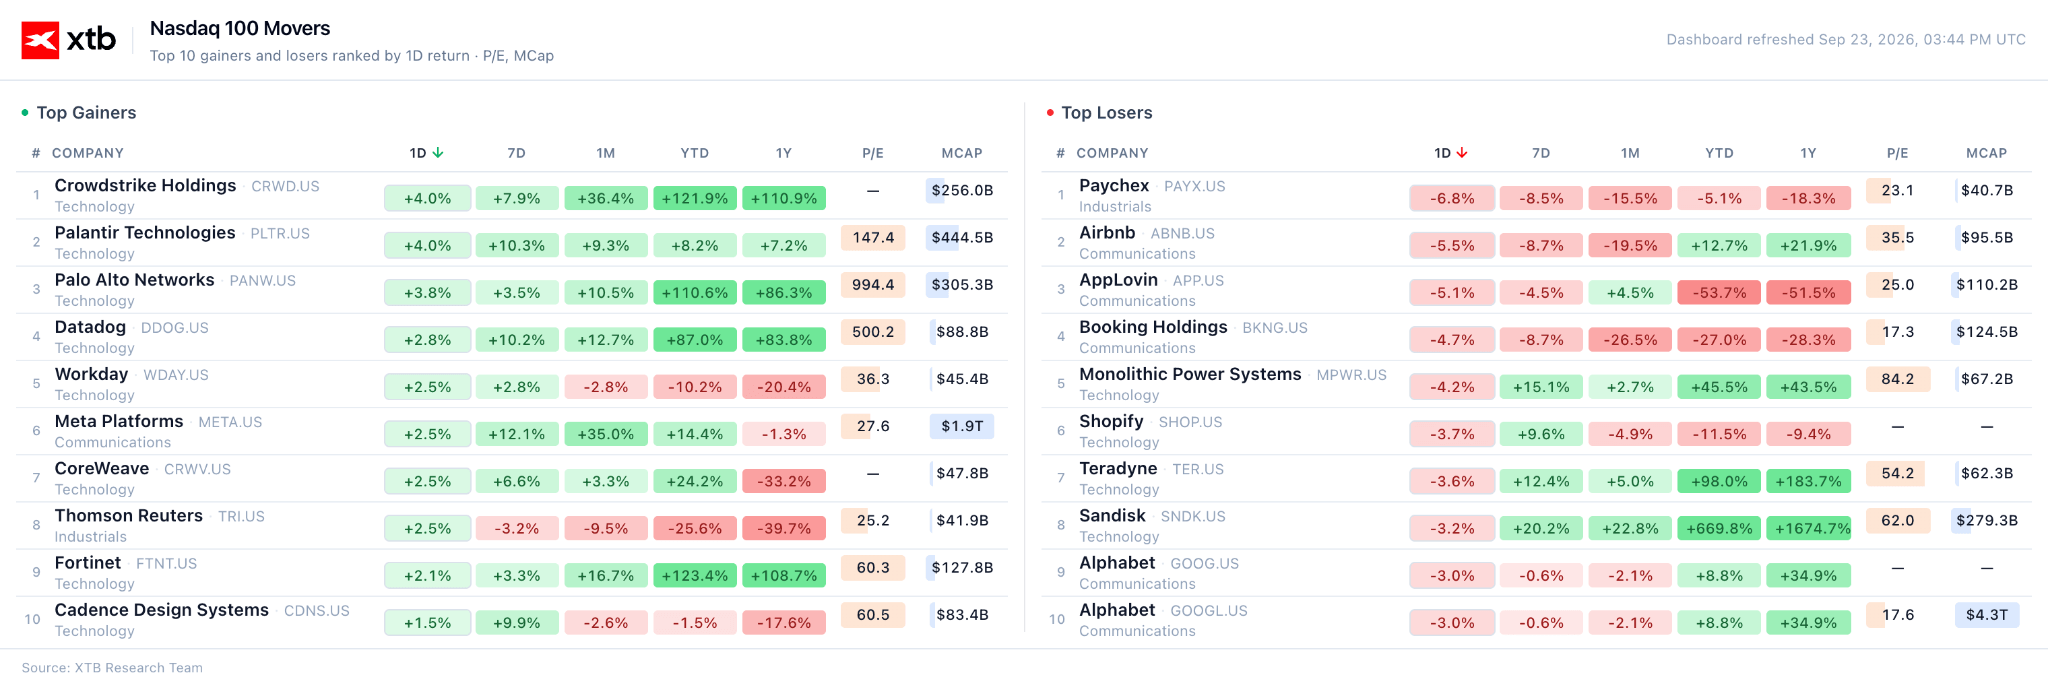
Small-cap stocks and semiconductor manufacturers suffered notable losses today, with the SOXX index falling 1.7% and the Russell 2000 declining 1.4%. Sandisk and Micron gave back some of yesterday's gains, falling 3.0% and 1.8% respectively, while Nvidia dropped 1.6%. The move can be attributed to profit-taking following yesterday's record high on the Nasdaq 100, as well as rising oil prices and higher US Treasury yields.
Figure 5: Top Gainers and Losers in the Nasdaq 100 (23.09.2026)
 Source: XTB Research, 23.09.2026
Meta: Star of the Month
Meta shares advanced once again (+2.7%), edging closer to their best monthly performance since July 2013. The stock has surged 32% in September, driven primarily by growing interest in its AI agent, Muse.
This has led to sharp declines in companies identified by Meta as integration partners for Muse, or competitors in areas the agent could dominate: Expedia dropped 6.8%, Booking fell 4.4%, and Airbnb fell 5.7%.
High-Level Summit
In the background, attention remains focused on Thursday's summit between President Trump and Xi Jinping, accompanied by a dinner for select US business leaders. Last week, Mr. Trump stated that he anticipates "a lot of different agreements".
Company News
Cracker Barrel ($CBRL.US)
Shares in the restaurant chain surged nearly 10% after fourth-quarter adjusted EPS beat analyst expectations, and full-year 2027 adjusted EBITDA guidance also came in above consensus.
Royal Caribbean ($RCL.US)
The cruise operator agreed to acquire a 50% stake in Sandals Resorts International for approximately $3bn. The transaction gives the company access to a Caribbean network of all-inclusive resorts.
General Mills ($GIS.US)
The food manufacturer reported first-quarter revenue growth ahead of Wall Street expectations, shifting strategy from previous price reductions to new product launches.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)


Bond yields highest since 2007


US Diesel Export Ban: Is It a problem for Europe?



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.